From freshwater staples to premium seafood: India’s quiet dietary transition

While India’s fish consumption has been dominated by freshwater species, high-value marine fish and shrimp are expanding their footprint. In this post, Bandyopadhyay and Joshi discuss how this transition is reflective of broader changes in income, urbanisation, technology-driven market access, and consumers’ nutrition awareness. They highlight the role of policy in ensuring affordability, strengthening environmental stewardship, and developing robust domestic markets.

India’s fish consumption patterns are undergoing a significant but under-recognised transformation. For decades, freshwater species such as rohu, catla, and mrigal dominated household diets, shaped by affordability, accessibility, and deeply rooted culinary traditions. Today, new evidence from the National Sample Survey (NSS) 2011-12, NCAER’s (National Council of Applied Economic Research) 2021 household survey and projections up to 2025, shows a gradual but persistent shift toward a more diversified seafood basket that includes high-value marine fish and shrimp. This transition reflects broader changes in income, urbanisation, technology-driven market access, and consumers’ rising nutrition awareness.

Freshwater species continue to account for about two-thirds of household fish consumption in India. But their share is eroding as marine varieties (26%) and shrimp (4%) expand their footprint. Though shrimp still represents a small fraction of household consumption, its growth rate is substantially higher than any other category. A combination of rising middle-class incomes, the expansion of cold-chain networks, and spillovers from export-oriented aquaculture are all helping restructure domestic demand. As more households shift from seeking “more fish” to “better fish”, consumption is becoming increasingly aspirational.

Emerging geographic clusters of demand

One of the most striking aspects of this transition is the emergence of new geographic clusters of seafood demand. Traditional coastal consumers in Kerala, Goa, Tamil Nadu, and Puducherry remain important, but demand is widening both eastwards and northwards. In Odisha and West Bengal, once dominated by freshwater and brackish-water species, urban households increasingly include shrimp as an occasional complement to traditional choices. In landlocked states such as Tripura, Meghalaya, and parts of northern India, marine fish consumption is rising due to improved cold-chain integration and the availability of frozen and ready-to-cook products.

Digital retail has accelerated this shift. Hyperlocal seafood delivery platforms in Kolkata, Bengaluru, Kochi, Chennai, and Guwahati have expanded access by offering cleaned, packaged, and hygienically handled fish delivered to the doorstep. This technology-led “democratisation of seafood retail” has made species once confined to coastal markets available across cities. In many ways, India’s seafood transition mirrors earlier changes in the poultry sector — where modern retail scaled up supply while transforming consumer expectations of hygiene and convenience.

Nutrition and equity implications

This evolving consumption pattern has broad nutritional implications. Fish remains one of the most affordable and bioavailable sources of high-quality protein, omega-3 fatty acids, and essential micronutrients. For low-income households facing persistent protein-energy deficits, even modest increases in fish consumption can translate into significant health gains.

However, the ongoing premiumisation of seafood raises equity concerns. The price differential between low-cost freshwater fish and higher-value marine or shrimp varieties may widen as demand for the latter grows faster than supply. Without policy attention, diversification in the seafood basket could reinforce nutritional inequality—where affluent households move up the value chain while poor households continue to rely exclusively on low-cost freshwater species.

A balanced approach is needed: strengthening the supply of affordable freshwater fish while supporting innovation and growth in high-value aquaculture. Policymakers can play a critical role by reducing price distortions, improving market infrastructure, and promoting species diversification in freshwater aquaculture that widens consumer choice without straining household budgets.

Environmental and sustainability considerations

Any analysis of India’s fish consumption must be situated in the broader ecological context. With aquaculture contributing more than 70% of total fish output, sustainability concerns are becoming increasingly salient. Intensive shrimp farming, while profitable, is associated with water pollution, soil salinity, disease outbreaks, and high feed dependency. These risks are amplified when production expands without adequate environmental safeguards.

Several states are responding by adopting cluster-based aquaculture models supported by water management protocols, biosecurity guidelines, and common infrastructure facilities. Andhra Pradesh and Odisha offer promising examples where production efficiency has been improved alongside environmental safeguards. Scaling such models, and promoting innovations in low-impact aquaculture systems, is essential for aligning India’s growing seafood demand with ecological sustainability.

The underdeveloped domestic market

Despite being one of the largest fish producers in the world, India’s domestic market remains an underleveraged opportunity. Historically, policy attention has tilted towards export promotion, particularly for shrimp. But domestic demand is now emerging as a major driver of sectoral growth. Harnessing this opportunity requires investment in cold-chain infrastructure, refrigerated transport, modern retail formats, and product standardisation.

Ready-to-cook, filleted, and hygienically packaged fish products have particularly high potential in urban markets, where younger consumers increasingly prioritise convenience. Strengthening domestic value chains can reduce post-harvest losses, ensure consistent quality, and support better price realisation for farmers and fishers.

Equally critical is the need for regular household consumption surveys and forecasting tools. Reliable data on household demand, species preferences, and price sensitivity can guide production planning, reduce mismatch between supply and consumption patterns, and support evidence-based policymaking.

A broader socioeconomic shift

India’s shift “from freshwater staples to premium seafood” reflects more than changing tastes. It signals deeper transformations in household income, mobility, market integration, health awareness, and aspirations. If managed well, this transition can deliver a triple dividend: improved household nutrition, higher incomes for fishers and aquaculture farmers, and a more sustainable seafood economy.

However, achieving this will require policy to move beyond production-centric strategies. A future-ready approach must integrate three priorities: ensuring affordability, strengthening environmental stewardship, and developing robust domestic markets. The transformation underway in India’s seafood consumption is ultimately a story of how a country can modernise its diet while balancing tradition, sustainability, and equity — a balance that will determine the long-term resilience of both households and the fisheries sector.

Saurabh Bandyopadhyay is Senior Fellow and Laxmi Joshi is Felllow at NCAER. Views are personal.
India’s shrimp exports must seek to diversify

India’s shrimp industry – one of the country’s most globally competitive export sectors – stands at a defining crossroads today.

ndia’s shrimp industry – one of the country’s most globally competitive export sectors – stands at a defining crossroads today. For years, the United States served as its top and most lucrative export destination, especially for frozen shrimp under HS Code 030617. However, this dependence turned into a vulnerability in August 2025 when the U.S. sharply increased tariffs on Indian shrimp, triggering significant trade distortions that rippled across India’s coastal economy. The cumulative duty rose to an unprecedented 58.26 per cent – combining 5.77 per cent countervailing duty, 2.49 per cent anti-dumping duty, a 25 per cent reciprocal tariff, and an additional 25 per cent penalty tariff linked to India’s Russian energy purchases.

As the U.S. accounted for over 37 per cent of India’s shrimp shipments in 2024, the shock was severe: exporters lost competitiveness overnight, and farm-gate prices crashed by 8-20 per cent. Andhra Pradesh, being the epicentre of shrimp production and export,has been severely affected, followed by Bengal, another crucial production centre, which produces nearly 70,000 tonnes of shrimp every year, 85 per cent of which is exported, earningapproximately Rs 8,000 crore annually from the export of frozen shrimp, with nearly 80 per cent of the revenue coming from the US. These tariff shocks severely shook these shrimp markets. The episode exposed how dangerously over-concentrated India’s shrimp export basket had become, and how a single policy intervention by a dominant partner could destabilise an otherwise high-growth sector.

Recognising the gravity of the crisis, the Government of India moved swiftly to restore stability and create a more “level playing field” for producers. The Export Promotion Mission (2025-2031) places certification and compliance at the centre of India’s long-term shrimp strategy. The government is expanding credit support to help farmers and processors upgrade facilities to meet ASC and BAP requirements – standards that are now essential for entry into high-value markets. Investments in modern testing labs, stronger residue monitoring, and digital traceability systems are aimed at guaranteeing antibiotic-free, fully trackable supply chains that can withstand rigorous EU checks, as India is gearing up to expand its seafood exports, particularly shrimp, to Russia, the European Union (EU), and Australia, offering much-needed relief to domestic fisheries struggling under steep US tariff. Upgrading processing plants to global benchmarks ensures consistency, food safety, and smoother clearance in Europe, where compliance failures often result in shipment rejections and market losses.

By strengthening farm biosecurity, enforcing tighter quality controls, and promoting transparent sourcing, these measures help India shift from volume-driven exports to premium, certified products. Additionally, policymakers should need to recognise the need to support other shrimp categories beyond HS 030617 – such as HS 030616, 030635, and 030636 – which currently contribute a minimal share to exports but hold untapped potential and can reduce market concentration risks if strengthened. As India recalibrates its export strategy, global trade patterns offer promising avenues for diversification. Non-U.S. markets have already increased their share from 51 per cent in 5MFY25 to 57 per cent in the same period this year – a significant shift shaped by demand from China, Vietnam, Japan, the EU, the UK, Russia, South Africa, and the Middle East.

China, now India’s second-largest market, shows consistently strong demand for frozen shrimp and has become a stabilising anchor amid U.S. volatility. Japan and South Korea offer premium, stable markets, although they require stringent adherence to quality standards and competition from Vietnam. The European Union and the United Kingdom present a renewed opportunity, especially as India advances trade negotiations that could reduce tariff disadvantages. Russia offers especially attractive openings with tariffs around 3 per cent and a history of high Indian market share. Vietnam serves as a major re-export hub, with Indian shipments doubling for processing and onward sale. Several African nations – notably South Africa – have also emerged as new demand centres, though purchasing power fluctuations require careful market development.

These markets favour value-added items such as breaded, ready-to-cook, seasoned, and vacuum freeze-dried shrimp, offering India an opportunity to diversify its product mix rather than relying predominantly on bulk frozen varieties. Therefore, it is high time to focus on building structural resilience rather than responding reactively to external shocks. India needs a three-pronged long-term strategy: diversify both export destinations and product profiles; scale up certifications, digital traceability, and biosecurity to meet the high-compliance requirements of key markets; and develop value-added processing capabilities to move up the global seafood value chain.

Strengthening production and exports under other HS codes-030616, 030635, and 030636 – will distribute risk and unlock new market opportunities. Finally, aligning aquaculture policies with sustainability, disease management, and global regulatory expectations will ensure a stable supply and higher farmer incomes. The recent turbulence in the U.S. market is a reminder that India’s shrimp success story cannot rest on a single pillar. With strategic policy support, diversified markets, and upgraded capabilities, the sector can not only recover but also emerge stronger, more competitive, and more globally integrated in the years ahead.

The writers are, respectively, a Research Associate and Professor at the National Council of Applied Economic Research. Views expressed here are personal.

The Missing Link in India’s Growth Story: Women, Work, and Care

India’s ambitions of fast and inclusive growth sit uneasily with one stubborn fact: most working-age women are not in paid work. This is puzzling at first glance. Women’s education levels have improved steadily, health outcomes have seen major gains, and aspirations have risen across generations. Yet participation in the labour market remains strikingly low. This disconnect is not just a social concern, it is an economic one. When women are unable to enter or remain in paid employment, households lose income, firms lose talent, and the economy forfeits a major source of growth.

Two constraints stand out. First, women shoulder a disproportionate share of unpaid care work, including childcare, eldercare, and domestic tasks which sharply raises the opportunity cost of participating in paid employment. Second, India lacks a formal framework for part-time employment, depriving workers of flexible, legally protected work arrangements that could help reconcile paid work with care responsibilities. My recent research, jointly with Dr. Ratna Sahay at the Centre for Gender and Macroeconomy, National Council of Applied Economic Research, New Delhi quantifies how addressing these twin barriers could substantially raise women’s labour force participation in India. Popular print media Economic and Political Weekly has also carried this research here: Women’s Labour Market Potential | Economic and Political Weekly.

The weight of invisible work

Across the world, women spend more time than men on unpaid care work, but the imbalance is especially stark in India and South Asia. Time-use data show that Indian women devote roughly twice as many hours as men each day to domestic and caregiving activities. These responsibilities cut across income groups and regions, reflecting deeply embedded social norms around gender roles.

The economic implications are profound. Most jobs in India demand long hours, fixed schedules, and daily commuting. When care responsibilities fall almost entirely on women, paid work becomes difficult to sustain, particularly during life stages such as childbirth or eldercare. Many women respond by withdrawing from the labour force altogether or by taking up informal, low-quality jobs that offer flexibility at the cost of security and progression. While the qualitative link between care responsibilities and women’s employment is well recognised, there is surprisingly little quantitative evidence on how much women’s labour force participation could increase if these constraints were eased.

Why part-time work matters

Globally, part-time employment has been one of the most important ways women stay connected to the labour market. In many advanced economies, part-time jobs are formally recognised, legally protected, and paid on an hourly or pro-rata basis. These arrangements allow workers to balance paid work with care responsibilities without being pushed into informality.

India is an outlier. Labour laws define full-time work but remain silent on part-time employment. Minimum wages are specified per day rather than per hour, and workers with shorter schedules are often treated as casual labour, excluded from social security and basic protections. For women seeking flexibility, this legal vacuum leaves few good options. The absence of formal part-time work effectively turns care responsibilities into a barrier to employment. This legal vacuum discourages both workers and employers from engaging in formal part-time arrangements. For women in particular, the lack of secure, flexible jobs reinforces labour market exit during key life stages such as childbirth or eldercare responsibilities.

A quantitative approach to women’s labour supply: What the research shows

Using a standard job-search model adapted to Indian conditions, Dev and Sahay (2026) examine how unpaid care work and job flexibility shape women’s labour supply decisions. The model builds on established job-search frameworks, capturing a simple but powerful idea: people accept jobs only when wages compensate not just for time spent working, but also for time taken away from unpaid responsibilities.

A central concept in this framework is the reservation wage, the minimum wage at which a person is willing to accept a job. Higher care burdens raise this threshold, making labour force participation less attractive. Calibrated with Indian data, from the Periodic Labour Force Survey, the Time Use Survey, and CMIE’s Consumer Pyramids, the model mirrors key features of the labour market today. Women face higher thresholds for accepting jobs because the opportunity cost of paid work is higher for them.

Simulating the policy reforms, two results stand out. Formalising part-time work on its own makes employment more attractive to women. But the largest gains emerge when flexible jobs are combined with a more equal sharing of care work between men and women. Under this combined scenario, female labour force participation rises by six percentage points, from about 37% to 43%, a sizeable increase by macroeconomic standards.

Lessons from elsewhere

Other countries offer useful reference points. In much of Europe, part-time workers receive the same legal protections as full-time employees, adjusted for hours worked. Scandinavian countries pair flexible work arrangements with generous parental leave and public childcare, enabling women to remain in paid employment across life stages. India’s labour framework has yet to make this shift. The lack of legal recognition for part-time work continues to funnel women into informality or out of the workforce altogether.

Countries Weekly cut-offs for part-time employment Maximum weekly work hours for full-time employment
FranceSpain

United Kingdom

Japan

Norway

Sweden

India

24 hours < Work hours < 35 hoursWork hours < 40 hours

Work hours < 40 hours

20 hours < Work hours < 30 hours

Work hours < 37.5 hours

Work hours < 40 hours

Not defined in labour laws

35 hours40 hours

35 – 40 hours

40 hours

37.5 hours

40 hours

48 hours

Table 1: Examples of Statutory/Statistical Definition of Part-time & Full-time Employment 

Broader economic implications

Raising women’s labour force participation has benefits that extend beyond gender equality. Higher participation increases the effective labour supply, boosts household incomes, and supports economic growth. Formal part-time employment can also improve job quality by bringing more workers under the ambit of labour regulation and social security. Moreover, redistributing unpaid care work can have intergenerational benefits. When care responsibilities are shared more evenly, women are better able to invest in their careers, while children benefit from improved household wellbeing and potentially higher public investment in care infrastructure.

Policy priorities

Our findings point to several policy priorities. First, India should formally recognise part-time employment in labour law, with clear definitions, hourly minimum wages, and pro-rata access to social security and workplace protections. This would align India with international best practices and expand the range of viable job options for women. Second, care policies must move to the centre of economic reform. Public investment in affordable childcare and eldercare services can directly reduce the unpaid care burden. Equal and well-paid parental leave for both parents can encourage a more balanced division of care from early stages of family life. Third, workplace flexibility, including remote work and adjustable schedules should be encouraged where feasible, supported by appropriate regulation to prevent abuse. Finally, sustained efforts to shift social norms around gender and care are essential for long-term change.

As India looks ahead to 2047, the question is no longer whether the country can afford to invest in women’s work, but whether it can afford not to.

Aakash Dev is an Associate Fellow at NCAER. View are personal.

Invisible drain

Recent studies confirm that India remains a major virtual water exporter, with rice, cotton, and sugarcane — some of the world’s most water-intensive crops — driving this invisible drain

Picture a glass of water. Now imagine it contains not just water but the story of how it travelled through soil, nourished crops, and eventually left India’s shores — not as water but hidden inside a sack of rice or a crate of sugar. This is the essence of ‘virtual water trade’, a concept revealing the fact that water-stressed India is among the world’s largest exporters of water embedded in the crops we ship overseas.

Between 2006 and 2016, research by Anna University found that India exported an average of 26 billion litres of virtual water annually. More recent studies by IFPRI and other institutions confirm that India remains a major virtual water exporter, with rice, cotton, and sugarcane — some of the world’s most water-intensive crops — driving this invisible drain. When India exported approximately 16 million tonnes of rice in 2023-24, it essentially sent away roughly 40 billion cubic metres of virtual water — equal to 17% of the country’s annual groundwater extraction.

If rice grabs headlines, sugarcane — perhaps the most problematic challenge — operates in the shadows. India is the world’s second-largest sugar producer and significant exporter. Sugarcane demands between 1,500 to 3,000 litres of water per kilogramme. Maharashtra — prone to drought — uses a staggering 2,450 litres per kg of sugar, compared to 990 litres in Uttar Pradesh. The math is sobering: sugarcane occupies just 3-4% of Maharashtra’s cultivated area but consumes 60-70% of the state’s irrigation water. This water-guzzling crop has been cultivated on record areas even during drought years, driven by assured procurement and political patronage of sugar cooperatives. India’s sugar exports in 2024-25 reached approximately 775,000 tonnes. With Maharashtra’s water footprint, this translates to billions of litres of virtual water leaving water-scarce regions.

The irony runs deep. India’s agricultural policies — designed to ensure food security —inadvertently incentivise virtual water exports from the most water-stressed regions. The minimum support price regime overwhelmingly favours rice and wheat, creating monoculture patterns divorced from regional water realities. Punjab, where groundwater extraction has reached 164% of sustainable recharge, continues to grow water-intensive paddy. Haryana follows suit at 136%. Between 2003 and 2020, these two states lost 64.6 billion cubic metres of groundwater.

Agricultural exports earned India $41.25 billion in 2020-21, sustaining millions of farming families. Rice exports support livelihoods across Punjab, Haryana, Uttar Pradesh, and Andhra Pradesh. The challenge is not whether to export but how to export sustainably. Research points to several pathways.

States with rain-fed agriculture and better water endowments should become primary sourcing zones for water-intensive exports. Haryana’s ‘Mera Pani Meri Virasat’ scheme, which pays farmers ₹7,000 per acre to shift from paddy to less water-intensive crops, deserves wider adoption.

Rather than eliminating rice and wheat MSPs, expand the basket to include millets, pulses, and oilseeds. Direct income support schemes like PM-KISAN can supplement this transition, maintaining farmer welfare while incentivising diversification.

Gradual shifts toward metered electricity, combined with compensatory cash transfers, could reduce wasteful extraction without hurting farmer incomes.

Micro-irrigation, System of Rice Intensification, and Alternate Wetting and Drying techniques can reduce water use by 30-40% without yield penalties.

The choice is ours: continue exporting water we cannot afford, or redesign our agricultural system to export prosperity instead.

Raktimava Bose and Sanjib Pohit are, respectively, Consultant and Professor at National Council of Applied Economic Research. Views are personal.

Innovation as national strategy: Can India invest its way to Viksit Bharat?

While global innovation leaders invest 2-4.5% of their GDP in R&D, the figure stands at 0.64% for India. In this post, Mondal and Pohit contend that the country ought to recognise R&D as an economic engine, raising public investment and the contribution of the private sector. Further, instead of only playing catch-up, there is a need to proactively develop a technology forecasting strategy.

What drives true innovation – talent, ambition, or opportunity? In reality, innovation is driven by investment: consistent, strategic, and future-oriented spending on research and development (R&D). Nations that dominate the global technology landscape today – whether the United States, Japan, South Korea, or China – did not get there by chance. They got there by investing where the future is. India now stands at a similar crossroads. If we aspire to a Viksit Bharat1 by 2047, India’s sluggish response to R&D cannot be a supporting activity; it must be treated as the economic engine.

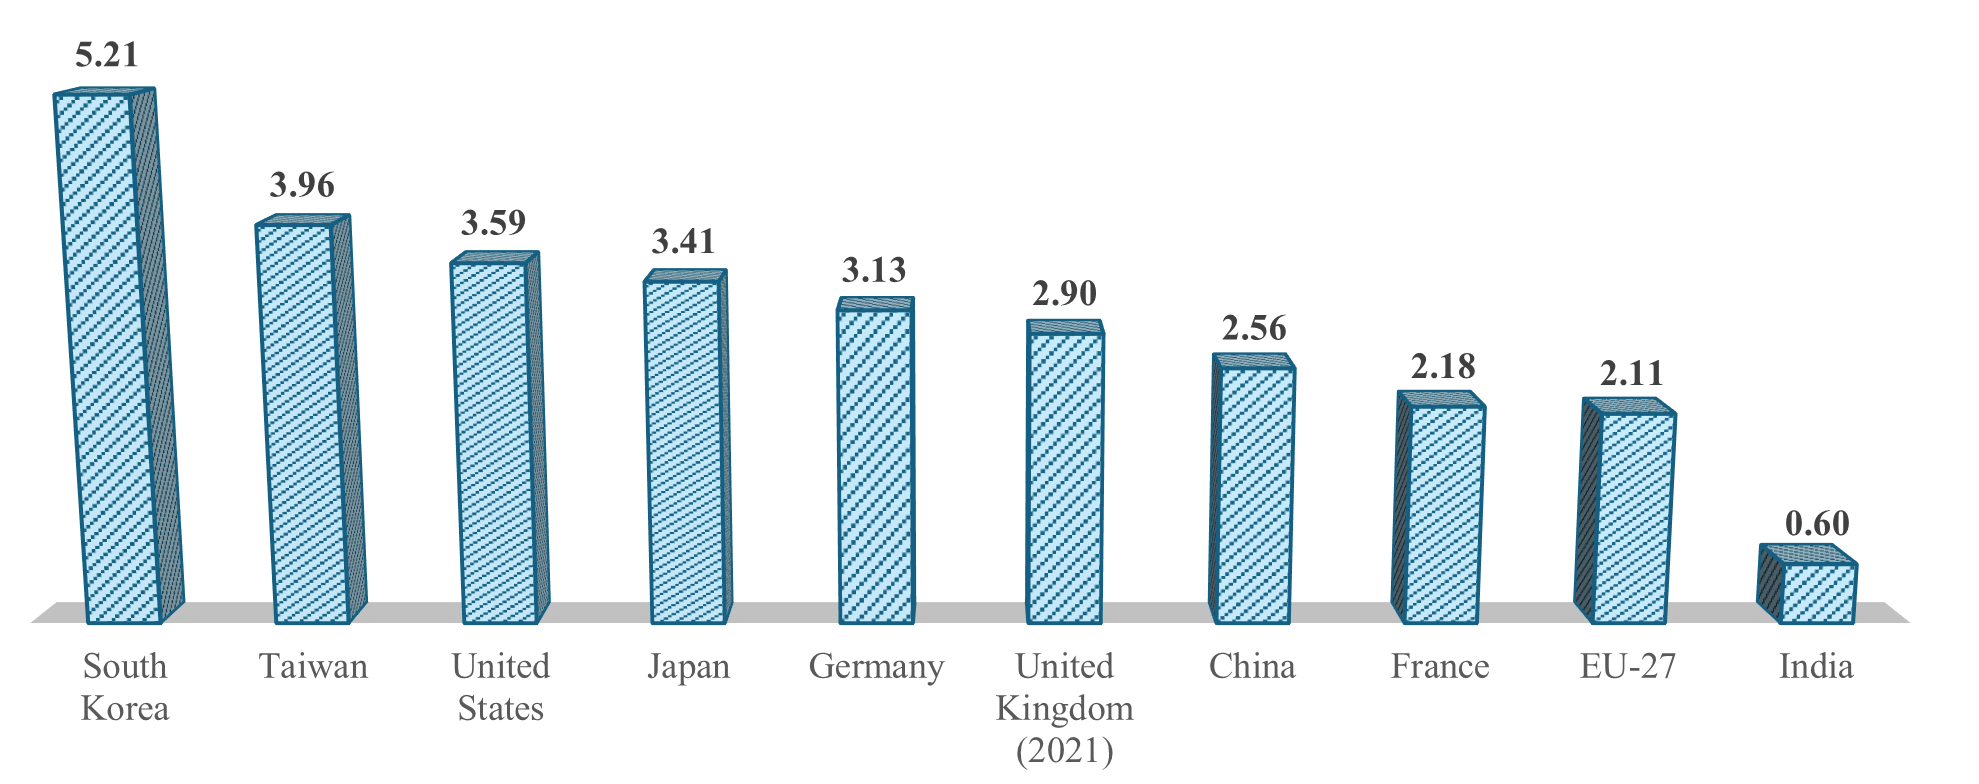
For over a decade, India has urged its industries to innovate and manufacture domestically. Yet, the country’s R&D spending tells a different story. According to the latest national R&D statistics, India’s Gross Expenditure on Research and Development (GERD) stood at 0.66% of GDP (gross domestic product) in 2018-19 and 2019-20, and then dropped marginally to 0.64% in 2020-21. In contrast, the global average is 1.8%, and innovation leaders routinely invest 2-4.5% of GDP. Even smaller East Asian economies – South Korea and Taiwan – invest between 3% and 5% of GDP annually. India’s private sector contributes only 36% to total R&D expenditure, compared to 50-70% in advanced economies.

Figure 1. GERD and GERD-to-GDP ratio, by selected region or country, 2022 or most recent year

Source: National Center for Science and Engineering Statistics, National Patterns of R&D Resources (2021-22 edition); Organisation for Economic Co-operation and Development, State of Industry R&D in India (IIFL Securities, 2024).‍

The result is predictable. India enters late into emerging technology arenas. By the time we master an existing technology, the market has already moved ahead – either up the value chain or into new scientific frontiers. This delays value capture, reduces competitiveness, and limits the gains Indian firms can enjoy from innovation-led growth.

What leading nations do differently

The difference between leading and lagging nations lies in one critical capability: technology foresight. While India has often reacted to global developments, others have anticipated them.

In Japan, technology forecasting exercises involve more than 2,000 top scientists and technologists, mapping out possible technology trajectories over a 25-year horizon. The outputs directly shape budget priorities, industrial strategy, and R&D funding. Japan’s early foresight in robotics and materials science ultimately enabled it to become a global leader in advanced manufacturing.

China’s transformation is even more striking. Its first major foresight initiative dates back to 1956, involving over 1,000 senior scientists who identified long-term science and technology priorities. In 2003, China conducted a major foresight exercise – “Technology Foresight toward 2020” – involving 60 leading scientists and over 320 experts across 32 subfields. Technologies were evaluated not just on scientific potential but on three economic indicators: contribution to economic growth, improvement in quality of life, and national security. Among the top priorities identified were high-efficiency solar cells, advanced biofuels, gene editing, large-scale integrated circuits, antiviral therapeutics, and advanced alloys. Today, China leads in several of those same fields.

Figure 2. Strategic chain followed by global innovation leaders

‍India never institutionalised this rigor. Except for a limited exercise by Technology Information, Forecasting and Assessment Council (TIFAC) in the 1990s, technology foresight never became an annual or systematic function linked to budget allocation. The result: fragmented R&D investment without a sharp national focus.

India’s turning point

India is finally recognising that innovation cannot be left to chance; it must be designed. Over the last few years, major flagship missions have been launched, demonstrating a strategic shift in the government’s approach – linking innovation, investment, and industrial capability. 

The most significant push came in November 2025, when the Government of India launched the Research Development and Innovation (RDI) Scheme Fund, a landmark Rs. 1 lakh crore fund dedicated to catalysing industry-led R&D. For the first time, India’s innovation financing architecture places the private sector – not just government labs – at the centre of R&D expansion. This directly addresses India’s structural bottleneck: the low share of industry-funded research. If India wants products and technologies to reach the market, industry must lead, academia must partner, and government must enable.

Complementing this shift is the India Semiconductor Mission (ISM), launched in 2021. Backed by a Rs. 76,000 crore Production Linked Incentive (PLI) scheme – Rs. 65,000 crore of which is already committed – the mission is creating India’s semiconductor ecosystem. India has approved 10 semiconductor projects across six states, with total investments reaching Rs. 1.60 lakh crore. These include the country’s first commercial Silicon Carbide fabrication plant in Odisha. Semiconductors are the backbone of every modern technology – from smartphones to electric vehicles to national security assets. For the first time, India is not attempting to catch up; it is laying the groundwork to compete.

Similarly, the Deep Ocean Mission (DOM), launched in September 2021 with Rs. 4,077 crore, places India firmly in the global race for deep-sea resources and marine biotechnology. With 7,517 km of coastline and strategic access to deep-sea mineral reserves, India recognises that future resource security will not depend solely on land-based extraction.

Meanwhile, the IndiaAI Mission, approved in 2024 with Rs. 10,371.92 crore, aims to “Make AI in India and Make AI Work for India”. The mission has already expanded computing infrastructure from an initial target of 10,000 Graphics Processing Units (GPUs) to 38,000 GPUs, dramatically improving access for startups, researchers, and enterprises. At a time when global AI compute costs are skyrocketing, enabling public access to AI infrastructure is a competitive advantage.

Beyond missions and budgets, India’s biggest strategic edge is something intangible yet transformative: Digital Public Infrastructure (DPI). Unlike Western economies where digital rails are owned by private corporations, India has built open, interoperable platforms that democratise access to technology.

A notable example is the Unified Payments Interface (UPI). In August 2025 alone, UPI processed over 20 billion transactions worth Rs. 24.85 lakh crore, representing 85% of India’s digital payments. UPI now operates in seven countries—including France, Singapore, UAE, and Mauritius – showcasing that Indian technology can scale beyond borders. UPI proves something fundamental: innovation does not only emerge from high R&D spending; it emerges from public digital infrastructure that fuels experimentation.

DPI is enabling a unique innovation model – frugal, scalable, inclusive, and exportable. But DPI cannot compensate for underinvestment in frontier technologies like deep tech manufacturing, biotechnology, advanced materials, and semiconductors. For that, India must invest significantly more.

However, many of these sectors have been selected based on the experiences of other countries. From the Indian perspective, we need to undertake a deep-down technology forecasting exercise to narrow down the sectors where investment in R&D may give fruits in the next 20 years.

Innovation cannot be purely aspirational – it must be funded

India has the talent, the demographic dividend, and the ecosystem. What we need now is aggressive investment and prioritisation.

If India is serious about becoming a developed nation by 2047, R&D expenditure must rise to at least 2% of GDP over the next decade, with the private sector contributing 60% or more. This is not a cost – it is an investment in economic competitiveness, technological sovereignty, and national power.

Another problem with India’s innovation system is that we are largely engaged in incremental innovation and not breakthrough innovation. Nine out of 10 breakthrough innovations end up failing. In the Indian R&D system, no one wants to be associated with failure, as the committee members of the research grantee or the researchers may come under the CAG (Comptroller and Auditor General) lens for wasteful expenditure.

India’s rise will not be defined by how fast it adopts existing technologies, but by how boldly it invests in creating the next ones – the path to Viksit Bharat begins when India stops catching up and starts setting the pace with other nations in the race.

The views expressed in this post are solely those of the authors, and do not necessarily reflect those of the I4I Editorial Board.

‍Note:

  1. Viksit Bharat, meaning “Developed India”, Viksit Bharat 2047 is the government’s vision to transform the country into a self-reliant and prosperous economy by 2047. Economic growth, technological upgradation, infrastructure development, social empowerment, and sustainability are the criteria of this programme.‍

    Get updates from NCAER