Unemployment figures hide widening job gap in South Asia

While global unemployment dips, South Asia grapples with declining labour force participation and widening job gap that put a generation at risk.

The world has encountered a series of extraordinary events in the last five years that transformed everyday life and economic activity. The COVID-19 pandemic was such an event that brought global affairs to a standstill. The depth and breadth of its impact were so profound that they confounded the expectations of policymakers and altered the collective approach to daily living. In the US, for example, the economic definition of a recession as two consecutive quarters of negative growth was called into question in early 2022. Despite clear economic contractions, the presence of a robust job market and historically low unemployment rates made economists hesitant to declare a recession which is a reflection of the pandemic’s impact.

The International Labour Organisation recently released its World Employment and Social Outlook 2023 which provides an employment forecast for 2024. Echoing the US experience, the report notes that global markets have lost their post-COVID economic momentum, yet the job market remains resilient. According to the ILO, unemployment and job gap levels have reverted to pre-pandemic figures. However, the recovery has been uneven across different geographical regions.

The ILO report casts light on the shifting dynamics of the global labour market as it emerges from the shadows of the pandemic. It offers a prognosis for 2024, mirroring the dichotomy observed in the US, where post-pandemic economic buoyancy has waned, yet the labour market displays unexpected resilience. The disparities highlighted in the report reflect a world where employment situations simultaneously converged and diverged across different regions, setting the stage for a complex narrative of recovery and challenge.

Labour market trends in South Asia

In 2023, the labour force participation rate (LFPR) in South Asia returned to its pre-pandemic downward trajectory. The LFPR has been declining over the past two decades, from 55.7% in 2000 to 51.3% in 2019. It is projected to decrease further to 53.6% in 2024 and 53.5% in 2025, following a temporary increase to 54.2% in 2023 due to the pandemic’s impact.

While countries like Bhutan, India, and Bangladesh are expected to see an increase in LFPR, Sri Lanka and Iran anticipate stagnation. Notably, except for Iran and Sri Lanka, the rate of female labour market participation is rising across the region, led by India. However, the report highlights that a staggering 87% of workers are employed in informal jobs, highlighting a significant lack of decent employment. The region also faces challenges from the gig economy and other new forms of employment.

The economic situation in South Asia, as revealed by the LFPR trends, is one of contrasts and contradictions. While some nations within the region anticipate growth in labour force participation, others brace for stagnation, presenting a picture of economic resilience and vulnerability. This regional disparity not only highlights the diverse economic health across South Asia but also highlights the critical need for tailored economic policies that can address the unique challenges faced by different countries.

South Asia is home to the world’s largest youth population, but the data reveals a troubling trend: a high proportion of young people are not engaged in employment, education, or training (NEET). This poses a long-term risk to their careers. In 2021, Pakistan had the highest NEET rate at 34.6%, followed by India at 28.0%. Furthermore, the proportion of females in NEET is alarmingly high in both Pakistan (56.4%) and India (43.5%).

The profound social implications of these labour trends cannot be overstated. In South Asia, where a substantial segment of the youth remains disconnected from employment, education, or training, the society may face turbulence. This threatens not just the economic stability of the region, but also the social cohesion and future prospects of its young population. Addressing this issue is imperative not only for the economic health of the region but also for securing a socially inclusive future.

Moving beyond unemployment

While the global trend of decreasing unemployment rates continued in 2023, challenges persist in both low-income and high-income countries, where unemployment rates slightly increased or remained stable, respectively. The ILO report goes beyond simple unemployment figures to include the ‘job gap’ indicator. This new metric counts those who wish to work but are currently jobless, expanding the focus beyond those actively seeking or available for immediate employment. Globally, the projected job gap for 2023 is 11.1%, with women facing a larger gap (13.7%) compared with men (9.3%). In South Asia, however, the expected job gap is slightly lower than the global average at 9.3%, yet the gender disparity persists.

As the world grapples with these challenges, the opportunities for reform and innovation in labour markets worldwide become evident. The resilience shown by global labour markets opens avenues for innovative employment policies and strategies that could redefine work in the post-pandemic era. This period of transition presents a unique opportunity for nations to harness the lessons learned from these unprecedented times to foster a more inclusive and resilient economic future.

Furthermore, about 241 million people (6.9% of the global population) were employed but still lived in extreme poverty (earning less than US $2.15/day), and 423 million workers (12.2%) faced moderate poverty (earning less than US $3.65/day) in 2023. Notably, recent data from NITI Aayog reveals that only 11.3% of the Indian population lives in multidimensional poverty. However, India paradoxically records the highest percentage of working poor in the region, at approximately 9.0%. Bangladesh (5.8%) and Pakistan (3.5%) also have significant portions of their working populations experiencing extreme poverty.

The global labour market has shown resilience post-COVID, with falling unemployment and a narrowing job gap. However, South Asia continues to face challenges, including declining LFPR, youth disengagement, and persistent gender gaps. The region also struggles with high levels of informal employment and challenges from the emerging gig economy. Despite some progress, the prevalence of extreme and moderate poverty remains a pressing concern, especially in India. This situation warrants targeted interventions to address the complex issues.

Jyoti Thakur is Associate Fellow at National Council of Applied Economic Research.
The NCAER-NSE Business Expectations Survey for India Fourth Quarter 2023–24

The National Council of Applied Economic Research (NCAER), one of India’s premier economic policy research think tanks, carried out the 128th Round of its Business Expectations Survey (BES) in March 2024, with support from the National Stock Exchange of India Limited (NSE). NCAER has been carrying out the BES every quarter since 1992, covering 500 firms across four regions. The overall business sentiment as measured by the Business Confidence Index rose from 127.6 in the third quarter of 2023–24 to 138.2 in the fourth quarter of 2023–24.

Household expenditure on education dropped after 2010. Three ways to increase investment

In communities where education is given greater importance & viewed as a gateway to success, households are more likely to allocate a larger portion of income toward educational expenses.

Education is the cornerstone upon which nations build their future. It is the bedrock of social and economic growth at the macro level, leading to individual empowerment and social stability. In India, a country with a large population and diverse socioeconomic landscape, understanding the trends in household expenditure on education provides crucial insight into the household’s contribution and participation in building and enhancing human capital.

Toward this, we refer to the National Sample Survey (NSS). The outcome of the surveys has served as one of the barometers for gauging household expenditure trends across rural and urban India. A close examination of the data from the NSS rounds spanning from 1999-2000 to 2022-2023 unveils an intriguing narrative of fluctuations and patterns in education spending. The survey on education spending by households covers expenditure on books, journals, newspapers, periodicals, library charges, stationery and photocopying charges, tuition and other fees, private tuition/coaching centre expenditure, and other expenses like fees for enrolment in web-based training etc.

Ascending trajectory
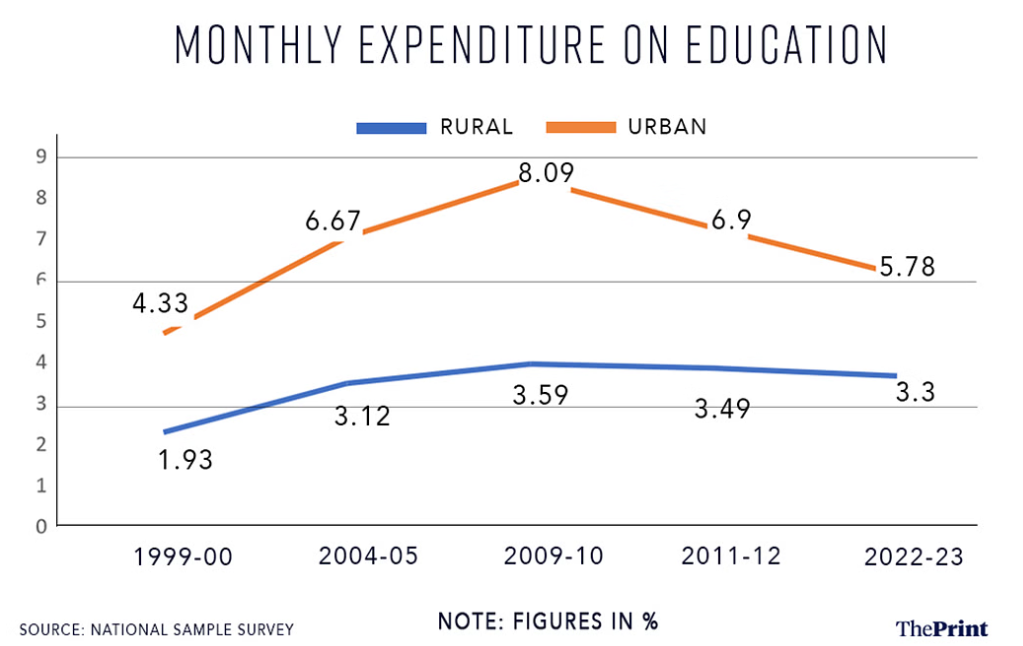
The turn of the millennium witnessed a significant uptick in household expenditure on education. According to data from the 55th round of NSS (1999-2000), rural households allocated 1.93 per cent of their expenditure towards education, while urban households earmarked 4.33 per cent—almost 2.5 percentage points difference. Over the subsequent NSS rounds, this allocation exhibited a commendable upward trajectory. By the 66th round of NSS (2009-2010), the expenditure had swelled to 3.59 per cent for rural households and 8.09 per cent for urban households, with a 4.5 percentage points difference.

Leaving the rural-urban divide gap aside, the rise in household expenditure spending on education could be indicative either of a growing household commitment to higher spending towards education or the rising education cost eating into household expenditure or both factors playing in tandem.

This period also marked a notable phase of prioritisation of education expenditure, driven by various factors including increasing awareness of the role of education in socio-economic advancement, policy initiatives aimed at universalising education, and rising aspirations among the populace.

Plateau and decline post-2010
The upward trend in education spending by households plateaued post-2009-2010, followed by a gradual decline in subsequent years. The 68th round of NSS (2011-2012) revealed a decrease in education expenditure, with rural households’ allocation falling marginally to 3.49 per cent and urban households’ spending falling drastically to 6.9 per cent. The most recent data from 2022-2023 paints a more sobering picture. Rural households allocated 3.3 per cent of their expenditure to education, while urban households dedicated 5.78 per cent. This downward trend raises pertinent questions.

The decline in household spending on education post 2009-10 requires further analysis. Whenever the unit-level data is made available in the public domain, a more in-depth analysis will be forthcoming on the wavering behaviour of education spending by households.

Interpreting trends
Interpreting the trends in household expenditure on education necessitates a comprehensive understanding of the multifaceted factors influencing the spending. Since the survey reflects the “out-of-pocket expenditure” of households, the numbers show that the economic conditions of households as well as the cost of education exert a significant influence on spending habits. It also shows the preference of households for certain educational pursuits.

Government policies and initiatives also play a pivotal role in shaping education expenditure patterns. Increased investment in education infrastructure, scholarships, and subsidies/reimbursements of costs tend to ease “out-of-pocket” spending on education. Conversely, shifts in policies or austerity measures may dampen government expenditure levels and put stress on households as they have to adjust their budgets in response to changing circumstances.

Moreover, societal attitudes towards education, deeply rooted cultural norms and values significantly influence expenditure patterns. In communities where education is accorded greater importance and viewed as a gateway to success, households are more likely to allocate a larger portion of their income towards educational expenses.

Toward inclusive education
As India aims to harness its demographic dividend, it is imperative to ensure equitable access to quality education across all strata of society. Addressing the existing disparities between rural and urban areas necessitates targeted interventions aimed at enhancing accessibility and affordability in underserved regions. The varying patterns in household spending on education underscore the urgent need for collaborative action in constructing a more inclusive and robust educational framework.

First, substantial investments are required in educational infrastructure to bridge the gap between rural and urban areas. This entails developing schools, colleges, and vocational training centres, especially in underserved regions. The availability of infrastructure impacts household spending on education.

Second, policy initiatives to ease the financial burden of education on families, such as scholarships, fee reductions, and income-based loan programs can improve accessibility and encourage wider participation in education.

Finally, involving local communities, parents, and stakeholders in the educational process fosters a sense of ownership and responsibility, thereby maximising education spending and fostering greater social cohesion.

While the fluctuating trends in household expenditure on education present a complex narrative, they also offer valuable insights into the evolving dynamics of education in India. By addressing the underlying challenges and leveraging opportunities for reform, India can chart a path towards a more inclusive, equitable, and affordable education system, thereby unleashing the full potential of its human capital. Higher investment in education should not only be a moral imperative but also a strategic way forward to secure a prosperous and sustainable future.

Palash Baruah is Associate Fellow at National Council of Applied Economic Research (NCAER), New Delhi and DL Wankhar is a retired officer of the Government of India. Views are personal.

Raw deal for women in the fisheries sector

Despite making significant contributions and accounting for a large share of the workforce, women’s concerns and interests are frequently disregarded.

India is second only to China in fish production. In 2022-23, India produced around 18 million tonnes, accounting for 8 per cent of global production. About 32 per cent of this came from marine sources, and 68 per cent from inland sources. The fisheries sector contributes 1.09 per cent to India’s GVA, and over 6.7 per cent to agriculture GVA.

Water bodies are an important source of inland fishery. Per the Census of Water Bodies by the Ministry of Jal Shakti (Census conducted during 2018-19 and reported in 2023), here are 2.4 million water bodies in the country, of which 97.1 per cent are in rural areas and 2.9 per cent in urban. The distribution of water bodies is as follows: 59.5 per cent are ponds; 15.7 per cent, tanks; 12.1 per cent, reservoirs; 9.3 per cent, water conservation schemes/percolation tanks/check dams; 0.9 per cent, lakes; 2.5 per cent, others.

Inland fisheries provide employment and livelihood support to over 28 million people in India, of which women are an integral part, helping with pre- and post-harvest work — peeling, seafood processing, community care, etc. An NCAER study observed that women’s concerns and interests are frequently disregarded.

For instance, women workers in the fish mandi of Srikakulam district of Andhra Pradesh complain about not having separate toilet facilities despite shouldering equal responsibilities in the entire marketing activities. There are still significant gaps in our understanding of gender relations in the fisheries sector.

Work overlooked

In India, women make up 72 per cent of the fisheries workforce (FAO, 2016), with 57 per cent engaged in seed collection, 73.6 per cent in marketing, and 75.7 per cent in curing and processing (CMFRI, 2010). Despite their significant contributions, women’s work is often overlooked. Processing industries often employ women, but rigid working hours, household responsibilities, and distance from the workplace make it difficult for them to attend work on time, leading to stress and even injuries.

The Central Institute for Women in Agriculture (CIWA) has calculated the Gender Work Participation Disparity Index in fisheries, which varies from State to State. In Nagaland, Manipur, and Himachal Pradesh it is < 0.15, whereas in Punjab, Haryana, Kerala, Uttar Pradesh, Bihar and Odisha, it is between 0.34 and 0.59 (CIWA, 2015).

Ownership of land and other productive resources is primarily male-dominated; in developed countries, women hold 20 per cent of land, and in underdeveloped countries, it is only 2 per cent. Due to several collateral factors or male dominance, women do not have access to financial facilities or marketing agreements. Women’s engagement in agriculture and related fields has been restricted by technological improvements that have primarily benefited men.

In 97 countries, just 5 per cent of agricultural extension services are received by female farmers, indicating that women’s access to these services is restricted. Women are left behind at home when males migrate elsewhere in search of employment, which results in excess workload and less prospects for income generation. In fisheries, women are under-represented on official decision-making platforms, which makes sustained reforms challenging. Sensitivity to gender issues, women-supportive marketing infrastructure, gender-responsive research, gender main-streaming of course curriculums, and gender-disaggregated data collection are crucial for sustainable transformation of the fishery sector.

The writers are Senior Fellow and Fellow, respectively, at NCAER

Odisha’s Breakout Moment is here!

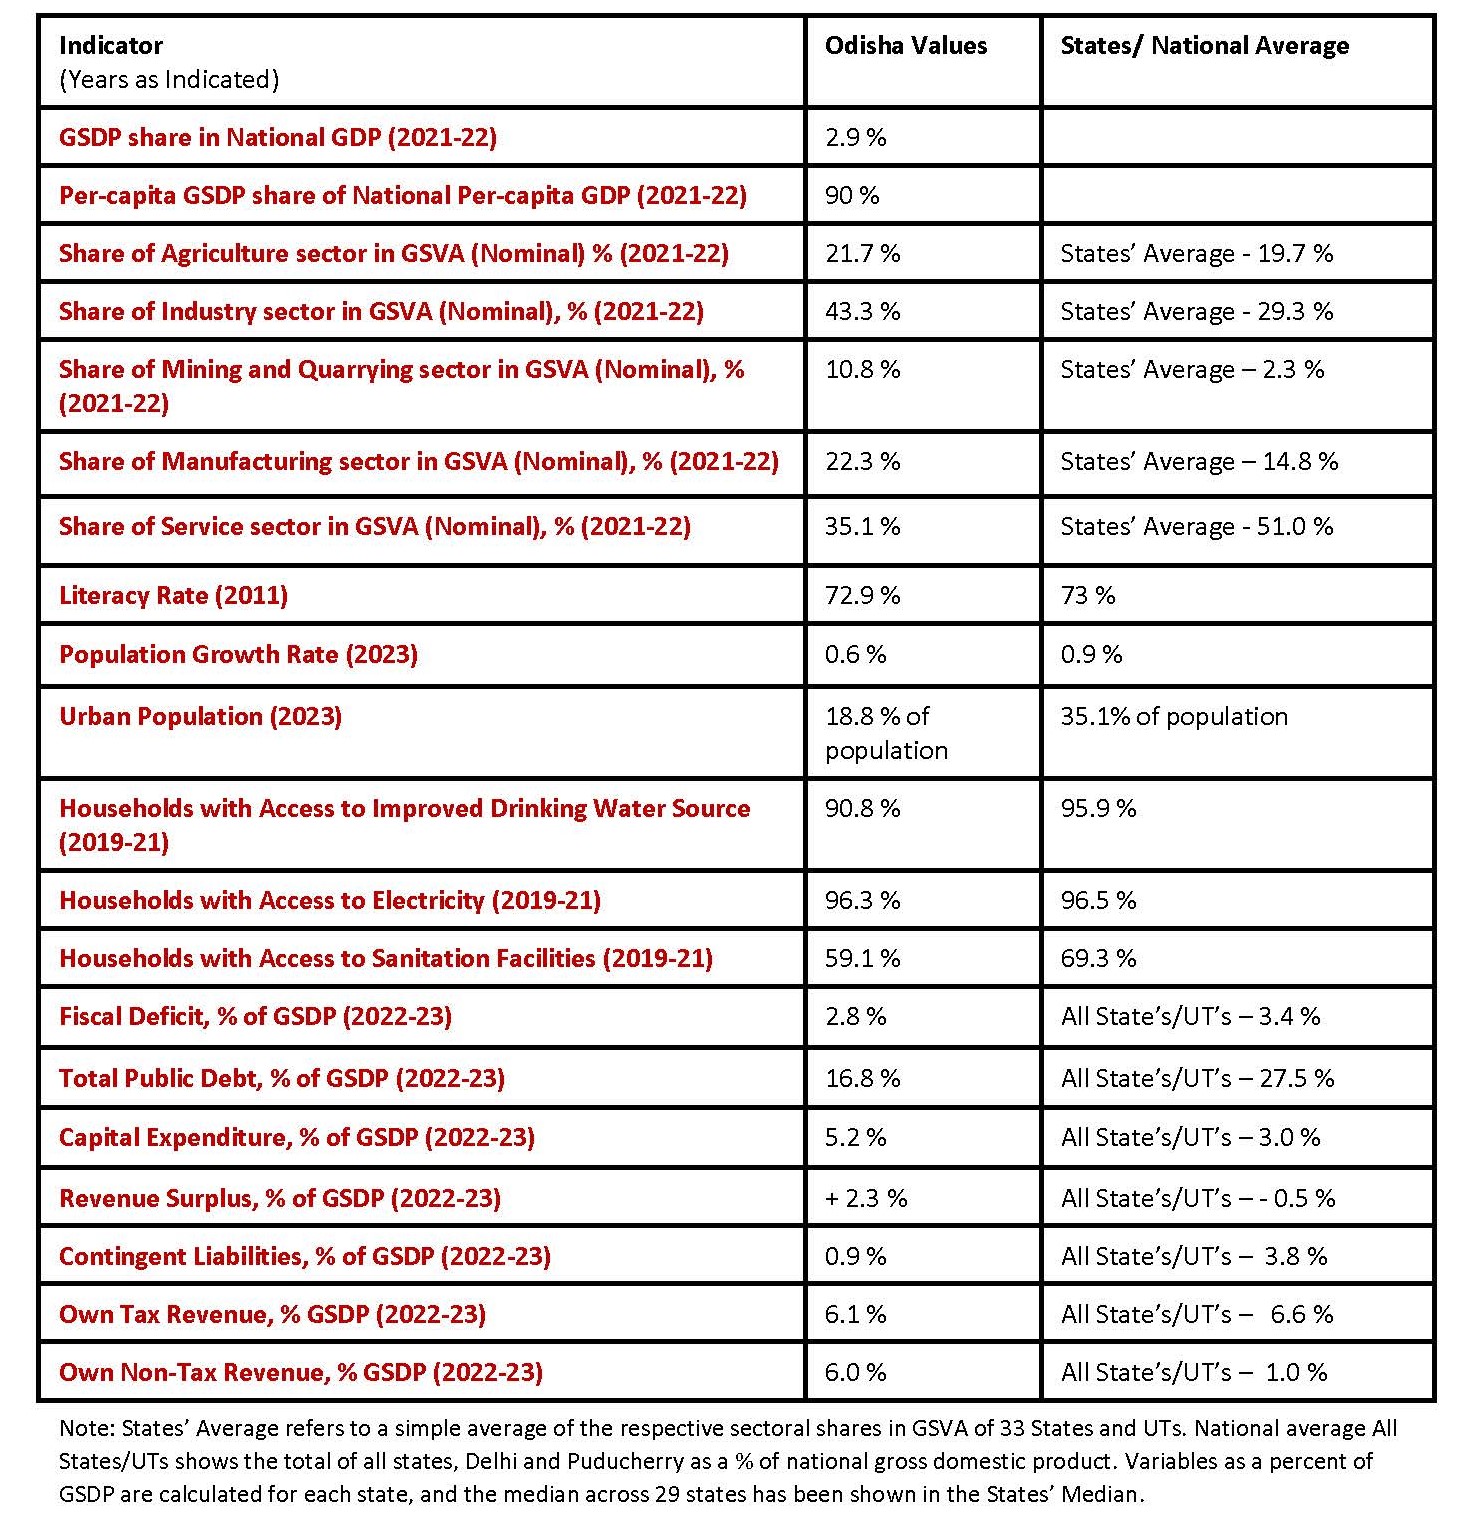
Odisha, India’s eleventh largest state by population and fourteenth largest by size of economy, has come a long way during the last two decades. At nearly $ 100 billion, if Odisha were a country, its economy would be larger than Tanzania, Sri Lanka or Ghana.

The growth momentum has been evident across sectors including   agriculture, manufacturing, and services. Additionally, at nearly 10 percent of its economy, and growing at 8 percent annually mining has contributed to Odisha’s economic well-being as well as to its robust public finances.  Thanks to the mining royalties, the state has a unique fiscal advantage. It collected non-tax revenue to the tune of 3.5 percent of its GDP a year compared to 1 percent for an average Indian state during the last decade.

The state’s rising prosperity has been accompanied by notable improvements in a variety of socio-economic markers such as gross enrollment ratio, gender parity index, infant mortality rate, fertility rate, life expectancy, immunization, and access to sanitation, drinking water and electricity.

Odisha has among the best fiscal yardsticks due to its deft fiscal management.

The state has been running a revenue surplus, unlike the revenue deficit for an average state; holds very few contingent liabilities; and runs fiscal deficit within the limits mandated under its fiscal rule. The state’s capital expenditure has doubled to nearly 5 percent of its GDP during the last decade, and far exceeds that of an average state.

Further, under most conceivable scenarios, its already small public debt is projected to decline further.

Yet, Odisha still lags on a host of indicators, including urbanization (its urbanization rate of 18 percent is only half that of the national average); enrollment ratio in higher education (which is only 22 percent compared to national average of 28 percent and much below that of the leading states such as Tamil Nadu’s 47 percent); and bank credit to GDP ratio (which at 29 percent is nearly half that of the national average).

Examples such as these indicate that despite lifting itself from the rank of a low-income economy to that of a low middle-income one, the state has miles to cover for it to become an advanced economy or to contribute to nation’s goal of becoming an advanced economy during the coming years.

So what may Odisha do to take a leap into the club of richer states such as Gujarat, Tamil Nadu and Karnataka, leaving behind the company of poorer states such as Rajasthan and West Bengal.

First and foremost, the state needs to elevate its aspirations. It should aim to attain double-digit growth rate and prepare its policy framework accordingly.

Second, a high middle-income economy with a per capita income of $4500, or a high-income economy with a per capita income of $12500, looks very different from today’s Odisha with a per capita income of about $2000.  Higher income economies are less dependent on agriculture and more on manufacturing and modern services; less rural and more urban; more digitally connected; more innovative; and more capital and skill- intensive. For Odisha to aspire to be an upper middle-income or a high-income economy, it ought to steer its growth strategy keeping these end goals in sight.

Doing so would require allocating public expenditure suitably on urbanization, skill formation, and R&D; simultaneous development of institutions and state capacity; and far greater domestic and international integration to attract capital, technology, and access to markets.

Third, its development strategy may emulate success stories in specific sectors from various other states and countries. For example, it can take cue from Kerala and Goa in international tourism (Odisha gets only 0.7 percent of the domestic and 0.4 percent of international tourism); Karnataka and Telangana in offering an alternative IT hub; and Tamil Nadu and Gujarat in manufacturing.

Unless Odisha pursues a more ambitious pathway, it may soon find the existing drivers of growth running out of steam. Early evidence points to such a possibility. Its GDP growth has decelerated to 6.6 percent during the last decade from 8.1 percent in the preceding decade. Worryingly, deceleration has been equally noticeable in manufacturing, mining, and services.

Odisha now has all the conditions to be the next breakout state, for which it should be very proud. What it needs now is to shift gears.

Key Statistics for Odisha and the National Averages

The writer is director general of National Council of Applied Economic Research. Views are personal.
    Get updates from NCAER