India Human Development Survey: February 2023

The IHDS Forum is a monthly update of publications, op-eds and data news based on the India Human Development Survey (IHDS), which was jointly conducted by NCAER and the University of Maryland in two rounds, in 2004-05 and 2011-12. The third round of the project has also been launched and is currently underway. Click here for previous issues.

Priorities for the G20 Finance Track

Emerging markets and developing economies are currently facing major challenges from global shocks including: a slowdown in global growth; food and energy price increases; decline in risk appetite of international investors; unsustainable debts in low-income countries; and ongoing climate risks. National policies have not sufficed to meet these challenges. Efforts at the national level must be complemented by changes in the global economic and financial architecture designed to make the world a safer place. In this paper, we focus on the financial aspects of such reforms. The financial agenda as we see it has seven key elements: (i) reform of central bank swap lines; (ii) reform of IMF contingent credit lines; (iii) SDR reallocation; (iv) reform of credit rating agencies; (v) creation of currency hedging instruments; (vi) inclusion of climate-resilient debt clauses in new debt instruments; and (vii) steps to streamline the debt restructuring process. We detail this agenda, and urge the G20 members to implement the recommended measures.

Summary of the Report

Tram scores over e-bus

Trams are more energy-efficient and economical.

After the push for carbon neutral transport system, all metros in India are now moving towards electric-bus. Recently, Mumbai introduced double-decker e-bus like the one that plies in London. The impression one gets is that this is the preferred mode for an urban transport system.

However, one finds it is the tram and not e-bus that is making a resounding comeback worldwide. Take the case of Europe. Trams have been reintroduced in 25 cities of France. In Germany, a proactive nation for carbon neutral transport, trams has been reintroduced in five cities. Trams continue to ply in many of the old East-European cities with narrow roads. And recently, e-bus was withdrawn from Moscow due to poor performance. Surely, there must be an economic rationale on why worldwide tram is being adopted as a dependable transport medium for cities.

At the outset, the outlay for trams seems huge — permanent tracks, overhead wires, etc. However, once installed, trams are one of the lowest energy consuming and most sustainable mass transit systems. This is the principal reason why worldwide tram is being introduced.

Trams run on hard wheels and rails that can be fully recycled, and have much lower rolling resistance than soft rubber tyres. They are plugged directly into the mains, negating the need for energy and resource-intensive batteries that need their own separate and often expensive charging infrastructure.

Energy consumption
The two important factors that drive energy consumption of trams and e-bus are rolling resistance and drive efficiency. How do tram and e-bus compare by these two yardsticks? Because the length of trams can vary, a single carriage, which is comparable with the weight of a double-decker bus, has been used in these calculations. A three-car tram can carry as many as 140 passengers (standing and seating), whereas the new electric London/Mumbai buses are expected to have a capacity of 90.

A single carriage tram has a coefficient of rolling resistance of approximately 0.001, around ten times lower than a double-decker e-bus tyre (0.01). A double-decker e-bus travelling at 30 mph along a smooth tarmac road would need 24.9 kW to keep it moving. By contrast, the tram would need only 3.5 kW. That is, more than seven times less power.

An electric motor converts the electricity supplied to it into motion with around 90 per cent efficiency. An e-bus has an electric motor, just like in a tram, and so benefits from the improved efficiencies. However, it also needs to carry its own energy supply in the form of a battery. In theory, a battery has minimal losses, however in practice charging with different currents can result in significant losses, up to 50 per cent in some cases.

On average, for the life of a battery, the charge and discharge cycles are estimated to be around 80 per cent efficient. That means, using a battery adds in losses of 20 per cent to our equation: 80 per cent x 90 per cent gives a drive efficiency of 72 per cent for an e-bus. A tram is plugged into the mains and avoids storage losses.

The tram beats e-bus hands down in two other important aspects as well. First, the life of an e-bus is 10-12 years and one needs to replace the battery after five years. The cost of the battery is nearly half the price of the e-bus. By contrast, the life of a tram is easily 20-30 years. In Kolkata, trams that are more than 50 years old are still running.

And, one needs at least twice/thrice the number of e-buses compared to an ordinary bus to provide similar service as charging of an e-bus takes 8-10 hours. Clearly, it is a costly venture. Given the financial condition of urban transport corporations in India, 3-4 years down the line, the corporations may collapse due to the financial burden caused by e-bus.

Thus, to provide an affordable carbon neutral urban transport system for at least the next few decades, investment in tram and not e-bus would make more economic sense.

The writer is Professor, NCAER. Views are personal

Mind the gender gap: Here’s how govt initiatives are focusing on empowering women in India

Bank account ownership took a leap over the last decade. But some of the gains stagnated during the pandemic. 2021 Global Findex data show that 78% of women reported having bank accounts. However, 64% did not withdraw any funds during the last 12 months, and 28% reported having an inactive account. Budget 2023 announced the launch of Mahila Samman Bachat Patra Yojana, a savings scheme for women.

One of the highlights at the ET Global Business Summit last week was how GoI, over the last eight years, has launched schemes that directly empower women. The flagship initiative that has direct implications for women’s access to social safety net has been the opening of bank accounts under the Pradhan Mantri Jan Dhan Yojana (PMJDY), allowing GoI to directly transfer cash into the beneficiaries’ bank accounts. The benefit of having a PMJDY account was most evident during the pandemic when GoI initiated cash transfers to women account-holders in the middle of the nationwide lockdown.

Data from the NCAER Delhi Coronavirus Telephone Survey conducted in June 2020, covering more than 3,400 households in Delhi-NCR, showed that female beneficiaries received the first instalment within three weeks of the declaration of lockdown. This shows the remarkable speed of delivery of cash benefits, facilitated through the Aadhaar-enabled payments system. Both below poverty line (BPL) and non-BPL households received the transfers, but some of the poorer households were excluded. These estimates are consistent with other studies using administrative data that suggest that less than half of poor households were likely to receive PMJDY transfers given the low prevalence of women PMJDY account-holders.

Bank account ownership took a leap over the last decade. But some of the gains stagnated during the pandemic. 2021 Global Findex data show that 78% of women reported having bank accounts. However, 64% did not withdraw any funds during the last 12 months, and 28% reported having an inactive account. Budget 2023 announced the launch of Mahila Samman Bachat Patra Yojana, a savings scheme for women. This has the potential to further boost women’s financial inclusion. But this is unlikely to have any effect on the poorest of the poor, especially those who remain unbanked.

Reasons can be linked to distance to the nearest bank, lack of documentation, financial illiteracy, keeping some financially excluded and being outside the purview of the social safety net. An effort needs to be made to further enhance last-mile delivery.

GoI had also launched schemes that have direct implications on women’s ‘time poverty’. Women traditionally play the role of water-bearers and firewood-collectors. Access to infrastructure, such as piped water and LPG, can significantly alleviate women’s time burden resulting from engagement in such activities. The National Sample Survey Office’s (NSSO) 2019 Time Use Survey indicated that 44% of rural households continued to collect firewood. Typically, women in households that use clean fuel, like LPG, spend less time in domestic unpaid chores, such as meal preparation time, freeing up women’s discretionary time.

Two key schemes deserve mention:

Pradhan Mantri Ujjwala Yojana (PMUY) has been providing free LPG connections since 2016, targeting women from BPL households, expanding LPG coverage across the country. However, response data from a Lok Sabha session indicate that in 2021-22, 58% of PMUY households took four or fewer refills, likely indicating that rural households continue to use solid fuel for cooking.

GoI’s initiative of extending subsidised LPG under PMUY since May 2022 is likely to increase LPG usage, although the post-subsidy LPG price could still be too high for sustained adoption. The consumer price index (CPI) inflation for fuel and light has been hitting double digits since May 2021, with only four months in between reporting less than10% fuel inflation. Also, NCAER research shows that it is women’s paid work that provides households incentives to adopt time-saving infrastructures such as LPG.

Jal Jeevan Mission aims to provide piped water connection to all rural households by 2024. While not exclusively targeted towards women, water security has the potential to significantly improve women’s well- being by freeing up women’s time to pursue productive work.

But where are the jobs? Data from the 2020-21 Periodic Labour Force Survey (PLFS) suggest a rise in work participation for rural women between 2019-20 and 2020-21. But much of it is in the form of distress employment in subsistence agricultural activities, in the form of self- employment and unpaid helpers. Plans for digital push in the agriculture sector, along with providing supply-side incentives for rural startups, as laid out in the budget, has the potential to convert this into an opportunity for women farmers.

But this will first require bridging the gender digital divide. Measures that directly empower women with skills training to exploit recent opportunities or provide sustainable income-generating avenues are likely to also reap greater gender dividends. According to GSMA’s (Global System for Mobile Communications) Mobile Gender Gap Report 2022, women’s mobile internet use increased from 21% to 30% between 2020 and 2021, while increasing from 42% to 45% for men, showing significant strides in bridging the digital divide.

GoI has made significant strides in empowering women. But the depth of the challenge makes this a work in progress.

The writer is senior fellow, National Council of Applied Economic Research (NCAER)

A remedy for health insurance

Ayushman Bharat: These schemes have a good coverage. But funds use will suffer, if people are unaware of entitlements

The introduction of social health insurance has been one of the most significant innovations of the past decade. While public health spending (including both Centre and States) has seen only a marginal increase over the last decade, government spending on social health insurance has increased consistently. Spending on social health insurance (at current prices) has almost doubled between 2013-14 and 2018-19.

Meanwhile, the government in September 2018 revamped the existing Rashtriya Swasthya Bima Yojana (RSBY) and introduced the Pradhan Mantri Jan Arogya Yojana (PMJAY) or Ayushman Bharat scheme with an aim to expand the services to a larger number of households. The annual coverage also increased to 5 lakh per household as opposed to 30,000 in RSBY. A surprising aspect of the Budget 2022-23 was that Ayushman Bharat did not receive a single mention in the speech.

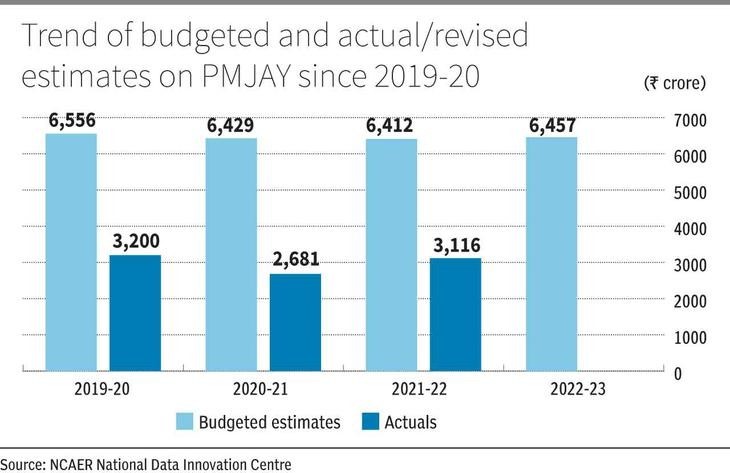
According to the estimated demand and expenditure for PMJAY by the 15th Finance Commission on Ayushman Bharat (2019), the total costs (Centre and States) of PMJAY could range from ₹28,000 crore to ₹74,000 crore for the next five years. However, we did not see an expenditure of this order for PMJAY since its inception. In fact, actual spending was much lower than the budgeted estimates over the last three Budget periods (Figure 1).

Expanded coverage
There can be no denying that coverage has expanded vastly, although meeting the initial target to cover 10.74 crore families (or nearly 55 crore individuals) from the lowest socioeconomic strata may take some time. However, access to PMJAY cards is not the same as using them. The utilisation of the amount allocated to the scheme has been poor. While 83 per cent of the Budget allocation was utilised in 2018-19, the utilisation decreased to 50 per cent in 2019-20, and to 42 per cent in 2020-21. With the pandemic raging in these two years, this decline is surprising and implies gaps in the implementation of the scheme.

While it can be argued that the use of funds for social insurance can be unutilised if the claims are less, it is also a fact that lack of awareness has played a major role here. NCAER research brings out lack of awareness on the part of the beneficiaries about the health benefits for which they are eligible and the process of accessing them. In 2019, National Data Innovation Centre at NCAER examined the knowledge and perceptions of health insurance beneficiaries regarding their entitlements from the schemes.

We assessed the knowledge of benefits and entitlements of various social health insurance schemes among the households in the Delhi NCR region who had access to a health insurance scheme over one year, 2019-20. We found that a significant proportion of the beneficiary households lack useful knowledge of their entitlements. Moreover, some of those who reported having knowledge turned out to have incorrect knowledge. We also examined the knowledge of beneficiaries about the entitlements and benefits of a popular health insurance scheme from Rajasthan. Before it got merged with PMJAY, Bhamashah Swasthya Bima Yojana (BSBY), the flagship health insurance programme of the Government of Rajasthan, used to provide an annual health cover of ₹30,000 for general illnesses and up to ₹3 lakh for critical illnesses. Besides hospitalisation coverage, the scheme also covered outpatient expenses for seven days before and 15 days post-hospitalisation. But when asked if members of the beneficiary households were aware that BSBY scheme covered outpatient expenses for the pre- and post-hospitalisation periods, 14 per cent of them reported that they were not aware of the same.

Among the remaining 86 per cent of the beneficiary households, 48 per cent reported that BSBY didn’t cover any pre- and post-hospitalisation expenses — which was not correct.

Awareness deficit
Similarly, a third of the beneficiary households did not know that BSBY pays for pregnancy and delivery-related expenses. This incorrect knowledge often leads to lower utilisation of the defined benefits of such schemes. Less than one-third of the individuals with insurance in the Delhi NCR region actually claimed their benefits in the event of hospitalisation.

If we expect to achieve universal access to healthcare through the provision of health insurance schemes, it is important to enhance knowledge about the scheme’s benefits and entitlements among the beneficiaries. Increasing coverage alone is not sufficient to achieve the goal. Without devising proper strategies to inform the card holders about where to go and what to claim, the vision of achieving comprehensive health will remain unattended. At this rate, each Budget may only see only a reduction in outlays due to lack of utilisation.

The writer is a Fellow at the NCAER. Views expressed are personal

    Get updates from NCAER