Bridging the skill gap in India’s automobile industry

Economic growth depends on innovation and technological progress — a fact highlighted by the 2025 Nobel Prize in Economics which highlighted the role of human capital in driving productivity. In India, this linkage is most visible in the automobile industry, a pillar of manufacturing and employment. Yet, the sector faces widening skill shortages and skill gaps that threaten its global competitiveness.

The automobile industry contributes nearly 49% of India’s manufacturing GDP and employs millions. However, the sector struggles to find workers with the right technical and soft skills. As India shifts towards electric vehicles (EVs), hybrid and flex-fuel systems, and smarter factories powered by automation, AI, and robotics, the demand for skilled engineers and technicians is growing faster than the supply. A recent NCAER National Skill Gap Study (2025) confirmed that both supply- and demand-side mismatches are holding the sector back.

Supply-side challenges in automobile industry

The supply-side problem begins with training. Many candidates lack practical knowledge of working with advanced machinery and digital systems. For most, the first experience of “working with their hands” comes on the factory floor. This lack of exposure leads to high attrition rates.

Soft-skill deficiencies add to the challenge. Poor communication, low discipline, and limited teamwork skills make new recruits less effective. Courses on battery technology, mechatronics, automation, and robotics remain scarce, while there is a shortage of qualified trainers. Even geography plays a role — firms often struggle to find a local skilled workforce willing to relocate.

Large automotive firms fill this gap through on-the-job training, covering technical and interpersonal skills. Some partner with ITIs to co-design curricula, set up labs, or share trainers. These partnerships help but fall short of meeting the industry’s vast needs. Smaller component makers and service workshops hire unskilled labour, training them internally or multi-skilling workers to cut costs.

Demand-side barriers: Image and inclusion

Automobile industry leaders acknowledge a perception problem. Shop-floor jobs are viewed as low-paying and physically demanding. Graduates trained in automotive trades often prefer better-paying delivery jobs in cities. Meanwhile, high-end engineering talent gravitates to the IT sector, attracted by salaries and cleaner work environments.

Gender imbalance compounds the issue. The automobile industry is overwhelmingly male-dominated, with women making up just 3.4% of the workforce (PLFS 2023-24). Only 1.8% of women are in vehicle manufacturing and 1% in repair and maintenance. Some EV assembly units have pioneered all-female lines, but these are exceptions. Workplaces lack basic facilities and gender-sensitive norms, deterring women from joining or staying in the industry.

Addressing skill gap for the future

Closing the skill gap requires simultaneous action on both the supply and demand sides. Curricula at ITIs and engineering colleges must evolve in line with emerging technologies — from EV design to cybersecurity and data analytics in mobility. Industry-linked training should become the rule, not the exception.

Equally, the automobile industry must make its jobs aspirational. Many young people are unaware that leading automakers offer career paths where technicians can rise to managerial roles through upskilling and reskilling. Awareness campaigns and visible success stories can reset these perceptions.

To attract niche talent — in software, AI, and systems engineering — companies will need to offer competitive pay and better working conditions. At the same time, automation that reduces physical strain and strict enforcement of POSH (Prevention of Sexual Harassment) guidelines can encourage more women to participate.

No single stakeholder can solve the skill crisis. Industry-academia partnerships, especially at the local level, are essential. Firms must continue co-creating courses and offering apprenticeships, while governments can incentivise regional skill mapping to align labour supply with demand.

Regular industry surveys should track evolving job roles and required competencies in real time. This will help design responsive policies for the next generation of manufacturing jobs. A coordinated skilling ecosystem — combining private innovation, public policy, and institutional accountability — is India’s best bet to sustain growth in its most dynamic manufacturing sector.

Isha Dayal is Fellow and Bornali Bhandari is Professor at National Council of Applied Economic Research (NCAER). Views expressed are personal.
Skill Shortages and Gaps in the Motor Vehicles Sector: Case for a Labour Market Information System in India

The automotive sector contributes significantly to India’s manufacturing output and employment (Bhandari, Pratap and Sahu 2022). Among those employed, most are skilled individuals, having undergone formal or non-formal vocational/technical education and training, according to the Periodic Labour Force Survey (PLFS). Despite this, skill shortages and skill gaps abound, as found through stakeholder consultations for NCAER’s National Skill Gap Study for High Growth Sectors (Bhandari et al. 2025). There are in-demand automotive jobs for which people are difficult to find, across geographies (resulting in overall, as well as spatial skill shortages); and if people are available, they lack the necessary skillsets (resulting in skill gaps) (Green 2013).

India is unprepared for its demographic shift — elderly outnumbering children

Beneath the surface of this demographic story lies a quieter, more human crisis.

India is getting older and faster than most realise. More than 10 percent of our population—over 14 crore people—are already aged 60 years or above. By 2050, this number will double, and for the first time in history, the elderly will outnumber children below 15.

According to the United Nations Population Fund’s India Ageing Report 2023, India’s elderly population by 2046 is expected to surpass its child population.

The report also highlights a worrying 41 percent decadal growth rate among the elderly. Yet, our policies, institutions, and even mindset remain unprepared for this profound demographic shift.

The erosion of family-based care

India’s traditional family structure, once the bedrock of elder care, is eroding. Urbanisation, migration, and the rise of nuclear families have drastically altered how we live and with whom we live. In the past, elders could rely on their children and extended families for physical, emotional, and financial support. Today, that safety net is fraying.

The reasons are structural, not just cultural. Younger generations are moving to cities for education and work. Women, traditionally the primary caregivers, are increasingly participating in the workforce, which is a sign of progress but also a challenge for household caregiving.

The silent crisis at home

Beneath the surface of this demographic story lies a quieter, more human crisis. Increasingly, India’s elderly population is living alone or with only another senior partner.

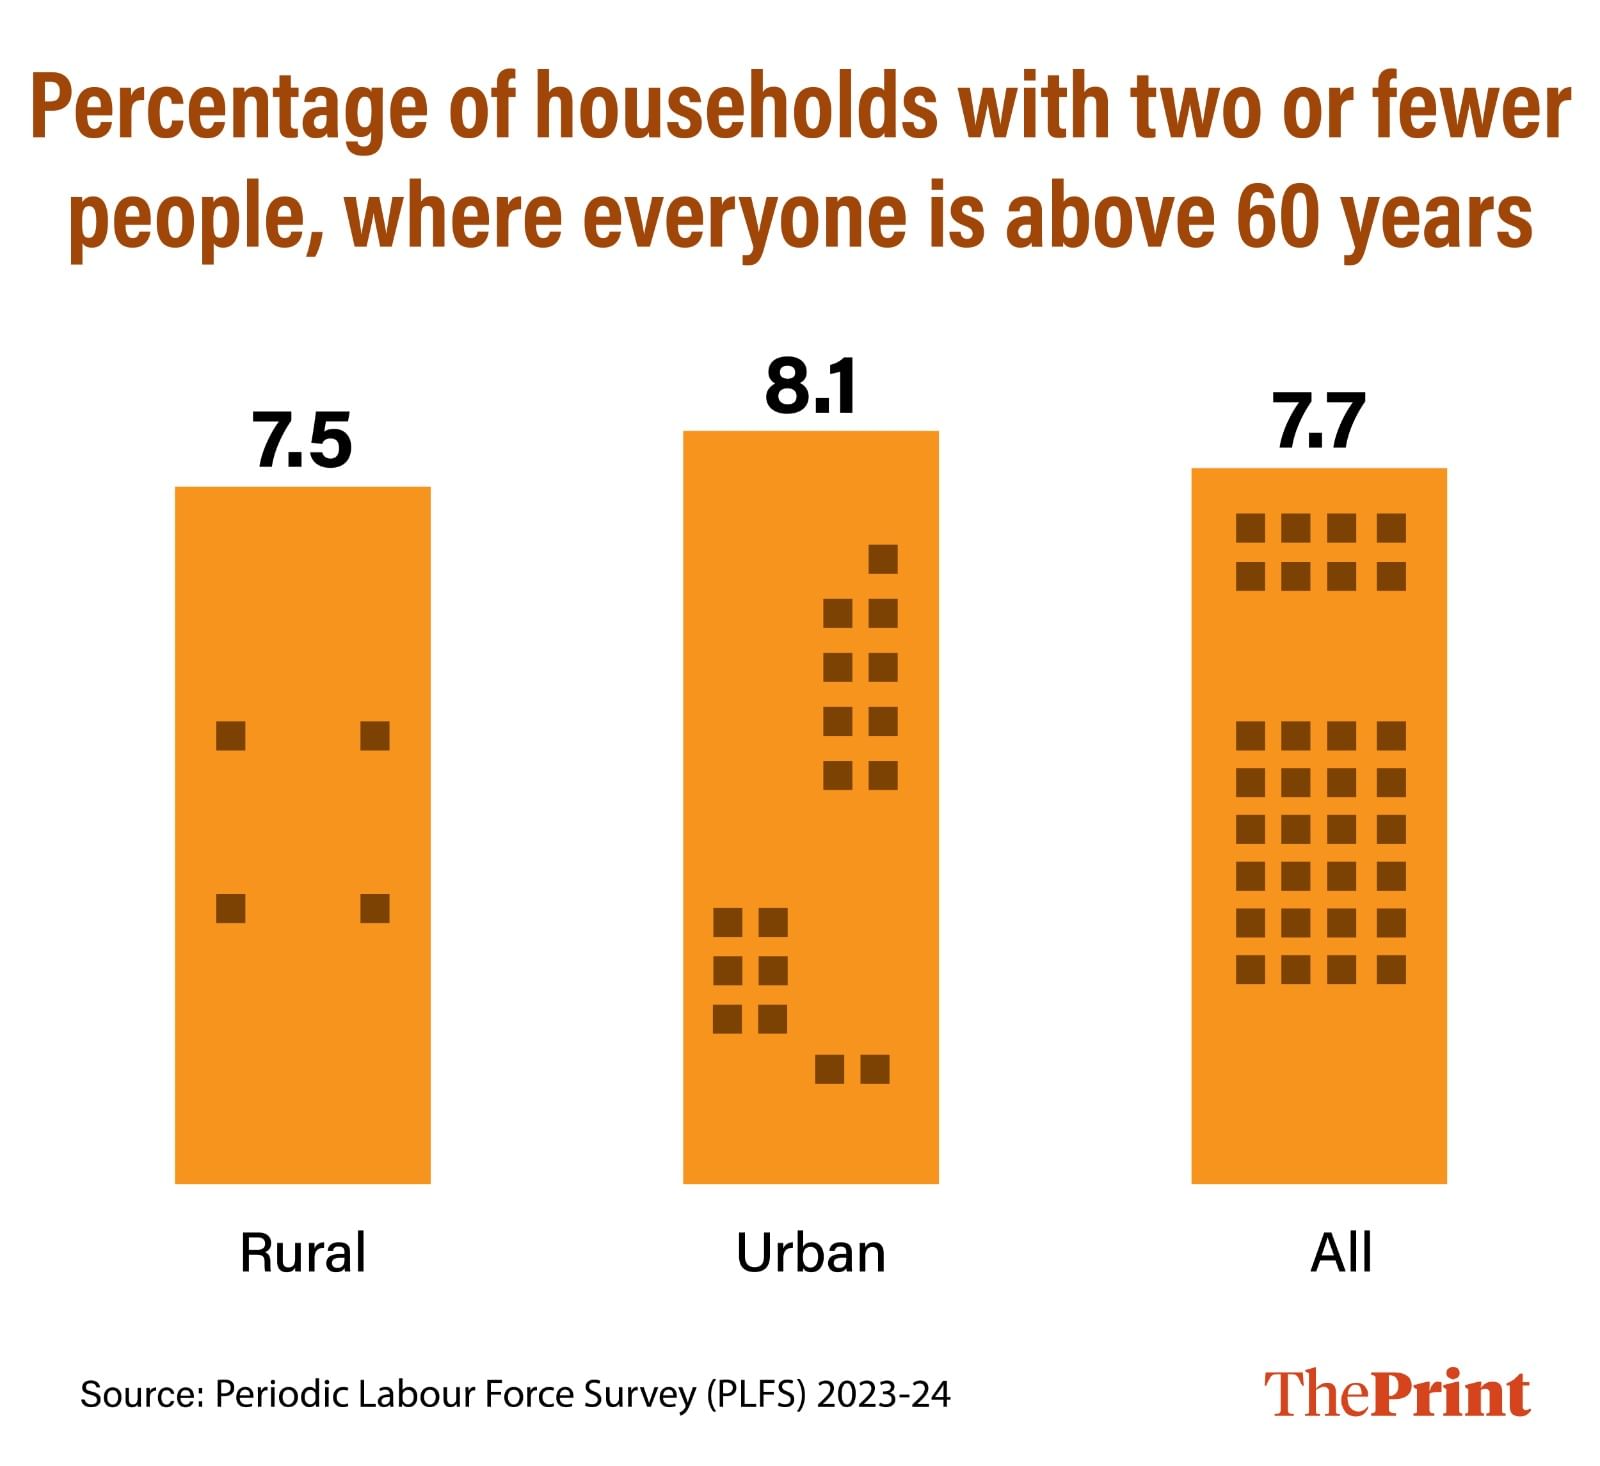
As per Periodic Labour force Survey (PLFS) 2023-24, across the country, 7.7 percent of households consist solely of elderly members aged above 60 years, with a maximum household size of two. The share is slightly higher in urban India (8.1 per cent) compared to rural India (7.5 per cent), reflecting changing family structures and the gradual erosion of traditional support systems.

Graphic by Manali Ghosh | ThePrint 

With no younger family members around to assist, these elderly individuals must rely on each other despite their own physical and emotional limitations. Such households often remain hidden from public view, yet they represent one of the most vulnerable segments of our society.

The situation is particularly concerning in southern states such as Andhra Pradesh (16.3 per cent), Tamil Nadu (15.3 per cent), and Kerala (15.4 per cent), where the share of elderly-only households is alarmingly high.

In these one- or two-member households, frailty, illness, and loneliness often go hand in hand. Many older adults grapple with mobility issues and chronic illnesses such as diabetes or hypertension, alongside deteriorating eyesight and hearing. When both partners are aged and unwell, even simple daily activities—like visiting the market, cooking meals, or seeing a doctor—can become overwhelming tasks.

The absence of younger family members or community networks further deepens their isolation. Without regular check-ins, social engagement, or reliable systems of care, many elderly individuals are left to fend for themselves. In smaller towns and rural areas, where access to public transport and healthcare services is limited, these difficulties intensify, leaving the elderly particularly exposed and unsupported. These are not isolated stories of individual hardship—they reflect a growing demographic reality that demands urgent social, policy, and community attention.

Building a care economy

What India urgently needs is the development of a care economy—an organised ecosystem that recognises caregiving as both essential social infrastructure and a viable economic sector. This means investing in training, certification, and employment opportunities for professional caregivers such as home nurses, physiotherapists, geriatric aides, and social workers.

A robust care economy would also formalise and value the immense unpaid care work—mostly done by women—that currently goes unrecognised. The International Labour Organization (ILO) estimates that unpaid care work contributes significantly to GDP, yet remains invisible in economic accounting. By formalising these roles, India could not only improve the quality of life for its elderly population but also open millions of new job opportunities. This would require coordinated efforts between government, private sector, and civil society—ranging from vocational training programmes to financial incentives for caregiving enterprises.

A moral and economic imperative

Caring for the elderly is not merely a social welfare issue; it is both a moral obligation and an economic necessity. On the moral front, a society’s measure lies in how it treats its most vulnerable members.

The elderly, who once built and sustained our families and communities, deserve dignity, comfort, and security in their later years. Economically, investing in care infrastructure can generate substantial returns. It can create formal employment, and improve productivity by relieving the burden of unpaid care work on working-age women.

Moreover, the growing elderly population represents a significant segment of consumers with distinct needs—healthcare, assistive devices, leisure, financial services. A vibrant care economy would not only serve humanitarian goals but also stimulate demand and innovation across sectors.

Rethinking policy priorities

India’s public health and social policies must evolve to reflect this new demographic reality. The focus must shift from reactive hospital-based treatment to proactive community-based care. Integrating elder care into the primary health system, creating local “care hubs,” and leveraging technology for remote monitoring and tele-consultation can go a long way.

We also need financial and policy support for caregivers. Tax incentives, social security coverage, and recognition under labour laws can make caregiving a respected and sustainable profession. The government’s “National Policy on Senior Citizens” and schemes like the Integrated Programme for Older Persons are steps in the right direction but need scaling up and modernisation.

Towards an inclusive future

India stands at a crossroads. The choices we make today will determine whether our ageing population becomes a demographic burden or a social and economic opportunity. An inclusive care system can transform the ageing challenge into a development advantage.

As India moves toward becoming an aging society, it must build institutions that reflect compassion as much as efficiency. Caring for our elderly is not an act of benevolence—it is the foundation of a humane and equitable society.

If we build a strong care economy now, we will not only secure dignity for today’s elders but also ensure comfort and security for ourselves in the years to come. Because ageing, after all, is not someone else’s story—it is the most universal future we all share.

Palash Baruah and Sameeha Jameel are Fellow and Research Analyst at National Council of Applied Economic Research (NCAER), New Delhi. Views are personal.

Why nations now pay more – and give up more – to secure financing

The sovereignty premium has become the quiet tax of our time. 


At the 2025 International Monetary Fund-World Bank annual meetings, discussions on financing development goals highlight an increasingly pressing reality: the growing economic cost countries incur to achieve financial autonomy. This sovereignty premium is becoming visible across sovereign balance sheets.

Global public debt is expected to surpass 100% of gross domestic product by 2029, the highest level since 1948 – but this masks the real cost: collateralised revenues, yield sacrifices and balance sheet erosion, not just higher spreads. Understanding how the premium is extracted, who bears the cost and what this means for the international financial system matters. The premium buys time, not escape.

The new reality is that sovereigns are using every part of their balance sheet to secure liquidity. The difference now lies not in whether they pay, but in how they pay and in what form. The mechanics of this premium differ between fragile and advanced economies, but the logic is converging in striking ways.

Figure 1. Three emerging patterns

Type of sovereign Primary motive Instruments used Who bears the cost
Fragile / foreign exchange-dependent Maintain market access and external liquidity Collateralised borrowing, commodity-linked loans and securitised revenues Domestic banks, pension funds and taxpayers
Liquid / Advanced Preserve balance-sheet strength and sanction resilience Reserve reallocation (gold, FX swaps), asset sales, fiscal guarantees Central banks, future taxpayers through foregone income
Common outcome Converging use of balance sheets to buy time, not autonomy — The premium is paid across the system in different currencies, proportional to the loss

External borrowing and revenue securitisation

The first channel is via external borrowing under tightening collateral constraints. Countries are increasingly issuing new debt not to finance investment but to manage redemption pressure. In February 2024, Kenya raised $1.5bn at 9.75% to repurchase part of a $2bn Eurobond. Investors demanded stronger covenants and margin triggers, effectively turning sovereign borrowing into quasi-secured lending. Autonomy itself became the collateral. Comparable practices – collateralised oil pre-payments, escrowed export receipts and margin-call clauses – are now common across several African and frontier economies.

The second channel is revenue securitisation and asset monetisation. Governments are borrowing against future income or selling public assets – such as ports, utilities or commodity flows – to raise near-term cash. These transactions provide liquidity today but mortgage fiscal capacity tomorrow. Once pledged, those flows are lost to future budgets. Liquidity comes at the price of ownership.

The third is through reserve composition and the yield sacrifice. The geopolitics of sanctions have altered how reserves are held. Central banks are substituting interest-bearing securities for gold and other non-yielding assets to insulate against seizure risk. Poland announced plans to raise its gold allocation from 20% to 30% of reserves. The World Gold Council’s 2025 survey reveals that 95% of central banks anticipate further accumulation, the highest ever recorded. Such ‘insurance’ reduces reserve income, constrains monetary policy and strengthens fiscal dominance. It is a silent cost embedded in prudence.

Domestic financial repression and restructuring

Domestic financial repression and restructuring is the fourth channel. When external options close, governments turn inward – lengthening maturities, freezing coupons or forcing domestic investors to absorb losses. Ghana’s 2023 Domestic Debt Exchange, Egypt’s accelerated state-asset sales and Argentina’s repeated conversions of central bank paper all show how the burden migrates home. The IMF’s latest Global Financial Stability report confirms that overreliance on narrow domestic investor bases – particularly when driven by financial repression – compounds rather than resolving the premium.

Each of these channels deepens rather than relieves fragility. Higher rollover costs accelerate debt accumulation, lower-yield reserves weaken central bank transmission and domestic expropriation erodes confidence. A country rolling over $20bn annually and paying 100 basis points more forfeits $200m every year – resources that could be diverted to infrastructure or climate adaptation. The IMF’s analysis confirms that decades of accommodative conditions have ended: interest rates have risen sharply while debt has continued to accumulate, fundamentally altering fiscal sustainability dynamics. The arithmetic of seeking financial autonomy has become subtractive.

How technology plays a role

Technology is compounding the premium, as finance grows more segmented, digital and sanction-sensitive. Over 130 jurisdictions are exploring or piloting central bank digital currencies. They promise efficiency yet introduce surveillance, convertibility and cyber-resilience risks. The premium now includes technology risk, layered on top of credit and policy risk. Sovereignty has become a securitised, technology-embedded good.

The distribution of the cost is politically uneven. Those who design or negotiate the transactions seldom bear their consequences. Pensioners, taxpayers and future generations do. When regimes change contractual rules – through restructuring or coercive exchanges – investor expectations shift, and term premia rise. The pursuit of control compounds the loss of it.

Globally, these premiums reveal a deeper systemic fracture. As advanced economies weaponise sanctions and payment networks, developing countries diversify reserves into defensive assets. But diversification without yield erodes income and credibility. The system is fragmenting into defensive balance sheets rather than co-operative ones. Everyone is hoarding safety; few are creating liquidity. The result is insurance without assurance.

Three directions could temper the premium

First, regional reserve pooling can reduce the need to hoard costly, idle assets. Shared high-quality collateral would mutualise sanction risk and preserve yield. Yet political obstacles are formidable: countries fear losing control, and coordination among diverse economies remains elusive. The Chiang Mai Initiative’s limited activation during crises illustrates these constraints.

Second, with proper preconditions in place, deeper local-currency bond markets can replace serial foreign borrowing. Credible yield curves, disciplined primary dealers and transparent buybacks would help rebuild trust. However, this requires credible institutional development, macroeconomic stability and investor confidence that many countries lack. Thin markets will remain vulnerable to sudden stops and capital flight.

Third, cross-border payments systems must be sanction-resilient but anchored in liquid, interest-bearing assets, not static reserves. Building such infrastructure requires a multilateral consensus, precisely when geopolitical fragmentation intensifies. Competing payment architectures – from Project mBridge to bilateral arrangements – may deepen rather than heal fragmentation.

These measures would not eliminate the sovereignty premium, but they could turn it from a penalty into a policy choice. Yet without genuine political commitment and institutional reform, they risk remaining aspirational.

The sovereignty premium has become the quiet tax of our time – a cost imposed not merely by markets but by the design of global finance itself. Each time a state sells an asset to buy time, swaps yield for safety or restructures to preserve liquidity, it pays that tax. What began as a spread on a bond has become a spread across the sovereign balance sheet. The 2025 annual meetings have made clear that incremental adjustments will not suffice. Until new institutions and norms emerge, sovereigns will continue to pay in basis points and in ownership and discover that what the premium buys is not sovereignty, but postponement.

Udaibir Das is a Visiting Professor at the National Council of Applied Economic Research, Senior Non-Resident Adviser at the Bank of England, Senior Adviser of the International Forum for Sovereign Wealth Funds, and Distinguished Fellow at the Observer Research Foundation America.

Building Water Accounts: Physical Supply and Use Tables for India’s Water Resources

This paper presents a comprehensive analysis of India’s water resources through the construction and application of Physical Supply and Use Tables (PSUT), providing a systematic framework for understanding sectoral water allocation, consumption patterns, and policy implications. Using the System of Environmental-Economic Accounting (SEEA) methodology, we examine water flows across agricultural, industrial, energy, and municipal sectors, revealing critical insights into India’s water security challenges. Expectedly, our analysis shows that agriculture dominates water consumption at 859 billion cubic metres (BCM) (81% of total abstraction), with rice alone accounting for 341 BCM, followed by wheat (106 BCM) and sugarcane (70 BCM). The industrial sector consumes 20 BCM, with engineering and pulp-and-paper industries being the largest users, while the energy sector requires 12 BCM, predominantly for coal-based electricity generation. We find that surface water provides 690 BCM and groundwater contributes 239 BCM to total abstraction of 1,122 BCM. The return flows amount to 1,053 BCM, indicating substantial potential for wastewater treatment and reuse expansion. The paper demonstrates how water accounting frameworks can inform evidence-based policy formulation, particularly for demand management, pricing reforms, and intersectoral water reallocation. The research contributes to the growing literature on environmental-economic accounting by providing the first comprehensive PSUT analysis for India’s water sector, offering a replicable methodology for other developing economies facing similar water stress challenges.

    Get updates from NCAER