Bridging the digital chasm

Growth in digital adoption has outpaced growth in digital literacy, creating an ecosystem where access does not necessarily translate into empowered usage.

India’s dream of becoming a developed nation by 2047 is closely tied to the potential of its digital economy. From fintech innovations to digital governance, its transformation is being powered by technology. Flagship initiatives such as Digital India, the Jan Dhan-Aadhaar-Mobile (JAM) trinity, and the Unified Payments Interface (UPI) have expanded digital access in ways once unimaginable.

But as the country surges ahead, a critical question arises—who is being left behind?The digital payments ecosystem in India has seen a meteoric rise. In 2024 alone, UPI processed about 172 billion transactions, up 46% from 117.64 billion in 2023, with a single-month transaction value peaking at Rs 23.25 lakh crore (National Payments Corporation of India). This is a testament to both infrastructure expansion and behavioural change, with more people turning to digital platforms for everyday transactions.

Encouragingly, a Reserve Bank of India (RBI) report notes that nearly a third of digital payment users now come from rural India, and merchant adoption is rising in smaller towns and villages. However, growth in digital adoption has outpaced growth in digital literacy, creating an ecosystem where access does not necessarily translate into safe or empowered usage—especially for informal workers, rural populations, and women.

The informal sector, which contributes around 45% to India’s GDP (National Accounts Statistics 2022-23) and employs the vast majority of the workforce, need to be carried along the digital revolution. According to the Periodic Labour Force Survey (2023–24), 61% of non-agricultural female workers are employed in informal enterprises and they often lack access to stable digital infrastructure, basic digital tools, and, most importantly, the required financial literacy to use such tools. When placed in the context of India’s dismally low financial literacy rate—just 24% according to the National Centre for Financial Education (NCFE)—their inclusion becomes a structural necessity to equitable growth.

Despite government schemes like e-Shram and PM-SVANidhi aimed at digitising the informal workforce, most workers remain at the periphery of digital participation. A 2023 study by ICRIER revealed that while 69% of micro and small enterprises used digital wallets, less than half had access to digital credit or e-commerce platforms. The primary barriers were not just economic but psychological and institutional: lack of trust in technology, limited awareness, and fear of fraud.In Jaipur, a Centre for Effective Action study of small merchants found that 58% had still not adopted digital payments despite low entry barriers.

For many, the preference for cash was not due to inertia but perceived convenience, concerns about transaction failures, and a lack of institutional support to resolve problems. The findings challenge the assumption that mere digital access equals digital inclusion. Without the skills, confidence, and safeguards to use digital tools meaningfully, digital platforms can disempower as easily as they can empower.

Financial literacy, therefore, emerges as the missing link. According to NCFE, only 27% of Indian men are financially literate. For women, the figure falls to 21%, and among informal and rural workers it is likely even lower. This knowledge gap leaves users vulnerable to rising cyber fraud and predatory digital lending. The Central Payment Fraud Information Registry reported 13.42 lakh UPI-related fraud cases in FY24 involving `1,087 crore—an 85% increase in cases and a nearly 90% jump in the amount defrauded compared to FY23. Victims are often low-income earners with limited understanding of online security or consumer rights.

The proliferation of unregulated digital lending platforms poses another threat. These platforms, often operating outside the purview of financial regulators, target financially uneducated users with exploitative interest rates. Without financial awareness, technology becomes a double-edged sword.

Financially illiterate users also miss out on wealth-building opportunities that digital finance can unlock—from savings and insurance to pensions and investments. As the digital economy opens up sophisticated tools for the middle class and tech-savvy youth, informal workers remain confined to low-yield, cash-based assets, deepening the wealth gap. What emerges is a multi-layered digital inequality: a lack of tools, trust, and knowledge.

India needs a multi-dimensional policy approach to address this. Financial literacy needs to be treated as core infrastructure—at par with roads, electricity, and broadband. Targeted vernacular campaigns need to reach women, youth, and informal workers through community-based platforms. Self-help groups, anganwadi workers, and panchayats can serve as grassroots educators. Schools and vocational institutions should embed financial education into curricula. Digital infrastructure can be made more inclusive through affordable smartphones and applications that work in low-bandwidth settings.

Fintech regulation should be tightened with faster grievance redress and stricter enforcement of RBI guidelines to protect users. Behavioural nudges can also play a role. Linking government benefits to digital literacy milestones, offering micro-insurance for active users, and gamified saving tools can encourage responsible financial behaviour. These aren’t just good practices—they are essential if India wants to avoid replicating old inequalities in new, digital forms.

The road to Viksit Bharat runs through its informal sector. As we imagine a future driven by innovation, we may remember that true empowerment comes not from access alone, but from the ability to use that access with confidence and clarity.

CS Mohapatra & Depannita Ghosh, Respectively Investor Education and Protection Fund (IEPF) chair professor and research analyst, IEPF Chair Unit, at the National Council of Applied Economic Research. Views are personal.
Do debt swaps deliver on development finance?

Evidence from borrowing countries reveals systematic twin-objective failure

While financial institutions promote debt swaps as ‘win-win’ solutions that address both debt distress and development financing, borrowing countries report a systematic failure in achieving both objectives, revealing an inversion of development finance principles.

Experiences across various developing countries highlight this critical contradiction. While Belize’s Prime Minister hailed their swap as providing vital ‘breathing space’, Ecuador faced intense pushback, with over 260 activists and academics cautioning against ‘green vulture funds’ exploiting vulnerable economies. This divergence exposes how debt swaps attempt to solve two fundamentally different problems – debt sustainability and development financing – through a single mechanism that systematically underperforms in addressing either objective effectively.

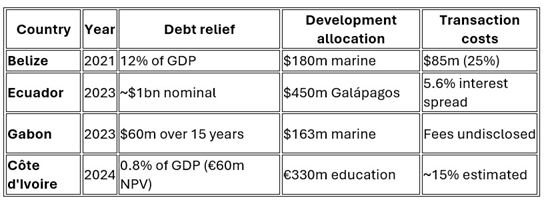
Figure 1. Systematic dual-objective failure across developing countries

Debt swaps in Belize, Ecuador, Gabon, Côte d’Ivoire, 2021-24

Sources: World Bank/TNC; LSE analysis; Ecuador Ministry of Finance; Bond prospectus analysis; Bank of America/DFC; Fee structure confidential; World Bank press release; Industry analysis

Across documented swaps totalling $3.5bn, the average debt relief measures 0.8% of gross domestic product. No swap has achieved a meaningful improvement in debt sustainability, while development resources remain systematically inadequate to meet sectoral needs.

Scale constraints

The 2024 IMF-World Bank framework explicitly recognises debt swaps as optimal primarily for countries facing moderate distress and temporary liquidity pressures rather than comprehensive restructuring needs. Côte d’Ivoire’s successful education swap hinged on demonstrating sound debt management practices, reducing its deficit to 4% of GDP from 6.8%. Countries lacking similar institutional strength systematically face exclusion.

Even successful cases illustrate constrained outcomes on both objectives. Côte d’Ivoire’s swap targeted €400m of expensive debt, freeing €330m over five years – merely 0.8% of GDP. This modest debt relief offers minimal structural improvement to debt sustainability, while the €60m net present value savings barely address substantial education infrastructure needs. Gabon’s $500m blue bond yields only $60m in net savings over 15 years – insufficient for either meaningful debt relief or conservation impact.

Transaction costs and sovereignty constraints undermine objectives

Ecuador’s swap illustrates hidden cost structures, with the government paying 11.04% interest compared to bond issuance at 5.4%, creating a 5.6 percentage point spread benefitting intermediaries rather than conservation.

Gabon’s experience confirms this pattern. Industry analysis suggests costs approached 15-20% of nominal debt relief. These transaction costs absorbed nearly 25% of Belize’s debt relief while diverting resources from conservation spending to financial intermediaries.

Borrowing countries report systematic sovereignty constraints through offshore control mechanisms. Ecuador’s former Environment Minister Daniel Ortega characterises swaps as replacing debt cancellation with ‘new loans with severe conditions’, involving external oversight, rigid performance targets and decades-long commitments constraining future policy choices.

Current swap structures systematically impede parliamentary oversight. Research reveals it remains ‘impossible for the public, or parliament, to scrutinise these deals before they are finalised’. Ecuador’s Galápagos Life Fund operates from Delaware, while Gabon’s conservation fund utilises similar offshore structures managed by private entities rather than government systems. The World Bank acknowledges that such structures can ‘prioritise external agendas over local development needs’.

The African Development Bank’s response reflects growing institutional scepticism, emphasising ‘African-led solutions’ while criticising ‘opaque natural resource-backed loans’, signalling regional resistance to externally designed swap structures.

Institutional capacity requirements create systematic bias

Small island developing states face institutional barriers that expose systematic prerequisites for swap participation. Seychelles officials acknowledge that administering swap proceeds ‘requires dedication and enthusiasm of a full-time team, with appropriate experience and training’.

Belize’s success depended on The Nature Conservancy’s 30-year presence in the country. Côte d’Ivoire succeeded through existing World Bank frameworks. Such prerequisites ensure that swap mechanisms serve middle-income countries with temporary gaps rather than addressing acute development finance needs.

Creditor coordination failures limit effectiveness

Private creditors hold 43% of debt in distressed countries but rarely participate in debt swaps, despite their substantial exposure. Successful swaps require voluntary participation from diverse creditor types. However, coordination failures systematically undermine the effectiveness of swaps. The Debt Service Suspension Initiative demonstrated these constraints indicating that simple, coordinated mechanisms deliver faster results than complex swap negotiations. Despite G20 encouragement, only one private creditor participated in a $12.9bn debt service suspension.

Creditor composition has shifted dramatically, with Paris Club debt falling to 11% from 28% for DSSI-eligible countries, while non-Paris Club lenders increased to 18% from 18%. For debt swaps, this fragmentation means negotiating with creditors operating under distinct legal frameworks with conflicting incentives, making comprehensive participation increasingly difficult.

Historical precedents expose systematic constraints

Contemporary swaps fail compared to historical single-purpose mechanisms. The Brady Plan achieved a 35% debt reduction through focused restructuring without conditionalities on development. The DSSI suspended $12.9bn across 48 countries within months through straightforward coordination.

Contemporary swaps achieve 2-3% debt reduction while generating inadequate development resources – inferior performance on both objectives compared to specialised instruments. The European Network on Debt and Development analysis suggests comprehensive debt moratoriums could free $50.4bn over two years, substantially exceeding realistic swap scenarios.

The 2024 framework inadvertently exposes twin-objective limitations. For debt sustainability, swaps are most suitable for countries with moderate distress and strong institutions, precisely those that require minimal debt relief. For development financing, swaps generate resources too constrained to address acute development needs.

Policy implications

Countries facing genuine debt distress require comprehensive restructuring focused on restoring solvency rather than managing marginal liabilities with conditional development.

G20 Common Framework implementation offers appropriate mechanisms for structural insolvency, providing the scale of principal reduction that swap mechanisms cannot deliver. Special Drawing Rights allocations address immediate fiscal pressures without transaction costs and sovereignty constraints.

Development financing requirements demand direct, unconditional mechanisms. Regional development banks possess the sectoral expertise and country relationships necessary for effective delivery of development finance.

Where swap deployment remains appropriate, strict criteria must govern implementation. Middle-income countries with moderate distress, strong institutions and existing sectoral capacity represent circumstances where swaps might complement debt management strategies. Transparent cost-benefit analysis requiring public disclosure addresses sovereignty erosion.

Debt swaps represent expensive financial engineering that systematically fails both debt sustainability and development finance objectives. Policy frameworks should abandon hybrid mechanisms in favour of specialised instruments designed for single purposes – comprehensive restructuring for debt problems, direct financing for development needs. Only through acknowledging these distinct requirements and deploying appropriately specialised instruments can policy effectively serve either debt relief or development finance objectives rather than pursuing financial complexity that achieves neither.

Udaibir Das is a Visiting Professor at the National Council of Applied Economic Research, Senior Non-Resident Adviser at the Bank of England, Senior Adviser of the International Forum for Sovereign Wealth Funds, and Distinguished Fellow at the Observer Research Foundation America.

Coercive bilateralism: New world order defined by how trade deals are made

For India, the challenge is to strike a balance between tactical necessity and economic priorities.

On April 2, United States President Donald Trump announced a broad set of bilateral tariffs that stunned the world. The tariffs were high and uneven: India faced a 26 per cent tariff; China, 34 per cent; and the European Union, 20 per cent. Soon after, they were suspended for 90 days, with a blunt message: Unless the US’ trading partners agreed to “fair and reciprocal” trade deals during the pause until July 9 (now extended to August 1), the punitive tariffs would take effect. The announcement marked a hard pivot away from the rules-based trade architecture of the World Trade Organization (WTO) and its insistence on non-discrimination, placing many economies under pressure. Several countries began negotiating bilateral trade deals with the US — from advanced economies like the United Kingdom (UK) to export-dependent partners like Vietnam. Others, including India, are compelled to do the same, lest they face exclusion from one of the largest consumer markets. This moment marks a deeper shift in the global trade order. For decades, the US advocated multilateralism, spearheading the General Agreement on Tariffs and Trade (GATT) and the WTO. It pushed for tariff reductions, rule-setting, and dispute settlement mechanisms aimed at making trade fair, transparent, and predictable. But in recent years, that vision has eroded. Throughout the 1990s, the US gradually shifted from multilateralism to bilateral trade agreements. Mr Trump’s first term was defined by unilateral tariffs and trade wars. The US systematically blocked appointments to the WTO’s appellate body, leading to its paralysis by 2019. Domestic political-economy concerns about inequality, geopolitical fragmentation, and post-pandemic supply chain anxieties have further discredited the global trade system. The “July 9 ultimatum” crystallises this evolution. The US is no longer trying to fix multilateralism, it is bypassing it entirely.

What we are witnessing is the rise of “coercive bilateralism.” The US is using its market access as a blunt instrument: “Either lower your tariffs, or we will raise ours to match.” For developing economies, this presents a dilemma: Either concede on sensitive sectors or face a tariff shock that could destabilise exports and investment inflows.

This approach has seen some success for the US: On July 2, Mr Trump announced a deal with Vietnam that slashed the proposed 46 per cent tariff on Vietnamese goods to 20 per cent (while trans-shipped goods, especially from China, would face a 40 per cent levy). In return, Vietnam would offer zero-tariff access to US goods, including large-engine cars, though the details remain unclear. For Mr Trump, this was a political win and a message to others: A deal is possible but only on Washington’s terms.

India, meanwhile, continues to negotiate under pressure. American and Indian officials are scrambling to resolve key differences, particularly over dairy and agricultural imports. India is reportedly resisting broad concessions in these politically sensitive sectors, even as the threat of steep new tariffs looms. While Mr Trump has expressed optimism about a deal with New Delhi, many sticking points remain. With nearly 18.3 per cent of Indian exports headed to the US, the stakes are high. A targeted agreement may be necessary to shield key industries from abrupt hikes.

The European Union, too, has sought a middle ground. While it is prepared to accept a universal 10 per cent tariff on most exports covering over €380 billion in trade — Brussels is pushing for exemptions in sectors like pharmaceuticals, semiconductors, aircraft, and alcohol. The UK had earlier agreed to a 10 per cent tariff on cars in exchange for improved access for its beef and aircraft engine sectors. Even China has negotiated a limited truce, restoring some rare earth exports to the US, though core disputes remain unresolved.

The consequences of coercive bilateralism are profound. First, multilateralism is unravelling. The WTO, once the anchor of the global trading system, is being sidelined. Second, power asymmetry is growing. Smaller economies are now forced to negotiate individually with a superpower, weakening their leverage. Third, the consistency of global trade rules is breaking down. Countries are being pulled into a web of inconsistent standards, digital provisions, and tariff exceptions, threatening the predictability that businesses depend on.

For India, the challenge is to strike a balance between tactical necessity and economic priorities. It is conceivable that changes sought by the US may work to India’s benefit by forcing tariff reforms that domestic politics have long delayed. But concessions — especially on sectors like agriculture or data governance — must be weighed against their long-term economic, political and national-security implications. Beyond the bilateral equation, India must also think multilaterally: Revitalising regional trade pacts, expanding South-South cooperation, and contributing to WTO reform.

While Mr Trump’s deadline has shifted again, the precedent his approach sets could define global trade for a generation. The danger is not just in the content of the agreements being signed but in how they are being signed: Under duress and at speed. This shift from multilateral rule-making to coercive deal-making forces the world to confront a basic question: Will we normalise a power-based trade order, or recommit to rebuilding a fair, rules-based system?

The authors are associated, respectively, with the Johns Hopkins University, Washington DC, and NCAER, New Delhi. The views are personal.

Dynamics of Energy Consumption, Economic Growth and Carbon Emission in a Sub-national Economy Context of India: An Evidence from Kerala

On examining the relationship of energy consumption with economic growth and carbon emission, we provide the evidence that the petroleum consumption growth significantly contributes to GSDP growth of Kerala (as indicated from regression coefficient of 0.70%), whereas electricity consumption growth affects GSDP growth with a time lag (as evidenced from Granger causality and regression coefficient of .13%). In contrast, GSDP growth of the state drives up both electricity and petroleum consumption demand, along with an observed strong elasticity of substitution relationship between consumption of two energy components (coefficients varying from 30% to 66%). We further find that the growth of transportation sector activities measured from transportation output which significantly contributes to gross emissions (as reflected from regression coefficient of .32%) rather than the overall GSDP growth of the state, suggesting that the demand for petroleum product increases with increased income growth without regard for its environmental concerns over the long-run. This is occurring more especially when amounts of CO2 emission are very much lesser in the state as compared to the national average of all the states in India.

Beyond clicks and scrolls: Digital financial education for Viksit Bharat

Financial literacy should not be an occasional campaign or an app feature-it must be an ongoing, evolving journey. In this age of digital transformation, the proliferation of apps, online courses, and gamified learning tools has brought financial education to our fingertips. But the question remains: are we truly learning, or merely consuming content in a digital haze?

Traditionally, financial education in India was sporadic and limited—confined to formal schooling or isolated workshops. However, the economic shocks of the global financial crisis and, more recently, the Covid-19 pandemic revealed a glaring need: widespread, scalable financial literacy for every Indian, regardless of age or income. This urgency accelerated the move toward digital financial education. Digital tools now play a crucial role in disseminating financial knowledge. Online courses, mobile applications, and gamified learning experiences provide users with flexible, self-paced education. Platforms such as Coursera and edX offer courses from top universities, while mobile apps like Mint and YNAB (You Need a Budget) help individuals manage their personal finances interactively. These resources have broadened access to financial education, reaching audiences that traditional methods often failed to engage. Indian institutions followed suit—Sebi launched its investor education app Saa₹thi, while the RBI’s Financial Literacy Week focused on themes like digital banking and cyber safety.

Digital tools undeniably have improved outreach. They break socio-economic and geographical barriers, enabling underserved communities to access financial knowledge. The variety of formats—videos, podcasts, quizzes, simulations—caters to different learning styles. Many mobile apps now integrate behavioural nudges and progress tracking to keep users engaged. This represents a significant shift from the one-size-fits-all model of traditional financial education to a more focused, target-oriented learning style.

Yet this democratization of financial information comes with caveats. The sheer volume of online information risks overwhelming users. People often skim through content without internalizing or applying it. The spread of misinformation—especially through social media influencers, biased advisers, or non-verified blogs—compounds the problem. Add to this the digital divide: rural populations, elderly citizens, and economically disadvantaged groups either lack reliable internet access or digital confidence.

The financial education materials available online require re-orientation with an emphasis on the targeted groups’ needs. Generic modules often fail to consider individual financial circumstances—something only personalized guidance or human intervention can address. As behavioural economists point out, cognitive biases like procrastination, overconfidence, and loss aversion can limit the impact of even the best online tools if not designed with user behaviour in mind.

Importantly, digital literacy without adequate awareness of fraud prevention and grievance redress mechanisms can lead to devastating outcomes. While India has witnessed an exponential rise in UPI and digital payment adoption—with around 172 billion transactions in 2024, marking a 46% increase from 117.64 billion in 2023—this surge has also been accompanied by an alarming rise in scams, phishing attacks, and payment frauds. Victims often lack knowledge about where and how to report such incidents or even recognize that they’ve been defrauded. Without a robust understanding of safe digital practices and redress pathways—like the RBI’s Digital Ombudsman or the Cyber Crime Portal—users remain largely vulnerable and under-confident, especially in semi-urban and rural areas where digital trust is still forming.

Despite several initiatives already in place, India still struggles with translating the availability of digital financial literacy into active public engagement. Regulators and academic institutions like SEBI, NCFE, and NISM have developed accessible e-learning platforms and certification programs—such as the Saa₹thi app, NCFE’s targeted modules, and NISM’s Investor Awareness Web Modules. These offer structured, credible, and even gamified financial education, covering topics like mutual funds, stock markets, savings, and fraud prevention. Yet, awareness of these resources remains alarmingly low. Even among digitally literate individuals, the uptake is limited—either due to lack of trust, interest, or simply the overwhelming nature of financial jargon. For large sections of the population, especially in semi-urban and rural areas, these platforms remain out of reach due to digital exclusion, language barriers, or lack of localized relevance. The gap between resource availability and user participation reveals that creating content is not enough; we must also create demand, trust, and usability, apart from access.

Several countries offer strong examples of how digital financial literacy can be structured, integrated, and sustained. In the United Kingdom, the government-backed Money and Pensions Service (MaPS), along with its MoneyHelper platform, provides a centralized digital hub offering free and impartial financial guidance. It brings together budgeting tools, scam awareness content, and debt advice in one place, while also collaborating with schools to incorporate financial capability into curriculum-based learning. The result is a comprehensive, life-stage approach to financial literacy, supported by both digital access and offline reinforcement.

Similarly, Australia has developed an inclusive model through the Moneysmart platform, operated by the Australian Securities and Investments Commission (ASIC). This portal offers financial education tailored to specific age groups and life stages—from schoolchildren to retirees. Its resources include interactive calculators, goal-based planners, and fraud alert systems—all designed in simple, accessible language. The emphasis is on clarity, safety, and user engagement, with financial decision-making contextualized through real-life scenarios.

India can draw valuable lessons from these global models. A unified, government-backed platform—consolidating digital learning resources, grievance redressal portals, helplines, and verified financial tools—can serve as a trusted source amid the current flood of unregulated content. Embedding financial education within formal schooling and higher education, especially using regional languages and culturally relevant examples, can build early awareness and long-term habits. It is equally important that the content reflects real-time risks—updating users on evolving scams, digital payment innovations, and policy shifts. Finally, encouraging deeper collaboration between fintech firms, educators, and regulators can ensure that digital platforms are not just technologically advanced, but also behaviourally intelligent—equipped with built-in nudges, fraud warnings, and default safety mechanisms.

To make digital financial education truly effective, we need to move from passive consumption to active engagement. Hybrid models—blending digital tools with in-person mentorship, community coaching, or AI-driven personalization—can bridge this gap. Schools, colleges, fintech firms, and regulators must co-create programs that combine real-world simulations with culturally relevant case studies and feedback mechanisms.

Financial literacy should not be an occasional campaign or an app feature—it must be an ongoing, evolving journey. Digital tools are powerful, but only when paired with critical thinking, trust in verified knowledge, and the ability to act on it. If we want citizens to make informed economic decisions, we must ensure that our approach to promoting financial education is not just limited to making it accessible, but also authentic, actionable, and inclusive—with grievance redress and fraud awareness forming its core. For broad-based financial sector participation, we need to move beyond clicks and scrolls, develop true understanding and nuances of financial markets, and help in building a sound and meaningful digital economy. As India envisions a Viksit Bharat—a developed and self-reliant nation by 2047—financial empowerment through digitalized financial education is central to that goal.

C S Mohapatra, former IES Officer and currently IEPF Chair Professor and Depannita Ghosh, Research Analyst, NCAER. Views are personal.

    Get updates from NCAER