Safeguarding India’s Growth: FX Risk Management for Macrofinancial Stability

India’s rapid economic ascent has positioned it as the world’s fifth-largest economy, with the International Monetary Fund (IMF) projecting it will reach third place by 2027. The Indian government’s ambitious goal of achieving developed-country status by 2047 requires an annual nominal GDP growth of around 10% in USD terms over the next 25 years—exceeding the 7% average of the past decade.

Sustaining this accelerated growth necessitates substantial financing, sometimes externally sourced. Economic history offers cautionary tales: Russia in the early 2000s, Brazil in the 2010s, and China in the 2020s faced macro financial shocks that disrupted their growth trajectories. Such shocks are especially destabilizing when they stem from financing-related vulnerabilities, restricting access to the essential capital required to sustain long-term growth.

India’s external sector appears robust, underpinned by rising foreign exchange reserves and a low external debt-to-GDP ratio—key indicators of macroeconomic stability. However, a closer examination of firm-level data reveals an emerging vulnerability: small and medium-sized enterprises (SMEs) are increasingly accumulating unhedged foreign exchange (FX) exposures. The risks are also found to be especially amplified for financially distressed firms and state-owned enterprises (SOEs). While this risk remains contained at present, its continued expansion could amplify financial fragilities, heightening systemic risk over time and undermining India’s long-term growth trajectory

SMEs: A Growing Source of FX Risk

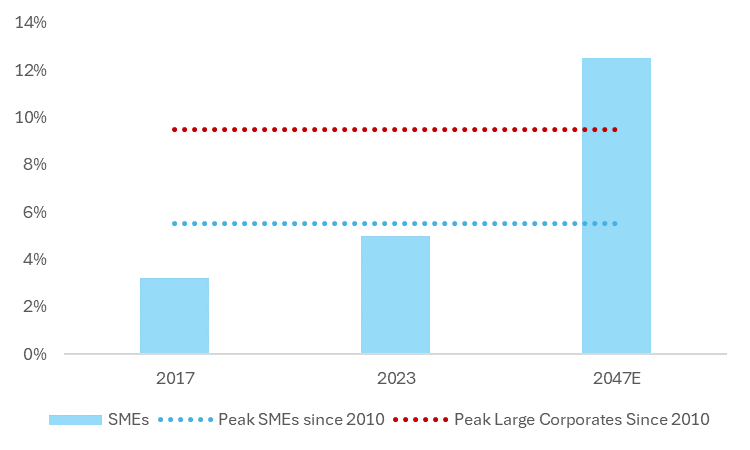
SMEs—defined as firms with assets up to USD 750 million—are integral to India’s expanding economic base, contributing significantly to employment, exports, and supply chain resilience. Despite the presence of a well-developed banking and non-banking financial system, SMEs are increasingly turning to external commercial borrowings (ECBs) to meet their funding needs. Their share of ECBs in total borrowings has surged by 50% over the past six years, reaching 5%. While this level remains manageable today, projections indicate that ECBs could account for 12% of SME borrowings by 2047—a historically high and potentially systemic level.

This shift toward external financing is driven by both push and pull factors. On the push side, domestic credit constraints, particularly for SMEs with limited collateral or weak credit histories, have made access to affordable long-term financing more challenging. India’s banking sector, while relatively stable, remains cautious in lending to SMEs due to concerns over asset quality, higher default risks, and stringent regulatory capital requirements. Additionally, India’s non-banking financial companies (NBFCs), which traditionally played a key role in SME financing, have faced liquidity constraints following periodic stress episodes in the sector.

On the pull side, global financial conditions and market-driven incentives have made ECBs more attractive. Historically low interest rates in international markets over the past decade, coupled with improved sovereign credit ratings and India’s growing integration into global financial markets, have enabled even mid-sized firms to tap offshore borrowing at competitive rates. Furthermore, the flexibility of ECBs—offering longer tenures, reduced documentation requirements, and, in some cases, more favorable repayment structures—has made them an appealing alternative to domestic bank loans. The liberalization of India’s external borrowing framework, including relaxed end-use restrictions and increased access to foreign lenders, has further facilitated this trend.

While external borrowing provides SMEs with a critical avenue to scale operations and invest in growth, the increasing reliance on unhedged foreign debt introduces significant currency and refinancing risks. As global interest rates are starting to normalize and currency volatility is on the rise, the cost of servicing FX liabilities could rise sharply, posing a broader challenge to macro financial stability if left unaddressed

Chart 1: External Commercial Borrowings as a Percentage of Total Long-Term Borrowings
Source: Prowess, Bloomberg, Author Calculations

As highlighted earlier, a significant portion of these foreign borrowings remains both unsecured and unhedged, amplifying SMEs’ exposure to currency risk. As of 2023, only 38% of SME FX exposure was hedged, compared to 68% for large corporates—a stark disparity that underscores the urgent need for targeted risk management interventions. This growing vulnerability is particularly concerning as SMEs are currently trading at elevated valuation levels, which could mask underlying financial fragilities.

The current trend bears striking similarities to vulnerabilities observed during the Asian Financial Crisis, particularly in South Korea and Thailand, where currency depreciation, rollover risk, and duration mismatches among SMEs led to severe financial instability. In the run-up to the crisis, many Korean SMEs had accumulated large amounts of short-term foreign currency debt, assuming continued exchange rate stability. However, when the Korean won depreciated by nearly 50 percent, firms with unhedged USD and JPY exposures saw their debt burdens soar, triggering widespread defaults. Compounding the issue, many of these firms faced rollover risk, as creditors became unwilling to extend financing, leading to a liquidity crunch that deepened the crisis.

Thailand faced a similar trajectory, where inadequate FX hedging and excessive reliance on short-term foreign debt led to massive corporate distress when the baht collapsed in 1997. A critical issue in both Korea and Thailand was the lack of granular, real-time data on corporate FX exposures, making it difficult for regulators to assess vulnerabilities before they escalated.

A similar data gap persists in India today. While aggregate indicators—such as foreign exchange reserves and external debt-to-GDP ratios—suggest resilience, firm-level FX risk exposure remains opaque, particularly for SMEs. Without better disclosure requirements and enhanced regulatory oversight, Indian policymakers risk underestimating the potential fragilities building up in the SME sector.

Addressing these challenges requires stronger FX risk monitoring frameworks, stress testing for rollover risks, and incentives for SMEs to adopt prudent hedging strategies. Without proactive intervention, India’s rising SME FX exposures could amplify systemic risks in future episodes of external volatility, much like the Korean and Thai experiences during the 1990s.

Chart 2: Proportion of Corporates Hedging FX Exposure
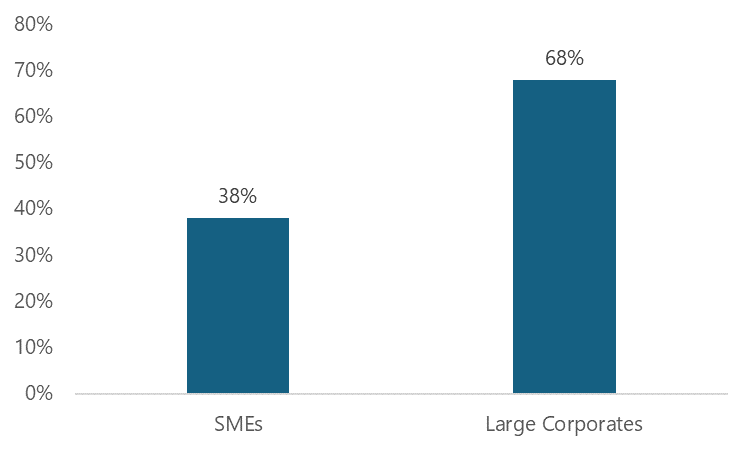
Source: Prowess, Author Calculations

SOEs and Financially Distressed Firms: Amplification of Risk

Our preliminary analysis, presented in this co-authored blog, offers early insights from our forthcoming research paper, which examines patterns of unsecured foreign borrowing in India’s corporate sector. The findings highlight trends that warrant closer scrutiny, particularly concerning financial vulnerabilities among highly leveraged firms.

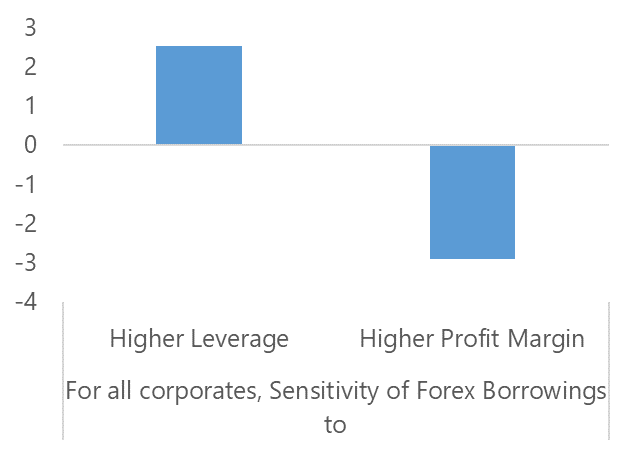
We find that unsecured foreign borrowing is disproportionately concentrated among firms already under financial distress—those with higher leverage and weaker profitability. This trend is especially pronounced among state-owned enterprises (SOEs), which exhibit greater sensitivity to leverage shocks compared to private firms. The tendency of SOEs to engage in riskier borrowing practices may stem from weaker financial discipline, implicit expectations of sovereign backing, or preferential access to credit that is not always aligned with market fundamentals.

Brazil’s experience in the 2010s offers a cautionary lesson. During this period, many Brazilian SOEs became heavily reliant on unsecured foreign borrowings, assuming continued currency stability. However, when the Brazilian real depreciated sharply, these entities suffered significant losses, triggering broader financial distress. The inability to roll over foreign debt, coupled with rising interest costs, forced large-scale interventions to stabilize key sectors. India must learn from such examples and implement stronger risk management frameworks to prevent similar vulnerabilities from emerging within its SOE sector and financially weaker firms.

This underscores the urgent need for improved oversight of corporate FX exposures, stress testing for highly leveraged entities, and proactive hedging strategies, particularly for firms with systemic relevance. Strengthening regulatory frameworks and corporate governance practices will be crucial to ensuring that India’s external financing strategy does not become a source of macroeconomic instability.

Chart 3: Sensitivity of FX Borrowings to Key Fundamental Factors
Source: Prowess, Author Calculations.
Note: The analysis captures the sensitivity of foreign borrowings relative to total borrowings, leverage levels, and market-based profitability projections.

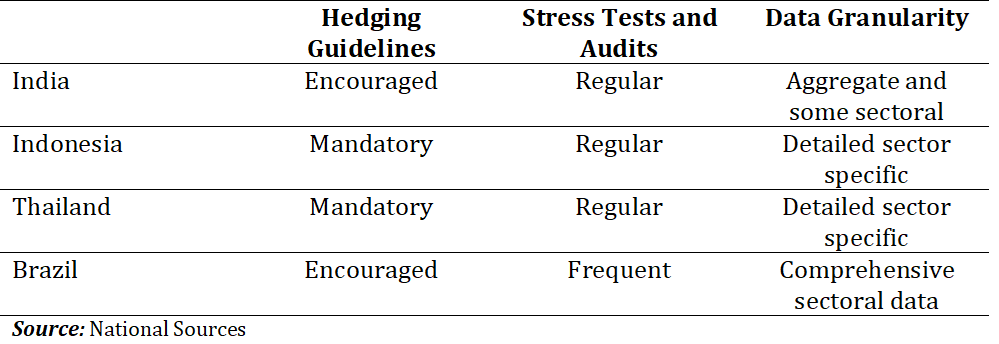
Chart 4: India vs. Emerging Market Peers on FX Exposure
Stakeholder Roles and Key Considerations

Strengthening FX Risk Management: Lessons from Global Experiences

India’s increasing exposure to foreign exchange risk, particularly within its SME sector, mirrors patterns observed in other emerging markets. Historically, rapid financial integration and external borrowing liberalization have introduced structural vulnerabilities when accompanied by inadequate risk management frameworks. Well-documented cases from Brazil, Indonesia, and Thailand illustrate the consequences of unchecked FX risk accumulation and the policy responses that mitigated systemic spillovers. Studies such as Eichengreen et al. (2005) on currency mismatches and emerging market crises and Goldstein and Turner (2004) on balance sheet vulnerabilities in developing economies emphasize the critical need for institutional safeguards to prevent capital flow volatility from undermining financial stability.

Brazil, during the 2010s, experienced a surge in unhedged corporate foreign debt, particularly among SMEs and state-owned enterprises, making them highly susceptible to currency depreciation. In response, the government introduced mandatory hedging regulations, requiring firms with significant FX liabilities to maintain a minimum level of hedged exposure. Empirical analyses have shown that these measures significantly reduced default rates during periods of currency turbulence, demonstrating the effectiveness of regulatory intervention in mitigating FX-related financial distress.

Following the Asian Financial Crisis, Indonesia implemented compulsory FX hedging for corporates with substantial external debt, alongside targeted subsidies to lower the cost of hedging for SMEs. This policy intervention was informed by extensive post-crisis research highlighting the dangers of currency mismatches, such as the work of Corsetti, Pesenti, and Roubini (1999). By reducing the prevalence of unhedged positions, Indonesia was able to improve corporate balance sheet resilience and minimize financial contagion risks.

Thailand’s experience following the 2013 Taper Tantrum further underscores the value of institutionalized FX risk monitoring. Recognizing that systemic exposures had built up over time, Thai regulators introduced a centralized FX risk surveillance system, enabling real-time monitoring of external liabilities across corporate balance sheets. This framework provided policymakers with early warning signals, allowing for targeted interventions during periods of heightened global financial volatility.

Policymakers: A Proactive Oversight Role

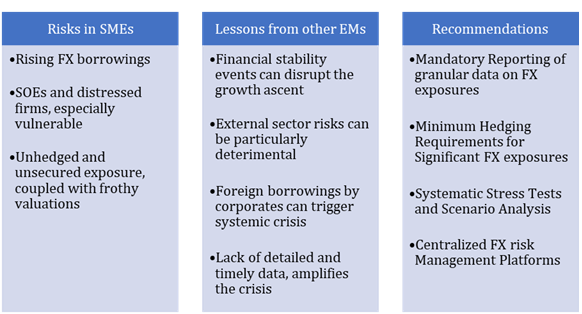
In India, the lack of granular, real-time data on FX exposures—particularly among SMEs and mid-sized firms—remains a critical blind spot. While macroeconomic indicators such as foreign exchange reserves and external debt-to-GDP ratios suggest resilience, firm-level data is limited, impeding regulators’ ability to assess emerging vulnerabilities before they escalate. Closing this information gap requires mandatory reporting frameworks that capture sector-specific FX liabilities, currency compositions, and hedging strategies. This is especially relevant for SMEs, where data collection and publication of risk indicators should be a priority.

The introduction of minimum hedging requirements for significant FX exposures could serve as a crucial policy safeguard. Drawing from Brazil and Indonesia’s experiences, such requirements could prevent an unchecked buildup of unhedged foreign liabilities, particularly among SMEs and SOEs with high leverage ratios.

Systematic stress testing and scenario analysis must also become an integral component of India’s financial stability framework. Regulators should evaluate corporate balance sheets under adverse currency movement scenarios, assessing potential solvency and liquidity risks. These exercises can provide early warning indicators, allowing policymakers to adopt targeted measures before external shocks materialize into broader financial distress.

Furthermore, a centralized FX risk management platform, led by the Reserve Bank of India, could provide SMEs with institutional support by offering hedging instruments, market intelligence, and financial advisory services. This would lower the cost and complexity of FX risk management for firms with limited treasury capabilities, encouraging greater participation in hedging markets.

Corporate India: Strengthening Internal Resilience
Corporate India must internalize the importance of comprehensive FX risk management as an essential pillar of financial resilience. A robust corporate treasury function, equipped with advanced risk assessment tools, can significantly enhance firms’ ability to navigate external volatility.

Strengthening FX governance entails:

  1. Enhancing treasury and risk management functions by investing in dedicated treasury teams or collaborating with financial institutions that specialize in FX risk advisory.
  2. Adopting advanced hedging strategies beyond basic forward contracts, including options, swaps, and structured hedging products that align with global best practices.
  3. Leveraging AI-driven forecasting models to improve accuracy in predicting currency fluctuations, enabling firms to make more informed hedging decisions.
  4. Increasing transparency in FX risk disclosures by publishing detailed information in financial reports on FX exposures, stress test results, and hedging strategies to enhance investor confidence and strengthen market discipline.
  5. Diversifying currency exposure to reduce over-reliance on the US dollar by exploring mechanisms such as UPI-enabled cross-border trade in local currencies, aligning with broader de-dollarization efforts in global trade.

Conclusion

India’s aspiration to attain developed-market status by 2047 will depend on its ability to effectively manage emerging macro financial vulnerabilities, particularly those linked to external financing risks. SMEs, despite being key engines of growth, are increasingly exposed to FX risk, which, if left unchecked, could evolve into a systemic fragility.

Policymakers must strengthen institutional safeguards by enhancing data transparency, implementing minimum hedging requirements, and integrating FX stress testing into regulatory oversight. Meanwhile, corporate India must adopt a proactive approach to risk management, improving treasury governance and embedding hedging strategies into financial decision-making.

By aligning financial stability imperatives with economic expansion, India can ensure that external vulnerabilities do not become a constraint on its growth ambitions, preserving the resilience of its financial system on the path to 2047.

Chart 5: Summary of Key FX Risk Trends and Policy Implications
India’s Financial System: Between Expansion, Risk, and Reform

India’s rise as the world’s fifth-largest economy is a defining moment, but sustaining this momentum and ensuring long-term, sustainable growth demands a hard look at its financial system. Rapid economic expansion has stretched the system in multiple directions, exposing structural weaknesses, regulatory gaps, and emerging systemic risks. The IMF’s latest Article IV Consultation and Financial Sector Assessment Program (FSAP) recognizes the growing strengths of India’s financial system but also highlights key vulnerabilities — delays in strengthening regulatory oversight, a shallow bond market, limited exchange rate flexibility, and rising risks in digital finance and nonbank financial institutions. India must act decisively in an increasingly volatile global financial environment to ensure its financial system remains globally competitive while supporting domestic economic priorities. The need for deeper financial markets, stronger institutions, and a more adaptive policy framework is no longer a distant ambition but an urgent policy imperative.

Since the 2008 Global Financial Crisis, India’s banking system has improved significantly, with stronger prudential regulations, better capital buffers, and declining non-performing assets. NPAs fell to 3.2% in 2024, the lowest in a decade — but the IMF warns they could rise to 5.8% under macro-financial stress, revealing the fragility of credit risk management. A significant concern is the continued dominance of public sector banks, which hold 60% of total banking assets. While they serve a critical role in financial inclusion, they also contribute to concentrated credit risks and inefficiencies in capital allocation. Their influence extends to the expansion of nonbank financial institutions, raising risks of spillover contagion due to their deep linkages with banks.

The rise of nonbank financial institutions has played a crucial role in expanding credit access, particularly for sectors underserved by traditional banks. However, their increasing interconnectedness with banks has created systemic risks. While regulatory oversight has improved, concerns persist over liquidity mismatches, dependence on short-term wholesale funding, and opaque risk exposures. The IMF underscores the need for stricter liquidity stress tests, higher capital adequacy norms, and better regulatory alignment between banks and NBFIs. Strengthening these measures will be crucial to containing risks and preventing financial contagion.

India’s capital markets have gained momentum, with the National Stock Exchange surpassing China in IPO volume in 2024, raising $19.5 billion through 268 IPOs. This surge signals growing investor confidence and deeper market liquidity. However, the corporate bond market remains severely underutilized, accounting for only 17% of GDP, far below peer economies like Malaysia and South Korea, which stand at 35–40%. As a result, businesses rely disproportionately on bank financing, making corporate credit cycles more vulnerable to economic downturns. Expanding the bond market is critical for diversifying financing channels and improving capital allocation efficiency. The IMF identifies three key reform priorities: broadening the institutional investor base to create stronger demand for corporate bonds, improving secondary market liquidity to help price discovery, and streamlining regulatory processes for corporate debt issuance and more participation. Without these reforms, India’s capital markets will continue to lag behind its vibrant equity markets, constraining long-term investment and economic stability.

The IMF’s review of India’s exchange rate management highlights a growing trade-off between currency stability, external competitiveness, and financial market flexibility. The Reserve Bank of India holds over $630 billion in foreign exchange reserves, providing a critical buffer against external shocks. However, frequent currency market interventions have limited exchange rate flexibility, raising concerns over external competitiveness and financial market efficiency. India’s push for rupee internationalization is a strategic step toward reducing reliance on U.S. dollar-denominated payment settlements. But for this initiative to succeed, India must expand rupee-based financial instruments to facilitate cross-border trade, improve offshore rupee market liquidity to attract global investors, and create a more predictable regulatory framework to encourage sustained foreign capital flows.

Few economies have embraced digital finance as rapidly as India. The Unified Payments Interface processed over $2.4 trillion in transactions in 2024, cementing India’s position as a global leader in real-time payments. Meanwhile, the Digital Rupee is positioning India at the forefront of monetary digitization and cross-border payment efficiency. The IMF and BIS recognize India’s CBDC initiative as one of the most technically advanced emerging markets. However, digitization brings its own set of risks. Cybersecurity threats, rising cases of digital fraud, and the growing dominance of a few large fintech players raise concerns over market concentration and systemic vulnerabilities. Stronger consumer protection laws, enhanced cybersecurity measures, and stricter oversight of dominant digital payment firms can help improve systemic resilience.

As India’s global economic influence expands, the strength and adaptability of its financial system will shape both domestic stability and India’s international financial integration. However, domestic macro-financial and economic stability must remain the priority before global ambitions can be fully realized. A comprehensive review is, therefore, imperative. By deepening financial resilience, accelerating capital market reforms, and fostering global financial integration, India can reinforce its position as a stable, competitive, and inclusive financial powerhouse — one that is fully aligned with its long-term economic ambitions.

Udaibir Das is a Distinguished Fellow at ORF America, Visiting Professor at NCAER, Senior Non-Resident Adviser at the Bank of England, Senior Adviser to the International Forum for Sovereign Wealth Funds, Distinguished Visiting Faculty at the Kautilya School of Public Policy, and Senior Advisor at the Toronto Centre. He previously held roles at the BIS, IMF, Reserve Bank of India, and Bank of Guyana.

Tackling the Impact of Trump Tantrum

After a steady rise for over two years, Indian markets have been in a correction phase since October 2024. Equity markets have declined by 14 percent; the exchange rate has depreciated by 4 percent; the reserves have declined by $65 billion (9 percent of the stock that existed); while FII investors have pulled out nearly $23 billion from the equity and debt markets.

Painful as it seems, the current sell-off is not a one-off phenomenon. Nor is it unique to India. Similar episodes of risk aversion and portfolio rebalancing out of Emerging Markets (EMs) have been occurring every two years, adding up to six such episodes during the last decade – in 2013, 2016, 2018, 2020, 2022, and 2024.

Significantly, four of these episodes have coincided with policy or political developments in the US, pointing to its influence on EMs.

The first sell-off occurred in 2013 (Taper Tantrum), when then Federal Reserve Chairman Ben Bernanke announced the Fed’s intent to reverse the pace of its ultra loose monetary policy. It resulted in an exodus of capital flows from EMs, a sharp depreciation of their exchange rates, decline in equity markets, and increase in bond yields.

The EMs faced  similar shocks  in 2016 after the election of President Trump; in 2018 when the US pressed the pedal on tariffs on China to which Beijing retaliated; in 2020 when   COVID struck; and in 2022 when the Ukraine-Russia war broke out. The latest episode started in early October, when the Fed’s guidance on policy rate was reset to “higher for longer”, and built up as  Trump’s disruptive trade agenda started taking shape.

India was one of the five most impacted economies during the first sell-off in 2013, when its exchange rate depreciated by 25 percent, reserves declined by 6 percent, and equity markets by 9 percent. In 2018, its exchange rate depreciated by 15 percent, reserves declined by 8 percent, and equity markets by 3 percent. In 2022, its exchange rate depreciated by 10 percent, reserves declined by 16 percent, and equity markets by 13 percent.

There are several similarities across these episodes.

First, the impact across countries has less to do with their economic strength, and more to do with the presence of reversible capital, the ease with which this capital can be withdrawn, and the extent of overvaluation. Thus, while strong macroeconomic fundamentals do not insulate India, the extent of reversible capital, its large and liquid markets, and potential overvaluations make it a fertile ground for these reversals.

Second, these events are short-lived, each lasting only a few months. The reprieve starts as soon as valuations become attractive and EMs appear competitive again.

Third, despite initial trauma, they do not leave a trail of destruction. Domestic financial sectors remain resilient to them, neither do they result in economic slowdowns.

Finally, the existing policy frameworks enable countries to respond promptly and adequately to them. Dealing with them does not necessitate any drastic measures including any assistance from the IMF. Countries are able to leverage flexible exchange rates, pool of forex reserves, prudent banking regulations, robust fiscal architecture, and credible monetary policy frameworks (e.g. inflation targeting) to handle them.

Past experiences, thus, suggest that the current storm too shall pass soon, without causing grave damage. Meanwhile, the next one may not be too far on the horizon.

How may India prepare both ex ante and ex post, for future shocks?

For ex ante measures, India should encourage stable, longer-term capital inflows (such as FDI) over volatile short-term flows (like FII flows). It should rebuild its reserves buffer as soon as the conditions turn conducive. While avoiding excessive appreciation or volatility of the exchange rate, it should still let it move more than has been the case in the recent past.

To soften the impact ex post, a fine calibration of exchange rate depreciation and use of reserves is needed. In recent years, policy response has shifted more toward the use of reserves while limiting the depreciation of the exchange rate. This ought to be revisited for speedier mitigation of  the shocks.

It would also help to re-assert the commitment to reforms, macroeconomic stability, and growth in such risk-off times. Equally important is to avoid any policy mis-steps, such as new forms of capital controls (as per the experience in 2013), and adopting a clear communication strategy with the market participants. Occasionally, swap lines with specific countries (particularly Japan) may be renewed; and schemes aimed at attracting funding from the Indian diaspora could be reintroduced.

These events serve as reminders that having graduated to the class of a large emerging market, India needs to remain vigilant, prudent, communicative, and committed to reforms, growth, and macroeconomic stability at all times.

The writer is Director General, NCAER. Views are personal.

That Sadly Uncracked Glass Ceiling

Among the many achievements of G20 under India’s leadership in 2023 was their specific commitment to promote women-led development. This commitment went beyond the general catchall of advancing “women’s economic empowerment”.

It signalled an increasing recognition by world’s top leaders that promoting full, equal, effective, and meaningful participation of women in the economy as decision-makers benefits society multidimensionally.

What are these benefits? Where’s the evidence? What is India’s record in promoting more women to the top? What are the hindrances, and what more can be done?

Women in leadership posts | Countries that have embraced gender diversity in decision making have witnessed better economic and financial performance of their economies and companies.

Women leaders in politics also enhance social development. Those in the corporate sector contribute to inclusive workplace policies, fostering a culture of fairness and equity.

In our research paper, co-authors Benedict Clements, Huy Nguyen, and I find that in a sample of about 120 countries, higher share of women in parliaments and cabinet positions raises govt health spend, both as share of GDP and as a share of total spend.

Greater representation of women in policymaking has positive effects on social outcomes, such as infant mortality rates, access to basic water services, and upper secondary school enrolment rates.

Studies conducted by Esther Duflo (Nobel laureate in 2019) and her co-authors during 2004-09 find that female political leadership in Indian villages has several societal benefits. It positively influences adolescent girls’ career aspirations and educational attainment. Female leaders invest more in infra. Exposure to women leaders improves perceptions about their effectiveness and weakens stereotypes about gender roles, while women are also more likely to stand for, and win, elected positions.

The corporate sector, too, benefits. An IMF global study reported that a higher share of women on commercial bank boards and supervisory positions goes hand-in-hand with lower non-performing loans and greater financial stability. A cross-country study of fintech firms also finds that gender diversity on executive boards improves firm’s performance in terms of funding obtained and revenues earned.

In a recent paper on India, my co-authors and I find that having at least one woman on the board in NSE-listed firms is associated with higher profitability and lower debt-equity ratio. When such firms hire women in top management positions as well, employee ratings and sentiment scores are also higher.

Why are women in India not breaking the glass ceiling? | India still has a long way to go in achieving gender parity in policymaking. As of 2024, women held 14% of Lok Sabha seats and 15% in Rajya Sabha, and occupied less than 7% of ministerial positions. This places India far behind the emerging market and developing economies’ average of 23% for parliamentary positions and 20% for ministerial positions.

However, India’s grassroots political representation presents a more encouraging picture. Reservation for women in panchayati raj institutions (PRIs) ranging from 33% to 50% has led to 1.4mn elected women representatives, enhancing gender balance in policymaking at the local level.

Companies Act (2013) played a pivotal role in increasing representation of women on boards in the corporate sector. Between April 2014 and April 2015, the share of women rose from about 5% to nearly 10%. As of April 2023, women held nearly 16% of board positions and 22% of top management positions, according to PRIME Database. This progress, while commendable, still falls short of global averages.

Challenges women face in rising to the top | Several factors contribute to the underrepresentation of women in Indian politics. They face higher levels of harassment, threats, and violence, and patriarchal norms and societal stereotypes remain deeply entrenched. Even when women are elected to political office, decisions are often influenced or controlled by male family members, undermining their autonomy. Financial barriers exacerbate the problem. Women candidates often struggle to secure the funding needed for political campaigns.

What constrains women from rising to the top in corporate sector? While women’s education levels are pretty much at par with men in India, female labour force participation, according to the latest PLFS survey, at nearly 42% is substantially lower than those of men at about 79%. A major factor preventing women from joining the labour force is the disproportionate burden they carry at home of unpaid household duties besides child and elderly care responsibilities. If women don’t join the workforce or many drop out after children are born, the pipeline of senior women shrinks substantially.

A path forward | Govt policies, corporate initiatives, and societal change must work in tandem to dismantle barriers for women.

To increase female labour force participation and prevent women from exiting the labour force, govt regulation and corporate policy should formalise part-time employment, as is common in advanced economies. This means that part-time employment is at par with full-time employment in terms of job security, medical coverage, and other benefits. School and college curricula should incorporate leadership training programmes.

The corporate sector could also set targets for women in C-suite positions, introduce mentorship programmes, and gender bias training. Finally, more equitable burden sharing of unpaid care between men and women and ensuring the safety of women through effective implementation of legal protections against violence and anti-harassment policies should take centre stage.

Creating professional linkages between successful elected women leaders and sharing of peer experiences at the village level can be a step towards addressing the control by male family members. Parliament passed the women’s bill for 33% reservation of seats in Lok Sabha and state assemblies. Its implementation is put off till after delimitation, which will happen only after Census is held. It is never too soon for gender parity in legislatures. 

The writer is Professor, NCAER. Views are personal.

Bolstering critical minerals trade between India and other MSP countries: A gravity model evaluation

This study aims to evaluate the opportunities for a sustainable environment, an equitable economy, and a just society through the international trade of critical minerals. By employing a gravity model, it intricately analyzes the trade dynamics between India and 13 other members of the Mineral Securities Partnership (MSP). The study indicates a landscape rich with potential for enhancing environmental protection; however, this is somewhat overshadowed by a decrease in the overall impacts on the economic and social dimensions of sustainable trade practices. The apparent lack of synergy among the various outcomes that arise from increased trade underscores a pressing need for policymakers to create pathways where environmental, economic, and social opportunities can harmoniously reinforce one another, amplifying the benefits of critical mineral trade. Moreover, the empirical findings highlight that income heterogeneity positively influences sustainable trade practices across environmental, economic, and societal fronts, thereby affirming the Heckscher-Ohlin hypothesis. Crucially, the study identifies the variability in trade uncertainty between partners as a powerful catalyst for trade and a driver of innovation within MSP countries. The discussion further delves into the effects of research and innovation, currency exchange, and geographical distance on sustainable trade, especially concerning QUAD and non-QUAD nations. This emphasizes the imperative for customized strategies that elevate global sustainable trade, considering the unique economic structures and regulatory landscapes at play.

    Get updates from NCAER