

While lithium-ion batteries have enabled the expansion of renewable energy storage so far, these are now confronting physical and chemical barriers. In this post, Mitra and Pohit put forth that the clean energy sector has successfully transitioned to a multi-chemistry ecosystem that leverages both physical materials and artificial intelligence. They highlight the opportunity that this paradigm shift presents for India to secure a self-reliant energy future.
The global push toward clean energy currently depends almost entirely on standard lithium-ion batteries. This dominant technology has successfully launched the initial wave of electric vehicles (EVs) and expanded renewable energy storage. Until now, the industry has utilised it as a universal solution for nearly all power storage requirements.
However, this singular approach is now confronting strict physical and chemical barriers. Standard lithium-ion cells have essentially reached the absolute limit of the energy they can safely contain. The global market demands much higher capacities, but pushing traditional designs to hold more power yields rapidly diminishing returns. More critically, attempting to extract additional capacity inherently compromises the thermal stability of the cell, which significantly elevates safety risks such as overheating and fires.
Consequently, the energy storage sector is undergoing a necessary and profound structural shift. The global industry is officially abandoning the search for a single universal battery to solve every power problem. Instead, the technological trajectory is pivoting toward a highly diversified system. The future relies on deploying a fragmented matrix of specialised batteries. In this new paradigm, different chemical architectures are precisely engineered and optimised for distinct operational environments and specific jobs.
The three new “post-lithium” contenders
Three primary post-lithium technologies are currently emerging to lead this new energy ecosystem. Each individual architecture targets a specific industrial bottleneck by optimising a different performance axis, ensuring that specific applications receive tailored storage tools.
The first major advancement is solid-state battery technology, which functions as the distance runner of the energy storage world. Standard batteries rely on a volatile internal liquid to transfer power, which can leak or catch fire under heavy stress. Solid-state designs completely replace this liquid with safe, solid compounds. This structural shift provides two massive advantages. First, it completely suppresses the risk of catastrophic fires, making the device exceptionally stable. Second, it allows the cell to pack immense amounts of energy into a remarkably small and lightweight footprint. Because they deliver maximum energy capacity per kilogram, solid-state systems are perfect for heavy transportation sectors. They are ideally suited for luxury electric vehicles that require an extended driving range exceeding 1,000 kilometres on a single charge, as well as for the strict weight limitations of aerospace engineering and electric aircraft.
The second major contender is the sodium-ion battery, which operates as the budget-friendly workhorse of the clean energy transition. Instead of relying on expensive and highly concentrated lithium reserves, these systems are built using sodium, a globally abundant material that behaves similarly to common table salt. On a physical level, sodium-ion cells are heavier and possess a lower energy density than traditional lithium alternatives. However, they offer extraordinary economic and operational benefits. They are dramatically less expensive to manufacture, virtually non-flammable, and capable of retaining their power capacity in extreme cold temperatures as low as minus 40 degrees Celsius. Because physical footprint and weight are secondary concerns for stationary power units, sodium-ion technology is the ideal solution for stabilising national electricity grids that manage wind and solar energy.
The third major breakthrough is the silicon-enhanced battery, which serves as the ultimate sprinter of the group. Unlike completely new cell designs, this technology is an immediate upgrade that can drop directly into existing manufacturing lines. It replaces traditional internal graphite components with advanced silicon materials. The primary advantage of silicon is its ability to accept and transfer electrical current at an unprecedented pace. This capability effectively solves the long charging times that slow down widespread consumer adoption. By integrating silicon, everyday passenger vehicles can charge to 80% capacity in less than 10 minutes, while specialised aerospace models can achieve this in just six minutes. This technology provides maximum convenience for daily commuters and high-performance electronic devices.
To easily compare how these three distinct technologies fit into our daily lives, we can evaluate them based on their specific strengths and trade-offs (Figure 1). As the data show, the energy market is fracturing into specialised roles where no single battery is expected to do everything.
Figure 1. Heatmap illustrating the application suitability matrix for post-lithium battery architectures

Source: Authors’ creation. These scores are derived based on technical performance metrics from the International Energy Agency and Bloomberg NEF against the specific economic and operational constraints of each application market.
Ultimately, the global industry is segmenting into distinct technological silos. The future energy market will rely on a matrix where solid-state maximises total travel distance, sodium-ion minimises levelised economic costs, and silicon-enhanced integration accelerates charging speeds.
Software is the new hardware
The physical chemistry of a battery represents only half of the energy storage equation. The other critical half relies entirely on advanced software. Modern energy storage systems have officially transitioned from passive hardware components into complex cyber-physical units. The internal management software now serves as the essential brain of the battery, proving that digital optimisation is just as vital as material science for extending operational life and performance.
Furthermore, smart management algorithms directly improve daily economic value by actively maximising operational efficiency. Batteries operate most efficiently within a highly specific temperature range. Artificial intelligence continuously monitors real-world driving habits and external weather conditions to dynamically adjust the internal cooling and heating mechanisms. By keeping the cell within its optimal thermal envelope, these smart management systems extract 5-10% more usable driving range from the exact same battery pack. This software-driven efficiency gain requires zero additional raw materials, making it an incredibly cost-effective method to boost overall capacity.
Geopolitics and India’s golden opportunity
The global transition toward clean energy has inadvertently created a fragile geopolitical landscape characterised by severe resource concentration. Under the current technological framework, the production of standard lithium-ion batteries relies heavily on a narrow selection of critical minerals, primarily lithium, cobalt, and nickel. The extraction and refining of these vital resources are highly concentrated within a small number of specific nations. This extreme geographic monopoly leaves the global supply chain highly vulnerable to trade disruptions, unexpected export restrictions, and sudden political conflicts. For developing nations actively expanding their transport sectors, this situation creates a dangerous mineral trap where domestic energy security becomes entirely dependent on foreign mineral policies and volatile global market prices.
To resolve this systemic vulnerability, economic strategists advocate for a profound industrial strategy known as technological leapfrogging. Instead of investing massive capital to build large factories for traditional lithium-ion cells, emerging economies like India have a unique window to skip this developmental stage entirely. Global competitors already possess insurmountable economies of scale in older lithium technologies. By deliberately redirecting state subsidies and domestic capital investments away from older chemistries, domestic manufacturers can invest directly in next generation storage platforms. This strategic pivot allows the nation to build entirely new supply networks from the ground up, utilising alternative materials that are completely insulated from global resource shortages.
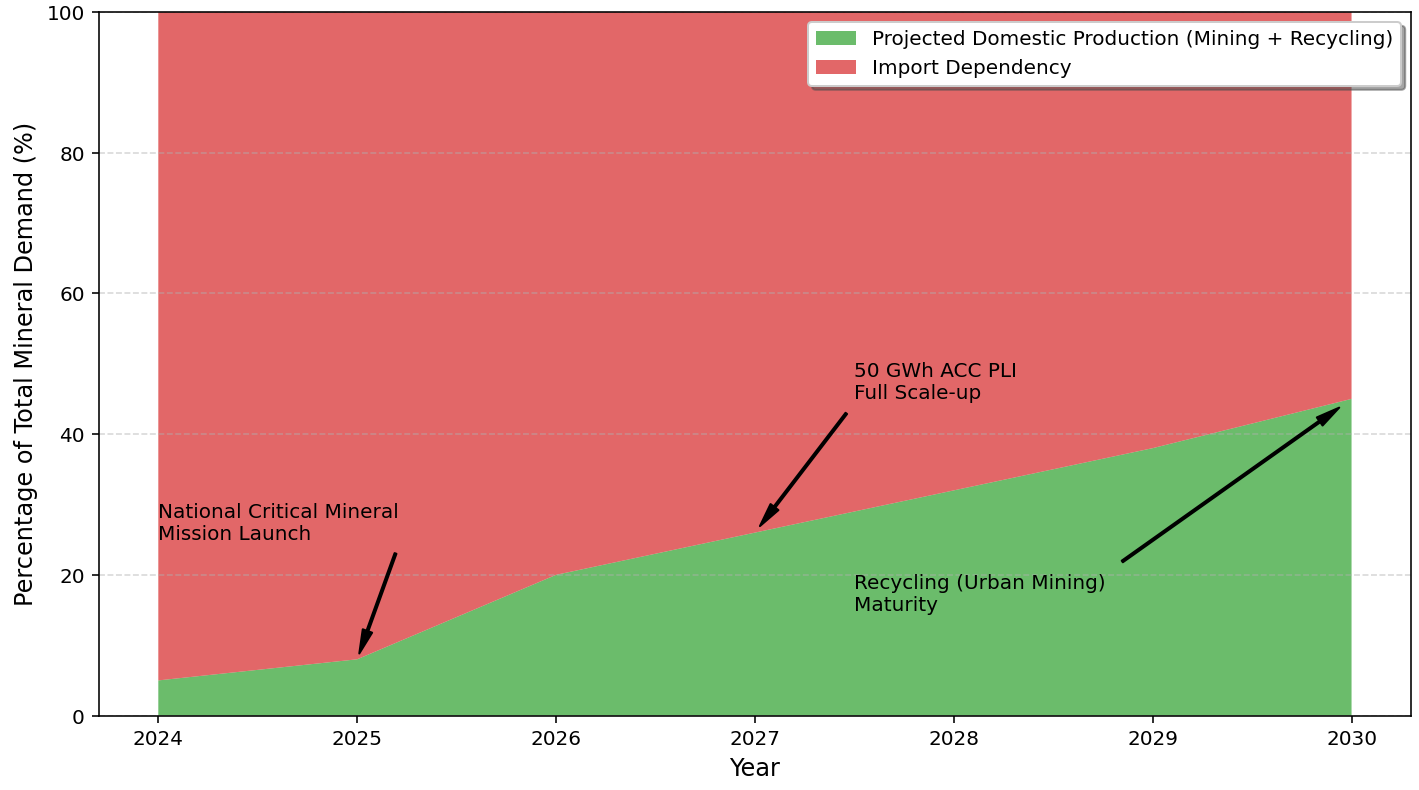
India’s clean energy trajectory highlights the profound long-term impact of this strategic shift. By moving away from a reliance on traditional critical minerals, the country is positioned to systematically reduce its external vulnerabilities over the next few years (Figure 2).
Figure 2. Projection of India’s strategic pivot from mineral import dependency toward domestic self-reliance
Source: Authors’ creation.
Sodium-ion technology represents the ultimate vehicle for this leapfrogging strategy. Unlike lithium, which is geologically scarce and fully imported, sodium is an abundant and easily accessible element. India can harvest the essential raw inputs for sodium-ion cells directly from its vast domestic rock salt deposits and extensive coastal seawater resources. This baseline availability offers a direct pathway to complete resource independence.
Furthermore, the physical characteristics of sodium chemistry perfectly match India’s geographic realities. Standard lithium batteries are highly sensitive to extreme heat, creating severe fire risks during intense tropical summers. In sharp contrast, sodium-ion cells possess exceptional thermal stability, maintaining safe operations under elevated temperatures. Additionally, because sodium-ion batteries offer a superior cycle life and a remarkably low lifetime cost, they are the most economically viable solution for stabilising India’s rapidly expanding decentralised renewable energy grid. By tailoring industrial policy to these realities, India can transform a supply chain crisis into domestic clean energy leadership.
Conclusion
The year 2026 marks a definitive inflection point in global energy storage, officially concluding the era of a monolithic lithium-ion dependency. The clean energy sector has successfully transitioned into a highly optimised, multi-chemistry ecosystem where physical materials and advanced artificial intelligence work in tandem to maximise performance.
Ultimately, the future of power storage is diverse, smart, and localised. The commercialisation of post-lithium platforms proves that capacity gains will be driven as much by algorithmic efficiency as by material science. For emerging economies, navigating this complex technological shift offers a critical window for structural autonomy. By aggressively embracing specialised chemical architectures, deploying smart digital twin software, and establishing strategic domestic supply networks, nations can effectively bypass foreign mineral monopolies. This comprehensive paradigm shift allows countries to secure a clean, highly resilient, and entirely self-reliant energy future.
The views expressed do not necessarily reflect that of the authors’ organisation or the I4I Editorial Board. Views are peesonal.