Industrial renewal in the East: Why West Bengal matters again

Once among India’s foremost manufacturing and trading centres, the eastern state of West Bengal gradually ceded ground to western and southern states such as Gujarat, Maharashtra, and Tamil Nadu. In this post, Bandyopadhyay contends that the emergence of a new connectivity-driven growth architecture stretching across eastern India, Bangladesh, and the Bay of Bengal region, opens new possibilities for industry in Bengal.

For decades, the economic trajectory of West Bengal has been discussed through the prism of industrial decline. Once among India’s foremost manufacturing and trading centres — with its engineering industries, jute mills, port economy, and commercial networks — the state gradually ceded ground to western and southern states such as Gujarat, Maharashtra, and Tamil Nadu. 

The long shadow of industrial decline in Bengal

Over the past decade and a half, West Bengal’s share in India’s organised manufacturing has remained modest and, in relative terms, has lagged behind the rapid expansion witnessed in leading industrial states such as Gujarat, Maharashtra, and Tamil Nadu. The western and southern states strengthened their position as India’s principal industrial hub through export-oriented manufacturing, port-led development, and stronger infrastructure ecosystems.The evidence becomes even more striking when one examines the trend in Gross Value Added (GVA) relative to fixed capital in organised manufacturing. Figure 2 reveals that West Bengal’s GVA-to-fixed-capital ratio has remained significantly below that of leading industrial states and has generally weakened over time. This suggests lower capital productivity and slower value creation relative to competing manufacturing centres, highlighting the need for a renewed industrial strategy.

Figure 1. Share in total industrial output (% share)
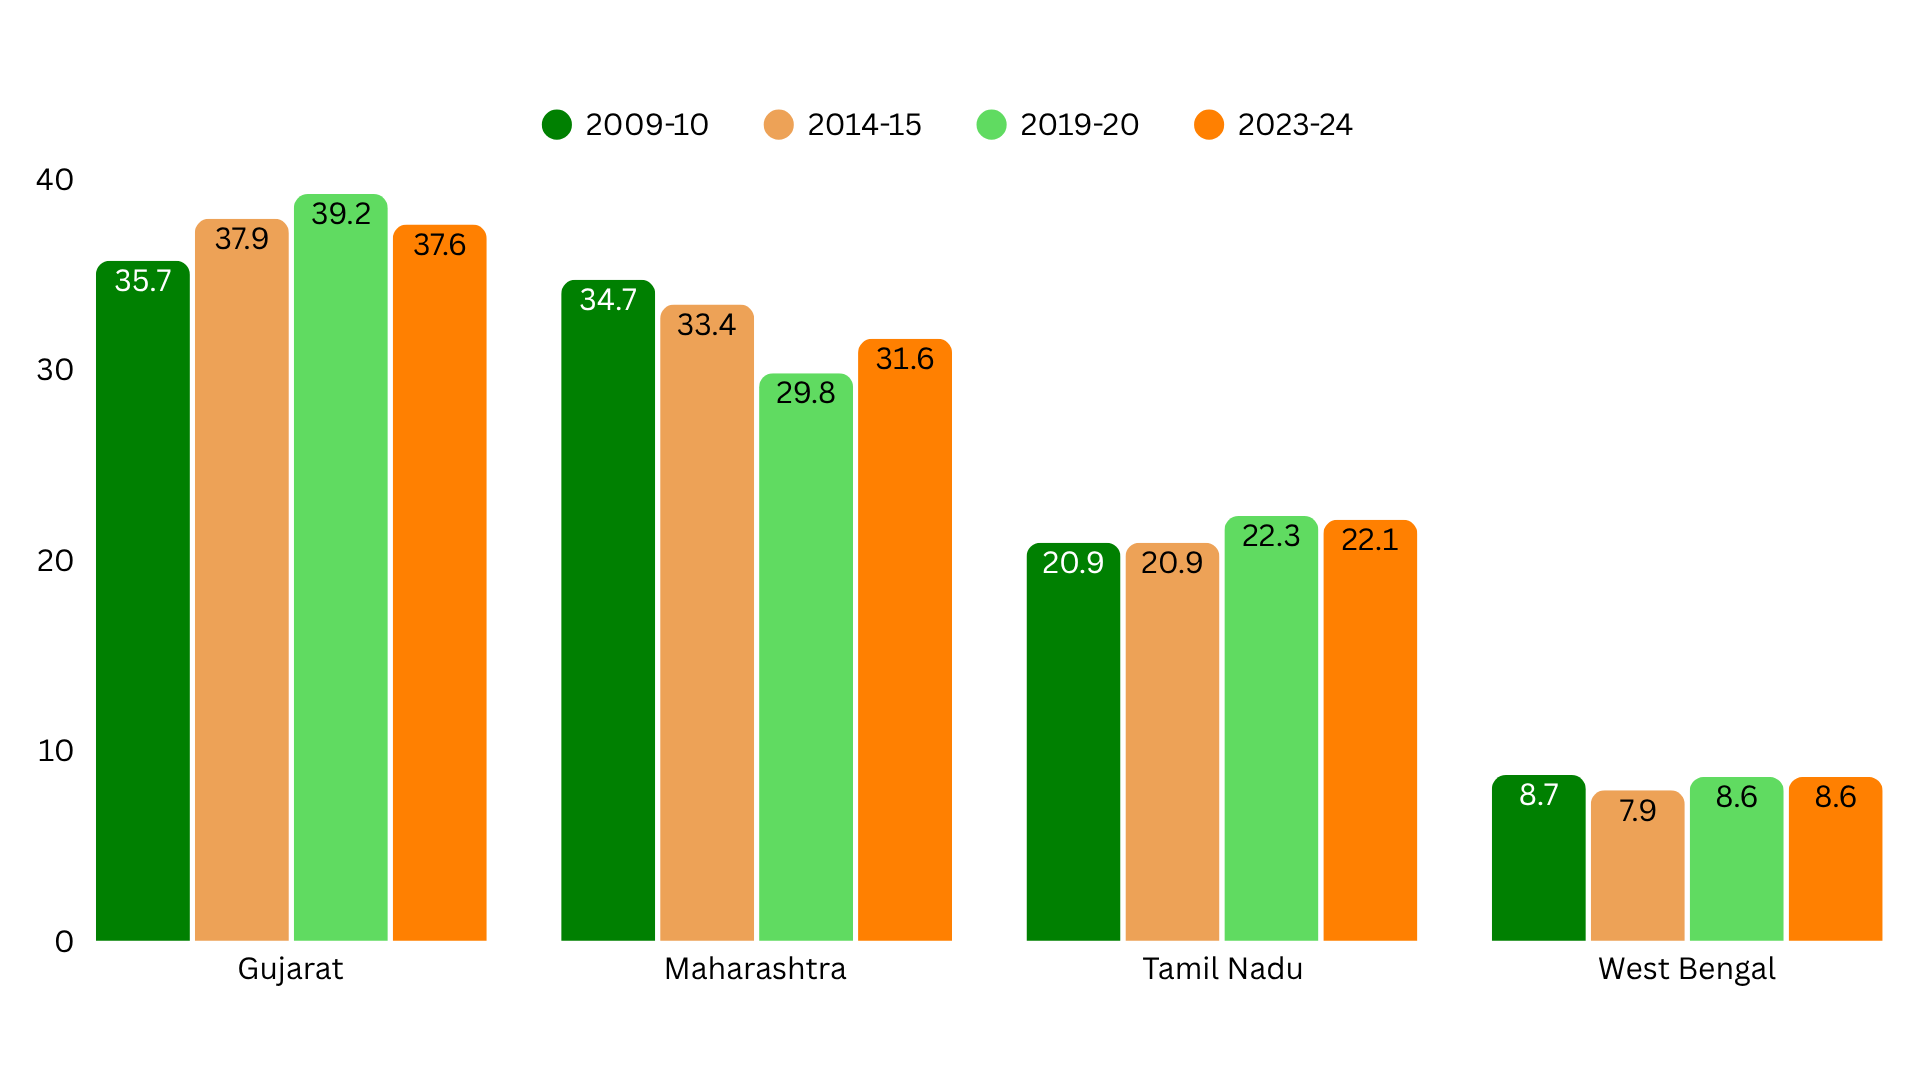
Source: Annual Survey of Industries (ASI), various issues.

The evidence becomes even more striking when one examines the trend in Gross Value Added (GVA) relative to fixed capital in organised manufacturing. Figure 2 reveals that West Bengal’s GVA-to-fixed-capital ratio has remained significantly below that of leading industrial states and has generally weakened over time. This suggests lower capital productivity and slower value creation relative to competing manufacturing centres, highlighting the need for a renewed industrial strategy.

Figure 2. Gross value added relative to fixed capital in organised manufacturing (%)
Source: ASI, various issues.

The scale of this relative decline becomes clearer when viewed through broader economic indicators. Today, West Bengal remains one of India’s largest states in terms of population and aggregate economic size, yet its manufacturing contribution remains significantly below that of leading industrial states. States such as Gujarat and Tamil Nadu have built strong manufacturing-led growth models over the past three decades, reflected in their expanding industrial output and faster growth in aggregate net state domestic product (NSDP). Measured at constant 2011-12 prices, the economies of Maharashtra, Gujarat, and Tamil Nadu have expanded considerably faster than West Bengal’s over the past decade and a half – highlighting the cumulative effects of sustained industrialisation, infrastructure investment, and export-oriented growth strategies. 

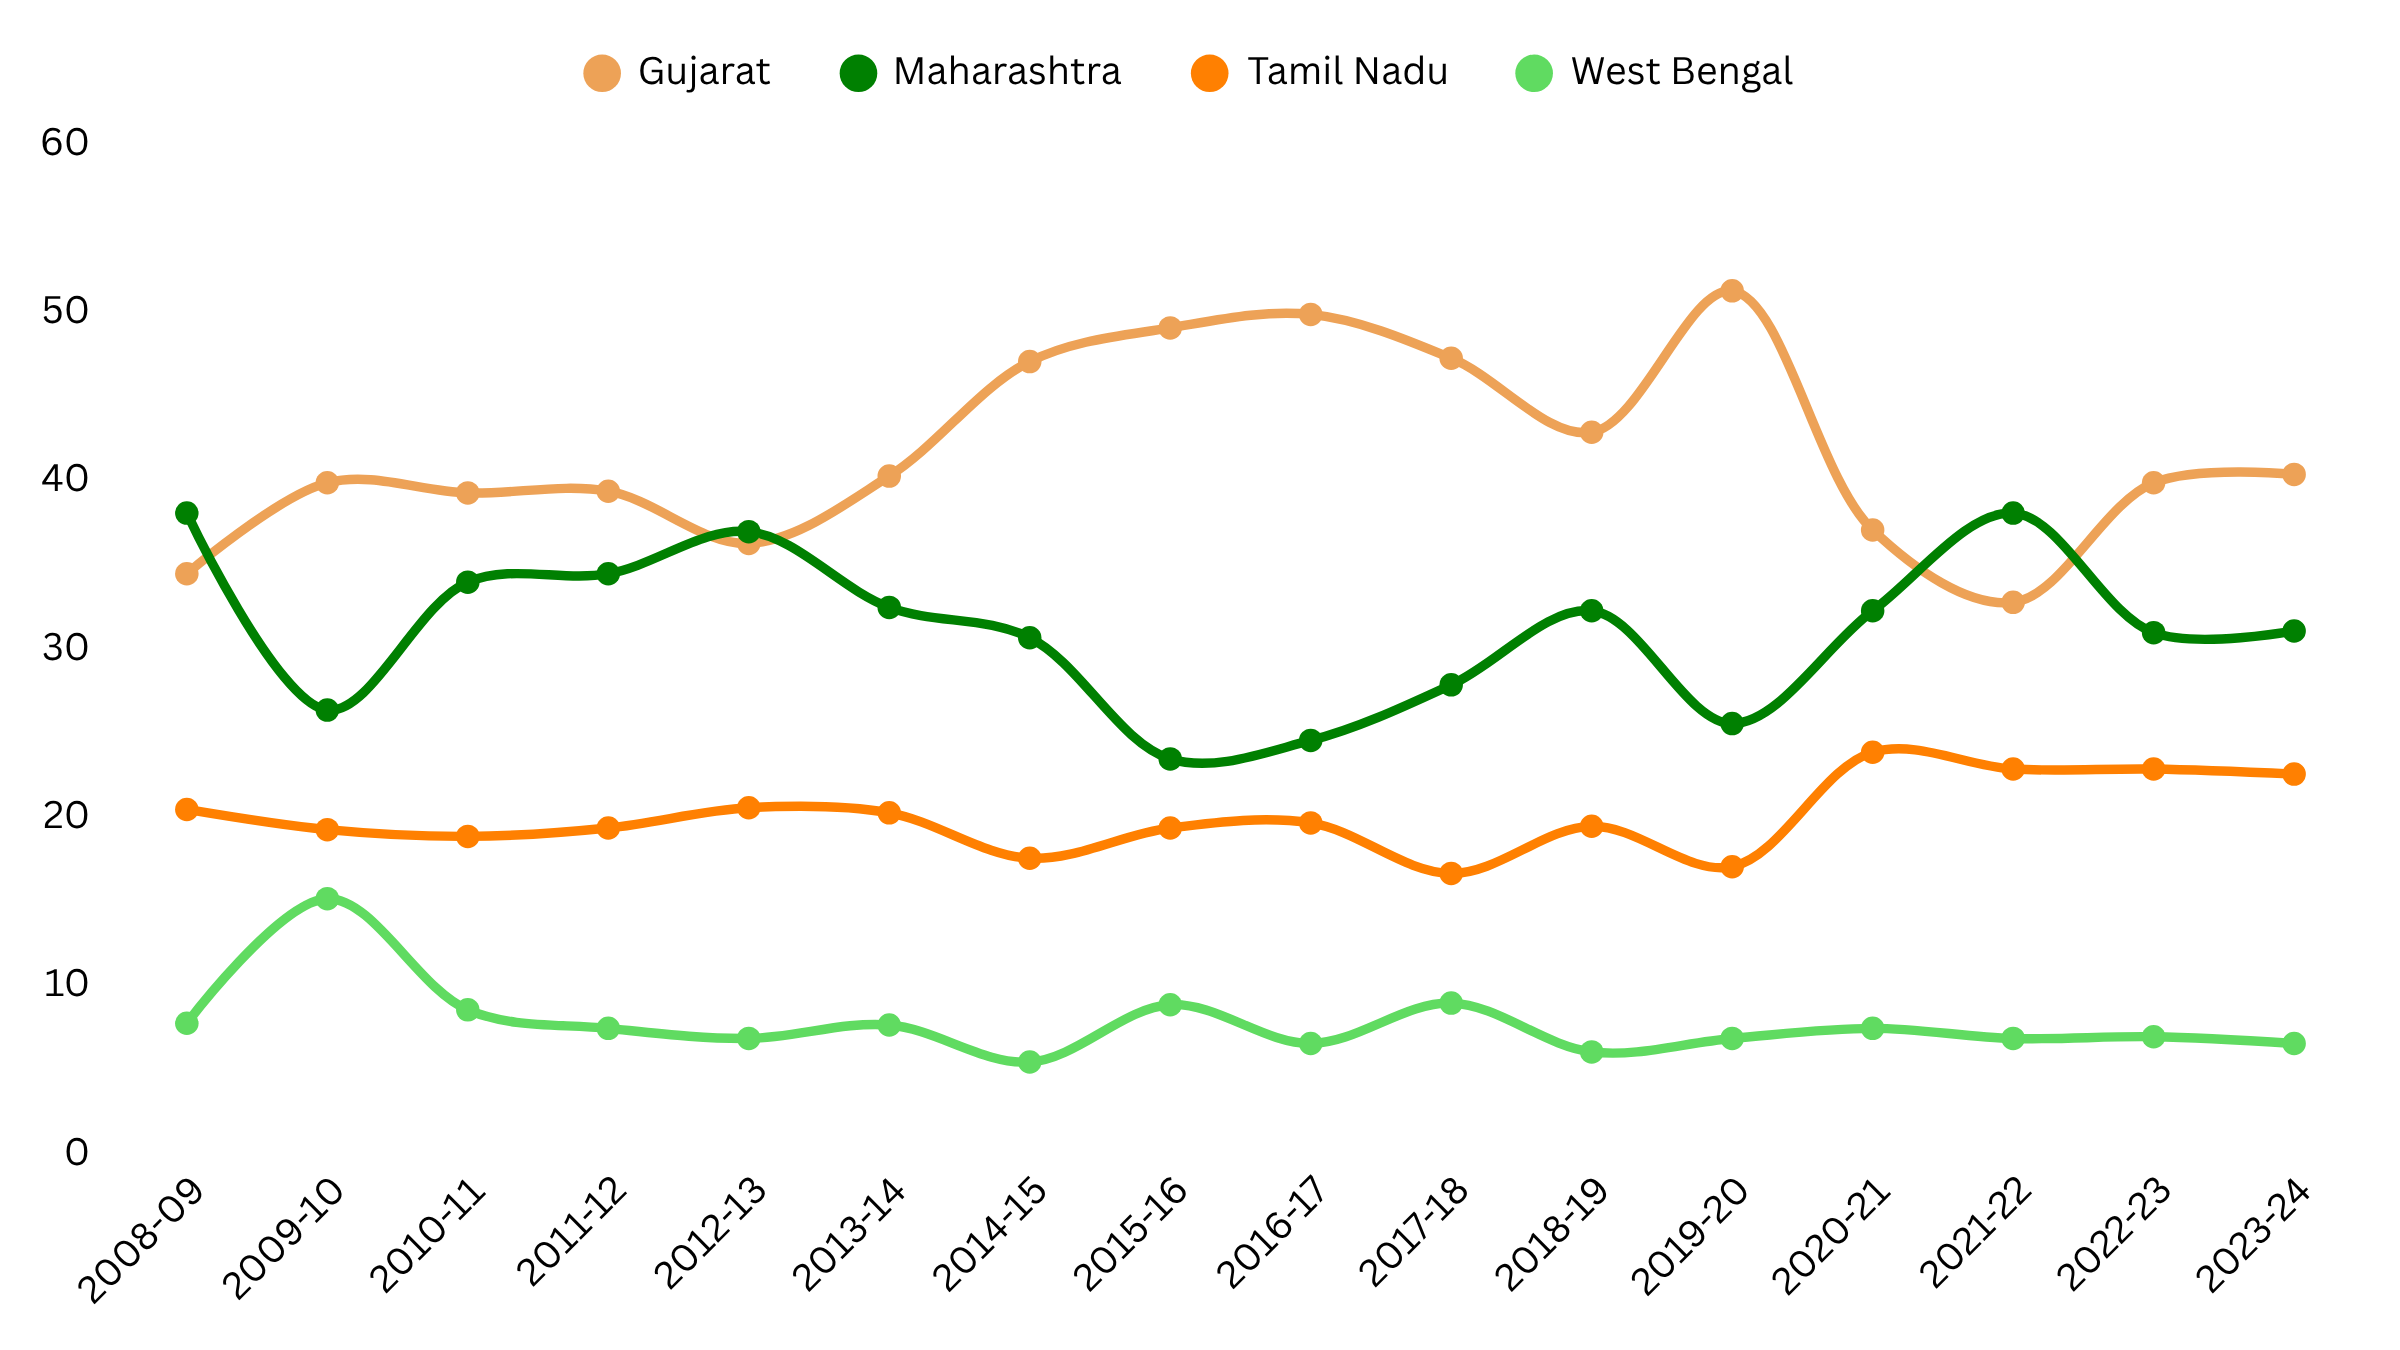
Figure 3 illustrates these divergent trajectories. While West Bengal remains one of India’s largest state economies, its per capita NSDP has grown more slowly than that of several leading industrial states over the past decade and a half. The widening gap reflects differences in industrial dynamism, productivity growth, and structural transformation. Maharashtra’s diversified industrial and services economy, Gujarat’s port-driven manufacturing ecosystem, and Tamil Nadu’s integrated MSME (micro, small, and medium enterprises)-industrial networks have generated stronger income growth, underscoring the developmental dividends of sustained industrialisation.

‍Figure 3. Comparative trends in per capita NSDP across major states (Rs.  ‘000, at constant 2011-12 prices)

‍Source: Ministry of Statistics and Programme Implementation (MoSPI), State Domestic Product Statistics. 

‍Note: Gujarat’s per capita NSDP figure of 2023-24 is provisional.

What makes the present moment different

Yet the comparison is not entirely discouraging for Bengal. Unlike many slower-growing states, West Bengal retains several structural advantages: strategic geography, port access, dense settlement patterns, a large labour force, an established urban network, and proximity to international markets. These advantages are becoming increasingly relevant as India’s economic geography itself undergoes transformation.

What makes the present moment different is not nostalgia for Bengal’s industrial past, but the emergence of a new connectivity-driven growth architecture stretching across eastern India, Bangladesh, and the Bay of Bengal region.

Over the last decade, Bangladesh has emerged as one of South Asia’s fastest-growing economies, with manufacturing exports — particularly garments and textiles — expanding rapidly. Bangladesh’s ready-made garment exports alone crossed US$45 billion in recent years, making it one of the world’s largest textile exporters. As regional production networks deepen across South Asia, India’s eastern states stand to benefit from growing cross-border trade, intermediate manufacturing, and logistics integration. According to the Ministry of Commerce, Government of India, Bangladesh has emerged as India’s largest trading partner in South Asia, with bilateral trade exceeding US$14 billion annually.

For West Bengal, the geographical proximity to Bangladesh is potentially transformational.

Nearly all major land-based trade routes between India and Bangladesh pass through eastern India, with Bengal serving as a principal gateway. Integrated Check Posts such as Petrapole-Benapole already handle a substantial share of bilateral trade between the two countries. Petrapole remains among South Asia’s busiest land ports, and improvements in border infrastructure, customs systems, and cargo handling are steadily expanding commercial activity. 

Beyond facilitating trade, the corridor has the potential to support integrated regional value chains in textiles, food processing, light engineering and logistics services, creating new opportunities for industrial expansion in eastern India. This matters because industrialisation today increasingly follows connectivity.

As supply chains become regionally integrated, border states often gain disproportionate advantages in warehousing, transport services, agro-processing, and light manufacturing. West Bengal is therefore not merely another state economy; it is emerging as India’s principal economic interface between the domestic market and the rapidly integrating economies of Bangladesh and the wider Bay of Bengal region. The significance also extends beyond Bangladesh. The growing strategic importance of the Bay of Bengal region and India’s Act East policy are gradually strengthening connectivity with Southeast Asia. The Bay of Bengal is increasingly being viewed as a critical economic corridor linking South Asia with ASEAN (Association of Southeast Asian Nations) markets through a network of ports, shipping routes, and multimodal transport systems. Projects linking India’s northeast with Bangladeshi ports, multimodal transport systems, and coastal shipping arrangements are beginning to reshape trade flows across the eastern subcontinent.

In this context, Kolkata and Haldia could regain strategic economic importance. Historically, the port economy was central to Bengal’s industrial rise. Today, renewed investments in port modernisation, inland waterways, and logistics infrastructure may once again strengthen the state’s role in regional commerce. 

The inland waterway route connecting the Ganga River system with Bangladesh protocol routes offers another underappreciated opportunity. Water-based cargo transport remains significantly cheaper for bulk commodities compared to road transport. As India pushes multimodal logistics under initiatives such as PM Gati Shakti, eastern river systems could become economically more relevant than they have been for decades.

‍Building long-term economic ecosystems

The experience of Gujarat is particularly instructive here. Gujarat’s industrial acceleration was closely linked to port-led industrialisation, logistics integration, and export-oriented manufacturing clusters. Tamil Nadu, meanwhile, demonstrated how diversified manufacturing ecosystems – combining large industries with MSMEs, skilling systems, and urban infrastructure – can create sustained industrial momentum over long periods. 

While Gujarat leveraged ports to become a manufacturing and export powerhouse and Tamil Nadu built diversified industrial ecosystems around automobiles, electronics, and MSMEs, West Bengal’s comparative advantage may lie in combining logistics, cross-border trade, and labour-intensive manufacturing within a rapidly integrating eastern regional economy.

West Bengal need not replicate these models exactly, but the broader lesson remains important: industrial revival depends less on isolated mega-projects and more on the creation of long-term economic ecosystems where infrastructure, governance, logistics, and enterprise networks function together.

Encouragingly, recent policy signals suggest that the current state government increasingly recognises the centrality of industrial growth for long-term employment generation. Greater emphasis is now being placed on logistics parks, warehousing, MSMEs, tourism infrastructure, data centres, and manufacturing-oriented investments. 

Coordination with the Union government will be equally critical. Large-scale industrial competitiveness today depends heavily on railway freight systems, highway integration, port connectivity, energy reliability, and trade facilitation. Central investments in eastern freight infrastructure and multimodal connectivity can significantly improve Bengal’s attractiveness for manufacturing and logistics industries. 

There are already visible signs of economic transition in eastern India. Expanding highway networks, freight connectivity initiatives, port-led development strategies, and the increasing policy focus on waterways collectively point toward a gradual eastward broadening of India’s growth geography.

For Bengal, this opens possibilities across multiple sectors: food processing, textiles, leather, fisheries, electronics assembly, logistics services, renewable energy components, digital infrastructure, and agro-based manufacturing.

The state’s large MSME base can become particularly important in this transformation. Unlike capital-intensive mega industries that generate limited employment, MSME-led industrial ecosystems create wider labour absorption and stronger local economic multipliers. 

At the same time, optimism must remain balanced with realism.

‍Challenges and opportunities 

West Bengal still faces an investor perception challenge rooted in historical memories of industrial disputes, land conflicts, and administrative uncertainty. Rebuilding confidence therefore requires institutional consistency rather than episodic investment summits.

Administrative predictability, transparent land policies, quicker approvals and stable industrial relations will be essential. Equally important is the need to ensure that industrialisation remains socially balanced through investments in skilling, urban services, and environmental safeguards.

The larger point, however, is that India’s next phase of growth may not mirror the geography of the previous one.

If western and southern India benefited most from the first major wave of post-reform industrialisation, eastern India — led by states such as West Bengal — may become increasingly important in the next phase shaped by connectivity, regional trade, and logistics integration.

The state’s industrial renewal, therefore, need not be viewed merely as an attempt to recover a lost past. It may instead represent the emergence of a new eastern growth frontier — one where Bengal’s geography, connectivity, and regional linkages once again become central economic assets.

‍The views expressed do not necessarily reflect that of the authors’ organisation or the I4I Editorial Board. Views are personal.

Debt office overhaul overdue in low-income countries

‘Transparency is the cheapest credit enhancement a poor country can buy’


Restructuring gets the summits; debt management gets the training workshops. Yet in a low-income country, the debt office is crisis-prevention and early-warning infrastructure, not a narrow technical function – and a fundamental institutional reform is overdue.

All four G20 Common Framework applicants (Chad, Ethiopia, Ghana and Zambia) had passed through the International Monetary Fund and World Bank Heavily Indebted Poor Countries initiative, with relief between 2004 and 2015. Each returned to distress.

The prescriptions repeat after every round: consolidate, reform, sharpen the debt sustainability analysis and publish more. All necessary, but insufficient.  If distress keeps recurring under the same institutional design, the design is part of the diagnosis.

The missing reform has an address: the debt office – largely seen as the hinge between the fiscal and financial systems and the sole authority overseeing the consolidated perimeter, from the borrowing plan to guarantees. It did not cause the shocks, but every shock crossed its desk, becoming rollover risk, bank exposure and a late warning. Weak design then widens each passage.

Hence, the reform must be institutional: statute elevating the office, explicit guidance written for these countries and accountability for outcomes within five years. The evidence is drawn principally from African economies; the institutional structures are not.

The load on the hinge

A market-access debt manager is a price-taker in one continuous market; a low-income debt manager works two disconnected ones: abroad, an episodic window too fragile to anchor a financing strategy, and at home, where regulation, liquidity needs and scarce alternatives make sovereign paper the default asset and the banking system the sovereign’s captive marginal lender.

The sovereign-bank nexus is growing faster in sub-Saharan Africa than anywhere; in the West African Economic and Monetary Union, government debt is 43% of banks’ assets. Some 41% of new debt in low-income countries in 2025 was short-term. Ghana restructured in 2023 and transitioned to weekly Treasury bill auctions; by late 2025, its domestic market debt averaged below three months.

In much of Africa, the frontier is not optimising the curve but extending it beyond 90 days. The sovereign funds themselves through three channels: banks; non-bank pools, with over 80% of the continent’s $2.1tn in institutional capital sitting in government treasuries, and obligations that never reach an auction, including guarantees, state-enterprise borrowing, and arrears. Call it ‘a shadow deficit’. In Chad, the largest commercial loan (over 40% of the portfolio) was not recorded in the state’s recording system.

Any arrangement that encumbers future public resources belongs inside the perimeter, whatever its label. No one assembled the whole: domestic debt sat in fragments until the African Debt Database built the first harmonised picture in 2025, drawing on official sources that no one had joined.

Three tasks

What can be done? First, steward the sovereign balance sheet, not just the debt portfolio: manage liabilities against assets, align currencies with revenues, integrate cash with issuance, and project the shadow deficit as it accumulates rather than discovering it only when it has crystallised. This is the minimum condition for solvency management.

Second, build the investor base as the central policy variable. Shifting paper from captive banks to captive pension funds diversifies names, not risk, and what is needed are holders that price duration and absorb losses. Tanzania and Uganda have lengthened their curves. The route off the 90-day treadmill runs through the investor base, not around it.

Third, watch and warn. The Debt Sustainability Analysis is an annual photograph; the auction book is a live monitor, registering stress as it forms – in Ghana, one auction in five has gone under-subscribed since the 2023 restructuring. Yet no one is obliged to act on what it shows.

The debt office, therefore, warrants a statutory duty to warn, not merely an authority to borrow, built on three elements: protected reporting lines beyond the finance ministry to a legislature equipped to act on them, pre-committed distress indicators, and graduated disclosure. Pre-commitment converts warning from an act of courage into an act of compliance – early warning without early panic. Transparency is the cheapest credit enhancement a poor country can buy.

The call

While the three tasks define the function, the three deliverables below would implement it, ideally codified in a new set of public debt management guidelines for low-income countries.

  1. Statute: make the debt office an economic agent of the state, with its own objective, board, perimeter authority defined by economic substance, not instrument form, and a warning function no minister can silence. It confers operational independence and interagency parity, not policy autonomy; borrowing remains politically accountable.
  2. Framework: an explicit, distinct low-income debt-management framework, the global architecture’s missing chapter, that joins sustainability analysis, strategy, and diagnostics through a single perimeter, a single data layer, and a single escalation protocol. It would build on, not replace, real Fund, Bank, and partner capacity work through the Debt Management Performance Assessment, the Medium-Term Debt Strategy and the Low-Income Countries’ Debt Sustainability Framework, etc. The gap is not debt-issuance advice, recording systems or cost-risk practice; it is a country-owned operating map for the whole sovereign balance sheet: liabilities, guarantees, arrears, cash, bank exposure and warnings.
  3. Delivery: an architecture held to outcomes. The Fund, the Bank, UNCTAD, the Commonwealth, the Organisation for Economic Co-operation and Development, and regional agencies, as their own evaluators found, answering, with countries, to the scorecard below. To ‘we already do this’, the answer is one word: publish and explain. Training counts are inputs; a curve beyond 90 days is an outcome.
Figure 1. The five-year debt management integration scorecard
Dimension Core actions (sovereign-controlled, scored)
Balance sheet Consolidated balance sheet published annually; guarantees, arrears, collateralised obligations, and central bank advances inside the perimeter; shadow deficit projected; borrowing, cash and issuance plans reconciled
Macro-financial Sovereign-exposure dashboard published jointly by the debt office, the central bank and the regulator

System signal
Composite funding-stress indicator; statutory escalation ladder; record of warnings and plan adjustments
Meta Budget, DSA and debt bulletin reconcile to one dataset
Accountability Mandate in statute; regular reporting to parliament; committee review of guarantees and collateralised obligations.

Source: Author’s framework

Note: Floor (assumed, not scored): the metrics prescribed by existing international guidelines. Scoring is binary – published or not, enacted or not. Tracked separately as market diagnostics: holdings concentration; auction cover, tails and under-subscription; the shadow deficit’s size.

The next round of distress is being assembled now, auction by auction, in guarantees that no central ledger carries. The debt office did not cause every shock; it is where shocks become rollover risk and where the warning appears first.Two decades of relief and reform treated debt management as a capacity problem. In a low-income country, it is statecraft; the office must stand as an institution of the state, mandated, autonomous and accountable. Reforming it and holding the sovereign and parliament accountable for outcomes means the debt cycle finally has a circuit breaker.Udaibir Das is Vice Chair of OMFIF, Member of the Bretton Woods Committee, Distinguished Fellow at the Observer Research Foundation-America, Visiting Professor at the National Council of Applied Economic Research, and Senior Adviser of the International Forum for Sovereign Wealth Funds. Views are personal.

Dimension Core actions (sovereign-controlled, scored)
Balance sheet Consolidated balance sheet published annually; guarantees, arrears, collateralised obligations, and central bank advances inside the perimeter; shadow deficit projected; borrowing, cash and issuance plans reconciled
Macro-financial Sovereign-exposure dashboard published jointly by the debt office, the central bank and the regulator

System signal
Composite funding-stress indicator; statutory escalation ladder; record of warnings and plan adjustments
Meta Budget, DSA and debt bulletin reconcile to one dataset
Accountability Mandate in statute; regular reporting to parliament; committee review of guarantees and collateralised obligations.

Can India’s AI promise reach everyone?

Across India, conversations around Artificial Intelligence (AI) are steadily moving beyond innovation labs and corporate boardrooms into the domain of governance. The larger question is no longer whether governments will adopt AI, but whether these systems can genuinely improve public services in ways that are accessible, accountable, and inclusive. It is within the broader shift that Madhya Pradesh recently announced its phased AI Mission across government departments, becoming significant. More than a technological upgrade, the initiative reflects an attempt to explore how predictive systems could support decision-making, strengthen public delivery mechanisms, and respond more effectively to citizen needs.

The mission envisions AI not as a back-office efficiency tool but as a system that anticipates crop failures, flags health risks before they cascade, and helps MSMEs access credit they have historically been denied. If that promise is kept, it would represent something genuinely significant: the state using predictive intelligence to serve its citizens.

India’s ability to move toward AI-led governance is also being shaped by a digital ecosystem that has expanded rapidly over the last decade. The Digital Public Infrastructure stack with Aadhaar, UPI, ONDC, and the Account Aggregator framework is not merely an engineering achievement; it is a redistributive architecture that has extended formal financial identity to millions of previously excluded citizens. The National AI Mission builds on this base: as of late 2025, over 38,000 GPUs are available at subsidised rates, and AIKosh hosts more than 1,500 public datasets. This is, deliberately, not a market-led model, and that distinction matters because it positions digital infrastructure as a public utility rather than a purely commercial ecosystem.

The first generation of AI in Indian governance i.e., chatbots, automated grievance portals, and form-processing bots, was useful but modest. What is now being imagined is categorically different: Decision intelligence. AI systems can help officials simulate the effects of a price support scheme before it is announced, or identify districts most vulnerable to a monsoon shortfall weeks in advance. In agriculture, satellite-based predictive analytics could reduce the volatility that devastates smallholder incomes. In public health, integrating data from pharmacies, hospitals, and environmental sensors can enable pre-emptive surveillance rather than reactive crisis management; in education, finance, and logistics, AI similarly drives personalised learning, smarter credit assessment, and supply-chain optimisation.

With over 65% of India’s population under 35, the urgency is demographic as much as administrative. Private-sector decision-making already runs on real-time analytics; public policy still relies on lagged surveys. Closing that gap is not a luxury for a country whose young people need productive employment and functioning health systems in this decade, not the next.

None of this is without risk, and the risks fall hardest on those with the least power to contest them. Algorithms trained on skewed datasets reproduce and often amplify existing social hierarchies. An AI credit-scoring model that penalises women for interrupted employment histories, or a resource allocation tool that under-counts marginalised populations absent from formal records, does not represent neutral technology; it encodes discrimination at scale.

There are encouraging signs that lawmakers are responding. India’s AI Governance Guidelines, released in November 2025, anchor fairness and equity as core principles, with special emphasis on protecting marginalised communities. The Digital Personal Data Protection Rules, notified around the same time, bring 800 million internet users under a formal privacy framework for the first time. A Private Member’s Bill introduced in the Lok Sabha in December 2025 goes further, proposing mandatory bias audits, restrictions on AI in surveillance and employment screening, and statutory penalties. Not yet a law, but it considers accountability in the legislature.

The labour question cannot be deferred, particularly because AI is expected to displace routine tasks across the economy, and the effects will be uneven. Workers in low-wage, repetitive roles, overwhelmingly from marginalised backgrounds, are most exposed. A framework that invests in AI infrastructure without investing equally in reskilling, social protection, and equitable access to productivity gains would trade short-term efficiency for long-term fracture.

India’s AI Governance Guidelines need to consider a principle-based, techno-legal approach over a top-down regulatory regime, i.e., embedding accountability into system design rather than policing it after deployment. Proposed institutions like an AI Governance Group, a Technology and Policy Expert Committee, and an AI Safety Institute, are a positive way forward to the architecture. Algorithmic audits, impact assessments, and mandatory incident reporting need to be operationalised. Civil society and independent researchers need access to audit trails, not just regulators.

Crucially, none of this replaces human judgment. The most thoughtful AI deployments in governance position the technology as a support layer for officials, not a substitute for democratic deliberation. When a model flags a district as high-risk for malnutrition, a person still decides the response. The technology expands what is knowable; it cannot, and should not, determine what is done.

India’s choice is not between AI and no AI. It is between AI adopted thoughtfully, with benefits channelled through the same public infrastructure logic that animated Aadhaar and UPI, and AI that drifts toward serving those who already hold data, capital, and institutional voice. The Madhya Pradesh experiment, the November guidelines, the parliamentary debate on accountability: These are early chapters of a story still being written. In a fast-changing world, this transition is a necessity for optimising resource efficiency, improving public services, and staying ahead of mounting social and economic challenges. But it must be done with caution: With robust safeguards, inclusive design, and the citizen, not the algorithm, at the centre.

This article is authored by Chetana Chaudhuri, fellow, National Council of Applied Economic Research (NCAER), and Raj Kumar Banerjee, founder and managing director, Isourse Technologies. Views are personal.

Bengal’s chance to plant a new tree

In O. Henry’s The Last Leaf, ailing Johnsy clings to life because one painted leaf refuses to fall. Such is the power of optimism; it does not need to be certain to be effective. But for Bengal, the question is whether the leaf will hold long enough for a real spring to arrive. Inherited with an economy marked by industrial deceleration, capital flight and missed opportunities, the 2026-27 budget document of the newly elected West Bengal government reads less like a routine financial exercise and more like a declaration of intent.

Despite operating under a heavy debt burden of Rs.8.15 lakh crore and substantial committed liabilities on pensions and payments for interest, total proposed expenditure is elevated by nearly 7 per cent over the previous year’s revised estimates. This pace of expansion is not merely managing a decline, but probably betting on revival. There is a sense of urgency running through the Bengal budget’s industrial vision, and perhaps that urgency is reasonable. From roughly 6 per cent in 2011-12, the state’s share of national real GDP has slipped to around 4.9 per cent today, a decline that has accumulated into an estimated loss of Rs 14.12 lakh crore in production over fifteen years.

The state’s GDP growth has trailed the national growth trajectory almost consistently during this phase (see inset chart). Our ongoing projections suggest that the stakes are even higher than they appear today. When viewed against India’s longer-term ambitions of a USD 30 trillion economy by 2047 under the Viksit Bharat vision, the implications for Bengal are more staggering. If Bengal’s share of India’s GDP merely stabilises at its current level instead of recovering to where it stood in 2011-12, the state will forgo more than Rs 51.26 lakh crore of cumulative production by 2047.

This gigantic amount is not the cost of economic contraction; it is the price of settling for a smaller share of a much larger Indian economy. As India grows, simply standing still means falling further behind. However, to its credit, the 2026 state budget appears to have recognised the direction in which the global economy is moving. The proposed Rs 5,000-crore industrial incentive framework that connects the Central Government’s integrated East Coast Industrial Corridor node at Durgapur, together with the state’s intention to develop a semiconductor manufacturing hub in the Panagarh-Durgapur belt, signals an ambition to compete in industries that will increasingly shape India’s next phase of economic growth. Nevertheless, the Durgapur semiconductor proposal is emblematic of both the opportunity and the peril.

A semiconductor hub in Durgapur should not be imagined merely as a plant that manufactures chips. It should be conceived as the anchor of an entire clean industrial ecosystem: renewable power procurement, treated water recycling systems, zero-liquiddischarge norms, energy-efficient buildings, high-end skill centres, waste treatment facilities, multimodal logistics and a vendor network designed around low-carbon standards from the outset. Dholera in Gujarat offers a useful reality check for an understanding of whereWest Bengal is now seeking to enter. 

Dholera already has a clearer investor anchor, a defined fabrication partnership and a semiconductor policy environment aligned with broader manufacturing strategy. Tata Electronics, in partnership with Taiwan’s PSMC, is developing the Dholera fab with an investment ofRs 91,000 crore, a planned capacity of 50,000 wafers per month, and chip production across nodes ranging from 28 nm to 110 nm. Construction formally began in March 2024, and the project sits within a larger national semiconductor mission that combines central incentives, industrial planning and ecosystem building. It would be a tragedy if, in trying to recover lost time, Bengal embraces an old school model of industrialization just when the rest of the world is quietly leaving this behind.

After decades of under- industrialisation, the pressure on the state’s economy to industrialise quickly also increases a bigger risk of becoming a mis-industrialised state. The pressure to attract investment, generate employment and revive manufacturing can easily turn the state into a willingness to compromise on financial viability, environmental safeguards, supply chain prudence, land-use planning or resource management. History suggests that such shortcuts often become expensive detours. There is, however, a rare scope hidden in Bengal’s delayed industrial journey.

Because the state did not witness the manufacturing boom experienced by several western and southern Indian states, it is not locked into a new generation of carbon-intensive industries. The semiconductor announcement suggests that Bengal has the opportunity to bypass the dirtiest phase of industrialisation altogether. Whether it succeeds will depend on the choices made long before the first chip leaves the factory. If Bengal hopes to attract investment into the industries shaping the next generation of global manufacturing, semiconductors, green hydrogen, advanced electronics and clean mobility, it must recognise that competitiveness is no longer defined by cost alone.

In an era of resilient supply chains and tighter sustainability standards, environmental governance is not a compliance burden but part of the state’s competitive infrastructure. At the same time, these are among the world’s most capital-intensive and institutionally demanding industries, requiring technological sophistication, efficient resource management and long-term policy credibility. If Durgapur is to emerge as a credible semiconductor destination, today’s announcements must therefore evolve into an industrial strategy equal to the ambition of the sector itself.

Durgapur has the chance to learn from a first mover, Dholera, without being trapped by first-generation mistakes. The questions are hard and must be asked now, not later. What exact segment of the semiconductor value chain is Durgapur targeting? What water infrastructure will support such facilities? What renewable power sourcing mechanisms will be built into the industrial node? How quickly can technical universities and ITIs in the Asansol-Durgapur belt be aligned to semiconductor manufacturing skill needs?

How will land aggregation be handled without reproducing Bengal’s old political scars around industrial acquisition? These are not administrative details to be addressed later. They are the project itself. If Bengal gets these foundations right, Durgapur could become more than a semiconductor destination, it could become the blueprint for the state’s industrial renaissance. If it gets them wrong, the announcement will remain just that: an announcement.

The writers are, respectively, a Fellow and a Research Analyst at the National Council of Applied Economic Research (NCAER), New Delhi. Views are personal.

India’s Paperless Border Paradox: Evidence from Empirical Estimations

A nation’s efficient participation in global supply chains and accelerated economic growth are driven by trade facilitation. Paperless trade has been a significant reform under the WTO’s Trade Facilitation Agreement. Quantifying its potential efficiency in global trade dynamics is essential for informed policy. Therefore, this study undertakes an empirical estimation from India’s perspective to understand how the paperless and cross-border paperless reforms have enhanced its efficiency in countries’ export–import movements over its other major trading partners. Central to the paper’s argument, the study reveals a paradox in paperless-border realities. While this paper captures the positive implications of the reforms, it also highlights the key challenges that hinder the seamless movement of cargo across borders. This study also identifies bottlenecks and highlights an asymmetric pattern of efficiency gains for India, depending on the size of its partner countries’ economies. Therefore, strengthening cross-border interoperability and digital and physical infrastructure is essential to ensure that India’s paperless trade reforms translate into faster, cheaper, and more reliable trade flows with key partners.

    Get updates from NCAER