GST 2.0: A reform that has gone much deeper than expected

To the GST Council’s credit, it went beyond the elimination of two rate slabs and delved into fine details to fix structural anomalies in this tax regimes. It broad-bases rates for like goods, corrects inverted duties and clusters products by their end use.

The Goods and Services Tax (GST) Council has finally spoken its mind about the GST 2.0 package of reforms mooted by the Centre and earlier adopted by the Group of Ministers (GoM) tasked with the work of rate rationalization.

Going by reports, the discussions were full-throated and the endorsement unanimous. The council deserves plaudits for not dithering in blessing such a comprehensive reform agenda with far-reaching effects, despite concerns about a likely ‘loss’ of revenue. Looked at closely, the agenda reflects the work of not one, but three GoMs, the other two being on the compensation cess and on life as well as health insurance.

This decision has been hailed by stakeholders and commentators with equal enthusiasm for good reason. At the outset, the relief offered by way of rate cuts is deeper and much more extensive than expected. The exercise has not been confined to the mere abolition of two rate slabs—12% and 28%—and the re-slotting of those goods and services in the 5% or 18% slabs. Goods and services have also been shifted from the 18% slab to 5% where necessary.

In the realm of indirect taxes, changing the categorization of individual goods or services from one rate slab to another is usually frowned upon as arbitrary. This is far from it. What has been attempted in this instance has three very clear policy underpinnings.

The most important one is the revision’s broad-banding of rates on substitute or similar goods, or goods of the same class, so that classification disputes are minimized. A case in point is food products, where several such disputes had arisen in the past owing to rate arbitrage. Now, all processed foods (barring aerated waters), including an omnibus category of foods not specified elsewhere, are clubbed at a common rate of 5%, setting at rest the scope for any future controversy.

The second imperative that has driven this rejig is the removal of inverted tax rates. By moving specified goods from the 18% to 5% slab, long-standing inversions have been fixed for man-made textiles, tractors and fertilizers, apart from leather footwear and other products. Unless we transition to a single rate structure, some rate inversions are inevitable.

The package proposes a revamp of the refund process, so that 90% of the refund of accumulated input tax credit (ITC) due (on account of rate inversions) may be refunded in an automated and time-bound manner, subject to risk-assessment. This would unlock working capital and improve the competitiveness of industry.

The third consideration that has informed such shifts is the clustering of products by their end- use to provide tax relief to certain sectors or items of mass consumption. Examples of these are tractors, agricultural machinery, fertilizers and bio-fertilizers, educational materials, personal care and personal healthcare products, ready-made garments and footwear (up to a certain value threshold) and renewables, including electric vehicles. Similar is the case with the review of items being charged 28%.

Goods that can be categorized as ‘aspirational’—like small cars, air conditioners, dishwashers and large TVs—have all been clubbed at a common rate of 18%. Barring full exemption for a few goods, the rate cuts are deep, with burdens going down in a range from 36% to 72%. Thus, the relief for consumers is substantial and very likely to stimulate both aggregate demand and growth in the short to medium term. That is why Prime Minister Narendra Modi described it as a Diwali bonanza and its capacity to boost consumption has become its unique selling point.

This meticulous attention to detail in calibrating GST rates with clear objectives and a broad purpose is perhaps unprecedented. The spin-off is that the resultant structure automatically acquires durability and would not need to be tinkered with for a while.

Among the three pillars of the Prime Minister’s package, the structural pillar referred to the need to impart stability. This has been achieved. As such, a second-order effect of these changes would be the boost they provide private investments, which are motivated to a large extent by certainty and stability.

It is heartening that the list of “demerit goods” or “sin goods” has been confined to tobacco and tobacco products, aerated beverages (given their high sugar content and attendant health risks) and some categories of automobiles (that have the ability to bear a higher incidence of tax). The council has also abjured the temptation of retaining the tax burden on these products at the current level (inclusive of cess) and confined them to the statutorily prescribed 40% rate. Since the rates are ad valorem, evasion-prone tobacco and tobacco products will attract tax on their retail sale price instead of today’s compounded levy. This is a neat and foolproof approach that takes minimal regulatory oversight.

With these changes and process reforms for registration, refunds and return filing, a major portion of our reform objectives has been accomplished. Some legislation-related issues, such as those related to ‘intermediary services,’ have also been resolved. The council’s attention should shift next to other legislative ambiguities, cleaning up the plumbing for ITC flows, introducing joint or coordinated audits and investing in the training of officers for dispute settlement—best done in mission mode.

The author is former chairman, Central Board of Indirect Taxes and Customs, and senior advisor, KPMG and NCAER. These are the author’s personal views.
Why macrofinancial surveillance fails when it matters most

The political economy of fiscal and financial blind spots.

Financial surveillance fails when it matters most. Every major financial disruption – from the 1997 Asian crisis to the 2008 financial crisis or recent geopolitical shocks from wars, sanctions and trade realignments – has exposed how blind spots persist in national systems, regional arrangements and global oversight.

Macrofinancial surveillance – specifically monitoring the interconnections between the financial system and the broader macroeconomy (fiscal, monetary, real economy linkages) – consistently breaks down despite massive institutional investment. Most economies operate for years without systematic macrofinancial evaluation, particularly when risks are accelerating. Crucially, no country has developed a comprehensive system to monitor fiscal-financial-real economy interactions systematically – existing frameworks focus on financial stability within the financial sector, rather than on cross-sectoral linkages.

The mismatch is stark. The International Monetary Fund conducts comprehensive assessments every five to 10 years for systemically important countries, over a decade for others. Financial Stability Board peer reviews are narrower, targeting standards compliance rather than system-wide dynamics. Basel Committee assessments follow separate timelines entirely. The IMF’s 2021 review found these cycles poorly coordinated.

The problem is not technical incapacity but political economy. Fiscal fragility, bureaucratic incentives, sovereignty concerns and collective action failures make fragmentation rational, even when it is systemically disastrous.

The fiscal surveillance trap

Surveillance matters most when private losses are reflected on public balance sheets. Ireland’s 2008 blanket banking guarantee transformed manageable sectoral problems into an €85bn sovereign crisis because the government underestimated the scale of banking sector losses and their fiscal implications.

This is the ‘fiscal surveillance trap’. Governments need comprehensive assessments to manage contingent liabilities but publishing them can trigger market reactions that crystallise those existing liabilities. Türkiye’s 2018 IMF consultation showed how detailed warnings about external financing risks preceded an acceleration in portfolio outflows.

The trap hits developing economies hardest. Organisation of Economic Cooperation and Development data show that advanced economies maintain fiscal buffers averaging 15-20% of gross domestic product, while developing economies average just 3-5%. When confidence falters, richer countries absorb volatility while poorer ones slide into debt crises. This fiscal arithmetic deepens political obstacles, making fragmentation the equilibrium response.

Why surveillance fragments domestically

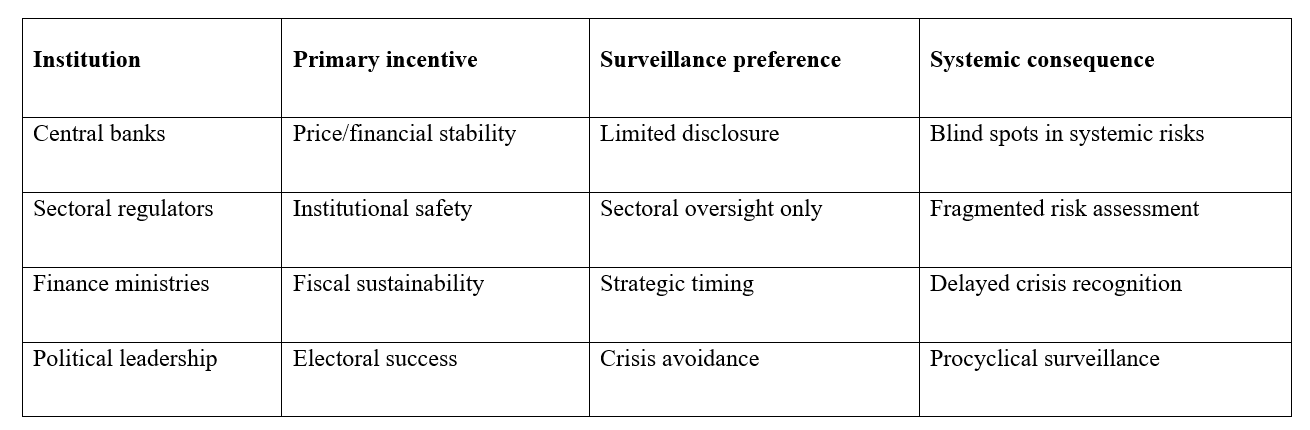
Three forces sustain this equilibrium. First, bureaucratic empire-building leads agencies to resist coordination that threatens autonomy. Second, regulatory capture allows financial institutions to prefer narrow regimes they can influence over system-wide transparency. Third, political myopia encourages governments to avoid disclosures that may destabilise markets during electoral cycles.

Deeper architectural problems compound these coordination failures. Existing regulatory frameworks assume clear boundaries between sectors – banking regulation for banks, fiscal policy for governments, monetary policy for central banks. Yet modern economies feature deep interconnections that cross these institutional boundaries, while surveillance remains siloed. Central bank independence, once designed to insulate monetary policy, now creates coordination gaps precisely when systemic risks span multiple mandates.

These forces create what economist Douglass North calls ‘institutional persistence’. Bad arrangements endure because incumbents bear the costs of change, while benefits are diffused. Each institution optimises locally while system-wide risks accumulate unseen.

Figure 1. How institutions fragment surveillance

Analysis from institutional incentive literature and surveillance practice observations

Central banks adapt by embracing deliberate ambiguity. Reports use phrases like ‘elevated vulnerabilities’ to convey risks without naming institutions. While rational, this undermines effectiveness as vague warnings rarely spur policy change. Surveillance becomes ‘performative’ – outwardly demonstrating diligence while avoiding impact. The more surveillance is needed, the less transparency is possible.

The global collective action failure

The same logic plays out internationally. Everyone benefits from robust surveillance, but each country has incentives to conceal vulnerabilities while enjoying others’ transparency – creating asymmetry.

When the Federal Reserve publishes stress tests, markets view it as prudential strength because the US can absorb shocks. When Nigeria’s central bank disclosed vulnerabilities in 2019, the result was capital flight and currency depreciation. Advanced economies internalise disclosure costs while developing economies face net costs.

Where blind spots matter most

The consequences are starkest where macrofinancially significant innovations outpace regulatory frameworks. India’s United Payments Interface processed ₹139tn in 2023 – transactions that affect monetary velocity but fall outside traditional banking supervision. Brazil’s digital real pilot blurs fiscal and monetary boundaries in ways current frameworks cannot address.

Climate shocks exacerbate the problem by simultaneously affecting all three macrofinancial dimensions. Pakistan’s 2022 floods drove banking defaults, infrastructure losses and fiscal emergency spending – yet no surveillance framework monitors how environmental shocks propagate across fiscal-financial-real economy linkages.

What does an effective design look like?

Breaking the fiscal surveillance trap requires recognising that some solutions can help countries escape the trap entirely, while others must work within its constraints.

Escaping the trap becomes possible when disclosure costs are reduced or shared. Industry co-financing – making financial institutions contribute to surveillance costs proportional to systemic risks they generate – aligns private incentives with public monitoring needs. Regional compacts like the Asean+3 Macroeconomic Research Office can share surveillance capacity across neighbouring economies, pooling resources while reducing individual country exposure to market reactions.

Working within the trap requires accepting that full transparency may be impossible but systematic monitoring can still occur. The most promising structural reform involves fiscal-financial integration that embeds macrofinancial analysis within existing institutional mandates. The UK’s Office for Budget Responsibility demonstrates how combining fiscal projections with financial stability assessments creates comprehensive monitoring without requiring new disclosure frameworks that might trigger market reactions.

The path forward

No consistent global mechanism exists to judge whether surveillance is effective in practice. The costs of macrofinancial surveillance failure are mounting – the IMF projects global debt exceeding $100tn in 2024, with risks heavily tilted upward such that debt could reach 115% of GDP in adverse scenarios. High macroeconomic uncertainty now threatens to amplify downside risks by 1.2 percentage points of growth, turning modest expansion into contraction when surveillance blind spots intersect with elevated debt vulnerabilities. Without systematic monitoring, debates about the future of finance remain academic.

Economist Friedrich Hayek warned that ‘The curious task of economics is to demonstrate to men how little they really know about what they imagine they can design.’ Policy-makers imagine they can design stability by managing pieces in isolation, yet systemic risks emerge from the fiscal-financial whole. The choice is stark: build surveillance that confronts political realities or face breakdowns that will prove far costlier than systematic monitoring.

Udaibir Das is a Visiting Professor at the National Council of Applied Economic Research, Senior Non-Resident Adviser at the Bank of England, Senior Adviser of the International Forum for Sovereign Wealth Funds, and Distinguished Fellow at the Observer Research Foundation America. Views are personal.

Dealing with after-effects of reform

A critical part of the package are the process reforms for simplifying registrations and expediting refunds, both for inverted duty structure and exports.

The run-up to the 56th Goods and Services Tax (GST) Council meeting was full of mixed sentiments—lots of excitement about the broad-brush picture of GST 2.0 reform and yet some lurking apprehension about the likely fine print. There was some relief when the Group of Ministers approved the Centre’s proposal on August 21. Given that some of the states had been expressing concerns about the revenue implications of the proposal and their pitch for seeking compensation, there was nervousness about which way the proposals would go in the GST Council when it met on September 3 and 4. Questions like whether the Council would reverse some of the proposed changes to accommodate these concerns or even defer it till a more acceptable alternative emerges were quite figural.

Belying these apprehensions, the Council has exhibited statesmanship in fully endorsing what was inherently a sound and irresistible proposal promising meaningful simplification in the rate structure and real relief in tax burden to all constituencies that matter for providing either a consumption or growth impetus to the economy. The Council has been sagacious enough both to recognise its merit as well as the need for its immediate adoption—implicitly parking revenue concerns till the proposal has played itself out in the economy. In the press briefing, the revenue secretary also chose not to characterise the revenue implications of the proposal (estimated to be about Rs 48,000 crore by the government) as a “loss” owing to the positive impact the rate cuts would have on consumption and demand, thereby providing adequate buoyancy to collections.

The package has received widespread support and acclaim from stakeholders. It has focused not just on abolition of the 12% and 28% rate slabs and refitting those goods and services into either 5% or 18% (putting in place a two-tier rate structure), but also on removing several inversions in duty by migrating goods from the 18% slab to 5%. A case in point being tractors, textiles, fertilisers, and so on. Of course, the thrust has been on providing relief to a large swathe of mass consumption items such as processed foods, apparel and footwear, personal care and healthcare products, life-saving drugs, educational material, bicycles, and life and health insurance.

As promised, the rate has been lowered on many aspirational goods too, such as small cars, motorcycles, air conditioners, dishwashers, and large televisions. Then, there are sector-specific reductions for agricultural goods and farm equipment, renewable energy products, and defence. Rate changes have been complemented by process reforms for registration, and refunds where technology would be used to eliminate human intervention and ensure time-bound delivery. Together, these make a very wholesome package minimising future disputes owing to misclassification and easing day-to-day existence.

Now, the focus must shift to implementation starting September 22 when the rate changes take effect. There are challenges that businesses face. The first, which is to tweak their ERP (enterprise resource planning) systems to reflect the rate changes, should not pose a problem as they have been given a lead time of more than two weeks. Then, they have to adroitly manage the movement of inventory so that there are adequate stocks available at different stages in the distribution chain to service heightened demand during the upcoming festival season.

At the same time, in a situation of rate reduction, if they are loaded with high inventory before September 22, distributors would accumulate surplus input tax credit (and blocked working capital) without the possibility of liquidation when they resell at lower rates of tax. A fine balancing act would thus be needed. Third, prices of products whose GST rate has undergone a change need to be reset. The key question in everyone’s mind is whether these large-scale benefits would actually be passed on to the consumer or cornered by businesses, thereby thwarting the very purpose for which they are proposed.

Until some time back, it would have been possible to enforce this through anti-profiteering provisions in the GST law (Section 171) and the attendant administrative machinery for investigating complaints of profiteering and adjudicating them. While the substantive provision subsists on the statute book, the administrative machinery for implementation has already been deactivated. The Council has chosen not to revive it and to trust businesses to comply voluntarily. The unresolved issue is whether these provisions would still be enforceable by GST authorities as part of compliance verification and, if so, in what manner. A suitable clarification from the Council would help.

There are implementation issues for the government too. A critical part of the package are the process reforms for simplifying registrations and expediting refunds (both for inverted duty structure and exports). The industry awaits this with lot of anticipation. The legal framework, information technology infrastructure, business processes, and standard operating procedures for these would have been designed already. The challenge for the government would be to ensure that the system of risk-based selection is robust and dynamic so that the selection is well-targeted. Trade’s experience with identification of risky exporters in the past and the weeding out of false positives was not a happy one. The new system should be responsive and nimble in reviewing its selection lest history repeat itself.

Vivek Johri, Former chairman, Central Board of Indirect Taxes and Customs, and senior adviser, KPMG and National Council of Applied Economic Research. Views are personal.

India’s renewable energy push calls for smarter state budgets

Uneven state spending and neglect of infrastructure threaten India’s renewable energy targets despite ambitious national pledges.

No country can scale renewable energy without robust infrastructure. Solar and wind power are variable, location-specific, and often generated far from consumption centres. Dedicated transmission corridors are needed to evacuate this power efficiently and reduce curtailments. Upgraded distribution systems and smart grids must manage intermittency, balance demand in real time, and enable two-way flows in decentralised systems such as rooftop solar.

Storage infrastructure—batteries, pumped hydro, and green hydrogen—provides grid stability during periods of low generation. At the local level, rural mini-grids and solar pumps support decentralised solutions. On the supply side, investments in domestic manufacturing of panels, turbines, and related equipment reduce import dependence. Institutional support, from forecasting tools to power exchanges and market mechanisms, makes renewable operations more efficient. Infrastructure, in short, is the backbone of India’s clean energy transition.

India’s ambitious targets and the reality gap

India’s rising energy demand, driven by urbanisation, industrialisation, and higher living standards, makes a transition to low-carbon systems imperative. The country has pledged net-zero by 2070 and a 500 GW non-fossil capacity by 2030. As of January 2025, renewable energy accounted for 46% of installed capacity, but just 22–24% of actual generation—evidence of intermittency, grid bottlenecks, and underutilisation.

The problem is uneven across states. Some regions with vast potential have failed to grow capacity, largely because of inadequate investment in renewable infrastructure.

State budgets and skewed priorities

A few states—Chhattisgarh, Jharkhand, Gujarat, Haryana, Maharashtra, and Uttar Pradesh—have prioritised renewable energy in their budgets. But most continue to spend disproportionately on revenue expenditure rather than capital investment.

Capital expenditure builds long-term assets—solar parks, transmission networks, storage facilities—while revenue expenditure covers salaries, operations, and subsidies. States that neglect capital formation risk stagnation, since infrastructure, not subsidies, determines future capacity.

State finances are central to India’s clean energy transition. With limited fiscal space and rising demands on welfare, subsidies, and infrastructure, many states struggle to prioritise renewable investments. Their dependence on central transfers and borrowings often leaves little room for capital spending on grids, storage, and manufacturing. Unless states improve fiscal management and reorient budgets toward long-term assets, the imbalance between revenue expenditure and capital formation will persist, slowing India’s march toward its clean energy targets.

Capital spending: The exception, not the rule

The contrast is stark. Chhattisgarh and Gujarat allocated 89% and 81% of their renbewable energy budgets, respectively, to infrastructure. Their approach shows a commitment to building lasting capacity.

By contrast, Haryana, Maharashtra, and Jharkhand devoted virtually their entire renewable budgets to subsidies and operations, leaving nothing for infrastructure. Uttar Pradesh spent 94% on revenue items. Even states with significant potential, such as Maharashtra and Haryana, report low installed capacity—underscoring the consequences of neglecting capital expenditure.

Towards a balanced fiscal strategy

Sustainable growth demands a more balanced allocation between capital and revenue. States must gradually raise capital expenditure shares by 15–20% annually over three to five years. This phased approach would preserve ongoing operations while steadily expanding infrastructure.

Public-private partnerships can help bridge funding gaps, as Gujarat and Chhattisgarh have demonstrated. To succeed, states will need flexible targets, regular progress reviews, financial innovation, and regulatory clarity. Capacity-building support for state agencies will also be essential.

India’s renewable energy journey is at a crossroads. Meeting ambitious national targets will require more than headline announcements of capacity expansion. Without systematic reforms in state-level spending, grid modernisation, and manufacturing, installed capacity will remain underutilised and generation targets unmet.

States that shift from subsidies to infrastructure, from short-term relief to long-term investment, will drive the next phase of India’s energy transition. Others risk falling behind, weakening the country’s collective march towards its clean energy goals.

Chetana Chaudhuri is Fellow, and Subrata Sekhar Rath Consultant at the National Council of Applied Economic Research (NCAER), New Delhi. Views are personal.

NCAER News: August 2025

NCAER News is a monthly digest where you can learn about NCAER’s research outputs, its latest events, and offerings.

    Get updates from NCAER