GST reform: Grab this chance to make it bold and beautiful

India’s goods and services tax (GST) is set for an overhaul by Diwali this year. With so much hope pinned on this reform, we must get every detail of the regime right. Here’s a look at some key issues that must be addressed by the GST Council. 

Indian Prime Minister Narendra Modi’s announcement on Independence Day about launching the next phase of goods and services tax (GST) reforms by Diwali this year adds tremendous heft and seriousness to this long-awaited policy change. There is a lot to be said about its timeliness too—with global headwinds in the wake of US tariff tantrums having dampened sentiment considerably in India’s manufacturing and export sectors.

The package not only clearly articulates the Centre’s vision of a reformed GST, but also pushes all the right buttons: we can expect a neater, less dispute-prone and stable rate structure; correction of rate-structure inversions; ease of living for businesses, with the streamlining of three key business processes of registration, return filing and refunds; a reduction in tax incidence for a wide array of constituencies ranging from students and women to the middle-class and farmers, with the burden eased on items of mass consumption as well as ‘aspirational’ goods.

The package on its way also acknowledges the need for stability in the rate structure, which is music to the ears of change-fatigued stakeholders.

In many ways, the level of ambition goes far beyond what was expected. First, what has been figural so far is mainly rate rationalization and the fate of the GST compensation cess. The current proposal, however, also goes into the administrative realm to address day-to-day pain points for businesses. It seeks to improve the mechanism for registration, return filing and refunds through greater use of technology.

Second, the expectation was that the four- rate structure of 5%, 12%, 18% and 28% slabs would be compressed to three. What is proposed now is a reduction to only two: reportedly, a standard rate of 18% and a merit rate of 5%, with a special rate of 40% only for a “select few” items that qualify as demerit or sin goods. Hopefully, this would be accompanied by broad banding goods of the same class under a uniform rate slab, so that classification disputes are minimized. Food products are a case in point.

Third, the proposed cuts are not only extensive in coverage but also deep.

But this is the Centre’s vision. For it to morph into reality, Indian states need to endorse it as and when the GST Council meets. According to reports, the group of ministers (GoM) on GST has already endorsed it. Judged by the yardstick of canons of taxation as well as mass appeal, the package is too attractive to be dismissed outright. Overall, at the national level, the proposal also seems to be revenue balanced or only marginally revenue negative, with the promise of losses expected to be neutralized in due course, thanks to its positive impact on retail prices and consumption.

It could be argued that some net revenue loss in the short-run is a small price to pay for such a simplified GST structure. In the absence of granular data on their respective consumption patterns and the balance between their imports from and export to others, it is not possible to compute the revenue implications for individual states.

Moreover, the GoM’s recommendations on the compensation cess remain unknown. The Centre appears to be of the view that the cess should go. Current Constitutional provisions do not allow GST-related cesses to be levied in any form. Given this background, it is legitimate for states—particularly those that foresee their revenues being impacted adversely—to seek some revenue-saving adjustments.

There are several possible ways in which these adjustments could be made. For instance, the current incidence (inclusive of compensation cess) on some ‘sin goods’ is much higher than 40% (the peak statutory rate of GST). This could be maintained through a suitable amendment of the GST law. Alternatively, the levy on tobacco products in excess of 40% could be loaded onto Central excise duty, which is also part of the divisible pool for revenue and would therefore reach state coffers too.

The list of items moving from 28% to 40% could include some ‘luxury goods’ in addition to demerit or sin goods. Likewise, some more items could migrate from 12% to 18% instead of going down to 5%. Another possible approach could be to phase in the reductions based on a pre-announced glide path, so that the drop in revenue is gradual.

While the proposed rate rationalization would receive a positive response both from industry and consumers, there are a few linked issues that need to be addressed for the transition to be painless. The ease of living pillar of the package already contains a reference to ironing out the GST refund process. If most items at 12% migrate to the lower rate of 5%, refunds arising from inverted rates would clearly increase under the new structure. It would impact pharmaceutical products, fertilizers and tractors, among others. Unless the refund mechanism for accumulated input tax credits is robust, timely and smooth, this would imply working capital being blocked for prolonged periods in such sectors.

Among the other major concerns that businesses have are whether and in what form the mechanism for implementation of anti-profiteering provisions would be reinstated, and whether they would have sufficient lead time to tweak their enterprise resource planning systems in the midst of the busy festival season. Hopefully, the GST Council will address these issues when it meets in September.

These are the author’s personal views. The author is senior advisor, KPMG and ex-chairman, central board of indirect taxes and customs.
India Human Development Survey: August 2025

The IHDS Forum is a monthly update of socio-economic developments in India by the IHDS research community, based on the India Human Development Survey, jointly conducted by NCAER and the University of Maryland. While two earlier rounds of the survey were completed in 2004-05 and 2011-12, respectively. Fieldwork for the third round was undertaken in 2022-24 and the data is currently being cleaned and processed.

Click here for previous issues

India’s vocational training system needs to reinvent itself to boost employability

Investing in robust public–private partnerships to deliver VET (Vocational Education and Training) is critical for successful skilling.

With a volatile external sector increasing the challenge of demand-driven growth, the Prime Minister unveiled a slew of proposed reforms from the Red Fort’s ramparts on August 15. While a recalibration of GST could induce higher domestic consumption and spur domestic investment with employment growth, India must seize this opportunity to also rethink its education system and increase the productivity and employability of its labour force. Our traditional education system — academic and rote-based — is unlikely to deliver a workforce equipped for the future of work.

In India and across the world, formal vocational or skill training is associated with higher chances of an individual being employed and obtaining a job in the formal sector. Yet, only 4 per cent of India’s workforce is formally trained, even though the institutional coverage of the Vocational Education and Training (VET) system is extensive — with over 14,000 Industrial Training Institutes (ITIs) and 25 lakh sanctioned seats. Actual enrolment was only around 12 lakh in 2022, implying just 48 per cent seat utilisation. Our VET system struggles with not only low uptake but also modest employment rates for those who undergo training. In 2018, the employment rate among ITI graduates was 63 per cent, whereas countries with robust VET systems such as Germany, Singapore, and Canada reported employment rates ranging between 80 and 90 per cent. These statistics point to a VET system that is both ineffective and unattractive to our youth.

The first factor is the stage of the education system at which VET is integrated. Countries that introduce VET earlier in the schooling system show a stronger association with better labour market outcomes. In Germany, for example, VET is integrated at the upper secondary level through a dual system, combining school education with paid apprenticeships. In contrast, in India, VET is an afterthought — offered post high-school education, which not only shortens the period available for hands-on training before the youth enter the job market, but also does not allow for orientation towards employable skills.

A second aspect is the absence of a defined pathway to higher (or academic) education via vocational skilling. For instance, Singapore offers VET either as technical education at the post-secondary level or via polytechnics at the tertiary level through dual vocational tracks, but has defined pathways from VET to traditional university education. India, in contrast, offers no formal academic progression from VET to mainstream higher education, nor does our education system offer credit transfers between systems. This reduces the uptake of VET by many who wish to keep the option of traditional, academic education viable.

Third, and possibly most important, is the perception and quality of VET in India. Singapore has industry-led curriculum design, high instructor quality, regular audits and a mechanism that seeks constant feedback from employers and trainees. Singapore also has a Skill Future Programme, where the government offers subsidies to upskill throughout one’s career. In India, in contrast, many courses are outdated and misaligned with industry needs. Over one-third of ITI instructor posts are vacant due to limited training capacity at National Skill Training Institutes. Quality monitoring is weak, with irregular ITI grading and no feedback systems.

Relatedly, investing in robust public–private partnerships to deliver VET is critical for successful skilling. In Germany, Singapore, and Canada, governments fund VET institutions, while employers pay for apprenticeships, share training costs, and also help design curricula. In India, the engagement of employers in the private sector is limited, if not absent. ITIs depend heavily on government funding, with minimal private sector investment in infrastructure and training apparatus. Medium and Small Scale Enterprises drive local job creation, but have low engagement with ITIs due to capacity constraints. Sector Skill Councils, which play a key role in integrating training with industry needs, lack state-level presence.

What can India learn from international experiences to overhaul its VET programme?

First, integrate VET into early schooling. The National Education Policy (NEP), 2020 recommends such integration, but progress has been slow. Second, fast-track reforms to implement the National Credit Framework that defines clear progression pathways and aims to have a board for nationally recognised certifications. Third, to improve training quality, align VET courses with local industry demand through regular market assessments, expand NSTIs and fast-track instructor recruitment to address capacity gaps, and strengthen ITI grading by incorporating trainee feedback. Fourth, scale models like the Private Training Partner approach by leveraging public infrastructure and private expertise. Involve MSMEs, and strategically use CSR funding to boost industry relevance. Fifth, increase public spending on VET and ensure the financial viability of institutions by linking public funding to their performance and granting them autonomy to generate their own revenue.

We must invest more in human capital. India allocates around 3 per cent of total education expenditure to VET, compared to 10-13 per cent in countries like Germany, Singapore, and Canada. Public funding can be optimised with improved financial viability of ITIs through lower per-student costs of training and by allowing ITIs autonomy to generate their own revenue.

Recent government schemes — such as the Employment Linked Incentive (ELI) scheme, the PM Internship Scheme, and the ITI Upgradation Initiative — reflect an increased focus on employment outcomes. ELI Part A offers up to Rs 15,000 for first-time EPFO-registered workers, while the revised ELI, Part B gives employers Rs 3,000 a month for every new hire. Both ELI schemes push formalisation of jobs but have no skilling components. The Prime Minister Internship Scheme aims to provide one-year placements to youth in top companies, but lacks pathways to permanent jobs. The ITI Upgradation Scheme focuses on modernising 1,000 government ITIs in partnership with industry, but not necessarily the quality of training.

Policy initiatives, thus far, have either tinkered on the margins of our existing education system or are afterthoughts. They are unlikely to transform the level of productivity and employability of our workforce unless we overhaul a system that is becoming increasingly outdated. Such an overhaul is crucial for making vocational training a pathway to jobs — an essential step towards a Viksit Bharat.

Afridi is professor of Economics, ISI (Delhi) and visiting professor, NCAER. Chandna is associate fellow, NCAER. Views are personal.

Gender justice beyond India’s north-south divide

Some northern states break gender development patterns, while new challenges emerge in the South

India’s performance in SDG 5 (Gender Equality and Women Empowerment) remains a significant challenge, as highlighted in NITI Aayog’s 2023-24 report, where it is the only SDG India is an aspirant. In as many as 13 SDGs, it is a ‘forerunner’. This reality is further underscored by the World Economic Forum’s 2025 Gender Gap Report, which ranked India 131 out of 148 countries, behind several South Asian nations such as Bangladesh, Bhutan, and Nepal. Key areas of concern include sex ratio at birth, spousal violence, land ownership by women, wage disparity, workplace representation, and women’s autonomy. Continued commitment from all stakeholders is crucial to address these disparities.

The north-south divide in gender development is a long-standing narrative in India, with southern states such as Kerala, Tamil Nadu, and Karnataka generally excelling in education, health, work participation, and women’s leadership. However, data from the recent Women and Men in India 2024 report reveals a more nuanced picture. Some northern states are showing steady progress, while certain southern states are encountering new challenges.

While Kerala reports the highest female literacy rate at 95.2 per cent, followed by Tamil Nadu at 80.1per cent, Bihar and Rajasthan lag at 63.8per cent and 65.3 per cent, respectively. Himachal Pradesh and Uttarakhand, however, demonstrate female literacy rates exceeding 80 per cent, comparable to those in the South. Jharkhand has also shown a marked improvement through initiatives such as girls’ scholarships and school enrollment campaigns. 

Interestingly, the pace of improvement in these smaller northern states is sometimes faster than in the larger southern states, partly due to their size allowing for broader coverage of reforms. At the same time, some southern states are facing fresh challenges, prompting questions about whether these states’ historic advantage in gender development will hold in the coming years.

While female labour force participation lags behind male participation in India, some states are resisting this trend. Himachal Pradesh leads with 56.2 per cent, followed by Chhattisgarh (46.1 per cent), and Madhya Pradesh (39.4 per cent). Tamil Nadu maintains a relatively strong rate of 35.2 per cent and Karnataka stands at 30.5 per cent. However, experts caution that the quality of work – safety, fairness, and adequate pay – is as crucial as the quantity. Andhra Pradesh, previously a leader in rural female employment, has experienced a decline due to disappearing rural jobs and insufficient childcare and training, pushing women out of the workforce.

The Periodic Labour Force Survey 2023-24 (PLFS) indicates a national increase in rural women’s self-employment, potentially due to improved accounting of unpaid agricultural work, the effect of post-pandemic reverse migration, the expansion of MNREGS, etc. However, the overall persistent decline in female work participation rates warrants further regional analysis.

 Health outcomes sharply highlight the north–south divide in India. States in the south clock high rates of institutional births, with Kerala and Tamil Nadu exceeding 98 per cent, while the northern states lag (Bihar at 76.2 per cent, Uttar Pradesh and Uttarakhand at around 83 per cent). This divide is even more pronounced in maternal mortality ratios (MMR). Kerala has the lowest MMR at 19 deaths per 100,000 live births, followed by Tamil Nadu at 54, whereas Uttar Pradesh is at a high 167, and Bihar and Madhya Pradesh are in the 118-173 range.

These preventable deaths are attributable to weak health systems, inadequate care, and insufficient support for women during pregnancy and childbirth, not solely medical issues. Health systems in the southern states are commendable for their focus on universal health coverage through initiatives such as door-to-door delivery, mobile clinics, robust palliative care supported by volunteers, dedicated health workers, continuous community engagement, and an emphasis on preventive care.

Evenly underrepresented in governance

Women’s representation in the state legislatures varies considerably, with neither the North nor the South consistently leading. While some of the southern states like Tamil Nadu (13 per cent), Andhra Pradesh (13 per cent), Karnataka, and Kerala (12 per cent) have moderate representation, Telangana lags at 5 per cent. In the north, Chhattisgarh (21 per cent and Uttar Pradesh (15 per cent) outperform many states, as do West Bengal (14 per cent) and Delhi (11 per cent). In contrast, Rajasthan (3 per cent), Punjab (11 per cent), Himachal Pradesh (1 per cent), and Jammu & Kashmir (2 per cent) show significantly lower representation.

Despite India’s history of prominent women leaders, most assemblies remain below the 33 per cent quota seen in local governance, a situation potentially subject to change with the implementation of the Women’s Reservation Bill. The limited representation of women in legislatures, particularly in the northern states showing progress and the southern States resisting change, is largely due to political parties’ reluctance to field women candidates, even in winnable constituencies. Without a firm commitment from these parties to increase women’s representation, significant progress is unlikely. Therefore, reserving seats for women in parliament and legislatures would provide a crucial impetus.

Although South India excels in many gender-related areas, progress in states like Himachal Pradesh, Chhattisgarh, and Uttarakhand demonstrates that the north is catching up. Meanwhile, some southern states need to refocus on issues like urban gender gaps and workforce challenges. India’s gender landscape is evolving beyond a simple north-south dichotomy. Progress hinges on local leadership, cultural shifts, and sustained commitment. A comprehensive perspective is crucial for effective action. Further analysis is needed to determine if higher percentage gains in certain states, particularly in health, political participation, and female work participation, have led to greater inclusion of historically excluded populations. It’s also important to examine whether relative declines in these areas in the south are context-specific and regional.

Additionally, we should investigate if the northern states’ policies recognising women’s participation have progressed faster due to a larger percentage of previously excluded populations. Southern states outperform the national average in economic indicators such as State Domestic Product, but this success doesn’t translate into greater progress in women’s participation, warranting further investigation. 

Jyoti is an associate fellow, National Council of Applied Economic Research, Delhi; Manimekalai is Director, Centre for Women’s Development Studies, Delhi. Views are personal.

The impossible choice: tariffs, sanctions and fragmentation

From efficiency maximisers to compliance optimisers.

In 1931, Austria’s Credit-Anstalt – the nation’s largest bank – collapsed not from bad loans but from political fragmentation. Despite having the resources to intervene, French and British central banks chose political considerations over financial stability, triggering a global depression. Nearly a century later, financial institutions face the consequences of a similar choice: systematic fragmentation driven by deliberate policy.

Where the post-cold war orthodoxy sought to expand the production possibility frontier through openness, the current phase is characterised by deliberate contraction along one axis – reducing allocative efficiency to gain strategic resilience. Financial firms now maximise expected resilience and continuity of market access, subject to regulatory, reputational and technological constraints, even if that entails ceding decision sovereignty.

Financial firms confront an unprecedented triple shock: trade, tariff and sanctions regimes, alongside financial policy fragmentation. The operational risk is high – a transaction that is legal in Singapore may trigger penalties in Washington, while capital that is acceptable in Hong Kong may be prohibited in London. Financial firms reconfigure their operations – from global integrators to jurisdictional separators, from efficiency maximisers to compliance optimisers, from universal service providers to selective gatekeepers.

Tariffs: the inflation cascade

The jump to 27% average US tariff rates disrupts every financial calculation. For insurers, tariffs create a direct inflationary cascade: higher costs for imported auto parts and construction materials translate into higher repair and replacement claims. Insurify projects a 19% premium increase by the end of 2025 as auto repair costs surge. Federal Reserve data show that vehicle repair costs have increased by 28% since 2020. The National Association of Home Builders estimates tariffs add $7,500-$10,000 per home in construction costs. Property insurers must reprice policies in real-time, abandoning actuarial stability in favour of quarterly adjustments.

For governments, tariffs also serve as a fiscal stress multiplier: higher subsidy outlays to offset inflation collide with reduced tariff revenues as trade volumes decline, creating new contingent liabilities that quickly spill over into sovereign balance sheets.

Trade finance becomes risk management speculation. Banks develop ‘tariff hedges’ – derivatives priced at 3% to 5% of transaction value. The steady business of financing trade becomes high-stakes speculation on political decisions, with approval processes contingent on tariff announcement schedules rather than borrower fundamentals.

Sanctions: the impossible choice

Sanctions force financial institutions into binary decisions – serve Russia or serve the West, access China or access America. The International Monetary Fund reports that correspondent banking relationships had begun to decline earlier. Each terminated relationship cuts entire countries from global finance.

The 2025 sanctions regime has dramatically accelerated correspondent banking withdrawals. The US Office of Foreign Assets Control’s November 2024 alert targeting Russia’s System for Transfer of Financial Messages payment system explicitly warns that ‘any foreign financial institution that joins or has already joined SPFS may be designated’ – forcing banks to choose between serving Russia-connected institutions or accessing US financial markets. The European Union’s 18th sanctions package banned SPFS entirely.

Banks implement ‘structural apartheid’ to survive. HSBC’s restructuring into eastern and western entities represents a shift from single-market integration to segmented-market models, reducing cross-jurisdictional compliance correlation. JP Morgan allocated $18bn to technology in 2025 – with significant portions dedicated to compliance systems across contradictory sanctions regimes.

Fragmentation: exponential complexity

Regulatory fragmentation creates exponential complexity. Five major jurisdictions generate 20 potential conflicts; 10 create 90. Securities firms maintain parallel teams for each jurisdiction. Chinese companies that once raised over $150bn globally now face dramatic constraints. In 2024, Chinese mainland markets raised only $9.3bn through initial public offerings – the lowest level in nearly a decade.

Compliance becomes prohibitive. Fund managers maintain separate portfolios: US versions exclude Chinese military companies, while European versions exclude Russian energy companies. Legal teams quadruple while investment teams shrink. Investment opportunities disappear as compliance departments exercise veto power over portfolio construction, accepting lower economies of scale in exchange for reduced tail-risk exposure.

For advanced economies already carrying historically high debt ratios and limited fiscal buffers, this multiplication of compliance costs erodes fiscal resilience as surely as it undermines competitiveness. The fragmentation penalty is not confined to the periphery – it also weakens the core.

How financial firms are adjusting

The observed responses group into three categories. First, hard-power adaptation: banks retreat from correspondence relationships, implementing regulatory technology solutions as binding constraints in their optimisation problems. Second, institutional rewiring: securities firms restructure their operations from global to regional, creating alternative market infrastructures to reduce single-point failures.

And third, risk diversification: asset managers often sacrifice diversification for compliance, creating redundancy in operations while accepting lower decision sovereignty in exchange for higher continuity of operations.

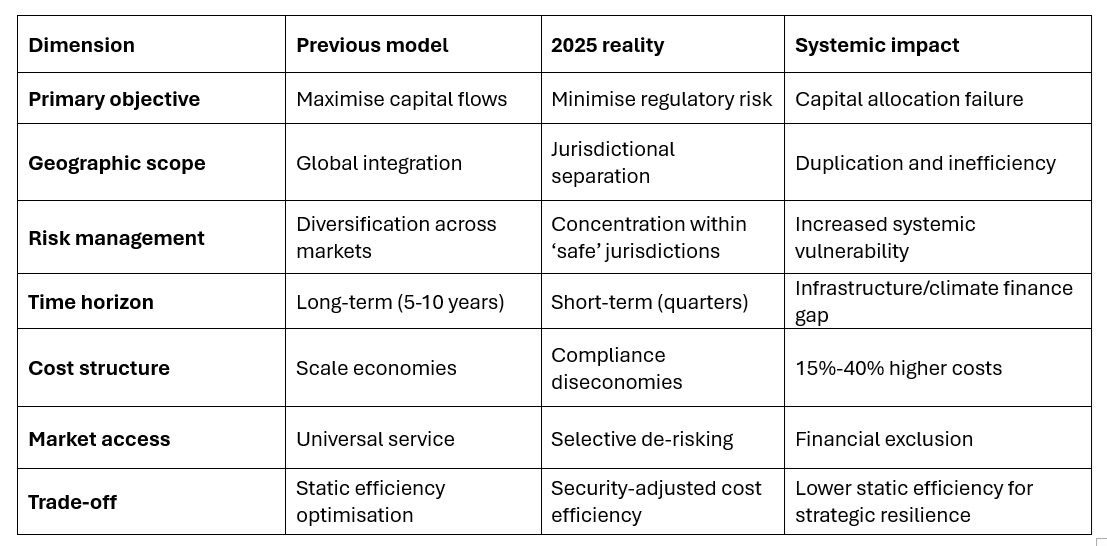
Figure 1. From integration to fragmentation – the new reality

This transformation represents a permanent restucturing. Time horizons collapse when rules change quarterly; banks will not lend beyond the scope of political cycles. Infrastructure and climate finance, which require 30-year commitments, are rendered impossible when the horizon of certainty has shrunk to two or three years.

Systemic consequences

The micro adjustments aggregate to macro failure. Developing countries facing a $3.9tn sustainable development goal financing gap lose access as banks de-risk. Fragmentation concentrates rather than diversifies risk. The dollar’s weaponisation undermines its foundation. The Atlantic Council’s Dollar Dominance Monitor shows 88% of foreign exchange transactions remain dollar-based – not from strength but absence of alternatives.

Three futures emerge from current trajectories. Continued fragmentation represents the baseline scenario where current trends persist. Cross-border capital allocation efficiency deteriorates. This path features gradual economic decoupling, with developing economies excluded from the global financial system. Growth rates decline as financial intermediation becomes a compliance exercise.

System breakdown occurs when fragmentation exceeds institutional capacity for compartmentalisation. Binary regulatory choices accelerate into cascade failures as correspondent banking networks collapse suddenly. Financial contagion spreads through isolation mechanisms – when the last bank serving a jurisdiction exits, entire economies face liquidity crises. This scenario triggers rapid dedollarisation and parallel financial architecture.

Forced reintegration emerges when economic costs exceed political tolerance for fragmentation. Financial institutions demand regulatory coordination to maintain operational viability. Crisis-driven negotiations yield new frameworks balancing national security and systemic stability. This path requires recognition that financial weaponisation undermines the weapon itself.

The reintegration scenario raises a further question: who could credibly lead it? The IMF and Financial Stability Board retain convening authority; however, the fragmentation of multilateralism itself limits their reach. More likely, any forced reintegration would come through crisis-driven bargaining among G20 powers, with private financial institutions pressing hardest for a new settlement.

Conclusion

In dynamic-system terms, the global economy has shifted from a high-integration equilibrium towards a more fragmented state, but the transition path is still in motion. For financial institutions, the challenge is calibrating marginal gain in resilience against the marginal erosion of competitive advantage.

Global financial institutions survive by ceasing to be what they were: efficient intermediaries of international capital. The events of 2025 – from OFAC’s SPFS alert to the EU’s complete ban on financial messaging – demonstrate that we are abandoning what worked without building something that might work better.

The question is not whether this fragmentation is sustainable, but rather how much economic damage accumulates before the impossibility of parallel financial systems forces either breakdown or reluctant reintegration.

Udaibir Das is a Visiting Professor at the National Council of Applied Economic Research, Senior Non-Resident Adviser at the Bank of England, Senior Adviser of the International Forum for Sovereign Wealth Funds, and Distinguished Fellow at the Observer Research Foundation America.

    Get updates from NCAER