Build A Creche Like You Would A Highway

Formalising part-time work with fair pay, making transport and housing women-friendly, and enforcing laws. Otherwise, urban women’s work participation will be stuck at 28%

As India’s economy rapidly transforms and modernises riding on a youthful population, a booming digital and physical infra, and a spirit of optimism, conditions are favourable for the country to become a global economic powerhouse. Yet, a glaring omission persists: the full and equal participation of women in the workforce.

India vs the rest | While Indian women now outpace many global peers in education, comprising over 45% of undergraduates, their participation in the labour force, especially in urban areas, remains alarmingly low at just 28%, half of the remaining G20 average that exceeds 56%.

Globally, 47% of women are active in today’s labour markets, compared with 72% of men. This has immense economic growth potential for India, as well as the global economy.

IMF estimates emerging and developing economies could boost GDP by about 8% over the next few years by raising the rate of female labour force participation (FLFPR) by nearly 6 percentage points. This is the average amount by which the top 5% of countries reduced the participation gap during 2014-19.

Missing half the workers | Across countries, high FLFPR are driven by several enablingvpolicies: child and elderly care infra; safe and affordable housing and transportation; equalvaccess to real and financial assets; existence of flexible and part-time work; and social andvcultural norms.

Sweden, for example, has formalised part-time work and spends over 1.5% of GDP onvsubsidised childcare, lifting FLFPR to more than 80%. In Chile, universal early childhood programmes have increased maternal employment by over 10 percentage points.

Countries like Egypt have seen female employment rise through dedicated women-only metro cars. Meanwhile, advanced economies like Netherlands and Germany have unlocked female talent by ensuring part-time work comes with the same protections and pay as full-time roles.

Counting barriers | What has been India’s record in addressing barriers that prevent women from fully participating in the economy? Formalised part-time work simply does not exist.

In keeping with its goal to promote women’s economic empowerment and women-led development, Centre has in place at least 40 programmes across ministries in rural and urban areas. These are yielding results in rural areas, doubling FLFPR from 24% in 2017- 18 to around 48% in 2023-24. However, with FLFPR at 28% in 2023-24 in urban areas, these programmes are yet to make substantive difference. Many of the efforts remain scattered, underfunded, and not of high quality.

Mend infra gaps | A recent paper analysing a job-search model grounded in Indian data, found that formalising part-time employment contracts and gender-equitable burdensharing of unpaid care work could raise overall FLFPR by 6 percentage points from 37% to 43%.

This has two policy implications. First is to address gaps in formal part-time employment. Current labour codes recognise only full-time employment (48 hours/week), leaving millions of part-time workers unprotected. India needs to align with ILO standards to ensure part-time work guarantees fair pay, equitable benefits, and legal safeguards. Formalising part-time employment and introducing flexibility in working hours is lowhanging fruit as it can be implemented quickly.

Second, closing gaps in women-friendly infra. For example, very few Anganwadis operational in India meet quality benchmarks and elder care is virtually non-existent beyond big cities. There is limited women-only public transport, an acute shortage of working women’s hostels, and weak enforcement of anti-harassment laws, with less than 7% of sexual harassment cases resulting in convictions.

Learn from states | While some Indian states are already leading the way — Tamil Nadu, for example, with its expansion of working women’s hostels and Kerala with its self-help groups — much more is needed. India stands to gain immensely by activating its ‘missing’ female workforce. Capital investments in digitalisation, ports, highways, railroads, and bridges are undoubtedly transforming India’s economy.

But this transformation also requires building crèches and elder care facilities with the same urgency as roads; constructing working women’s hostels like highways; and ensuring safe and reliable public transport for women as more metro systems and buses are introduced. In addition, strict enforcement of existing laws on safety, harassment, maternity benefits, tax credits for private care facilities, and rural eldercare cooperatives could go a long way.

Investing in increasing FLFPRs will transform the living standards of families and raise GDP to even higher levels, paving the way for changing patriarchal norms and mindsets as it benefits everyone. In short, investing in women isn’t just a matter of equity — it is smart economics.

The writers are with NCAER. Views expressed are personal.
From access to awareness: Why India needs to boost digital financial literacy

From UPI processing over 17 billion transactions in a single month to kirana stores & vegetable vendors using QR codes, digital finance in India is no longer a luxury — it’s a lifeline.

This surge has brought unprecedented financial inclusion, especially in rural and semi-urban areas. But while access has grown, awareness has not kept pace.

“DFL combines two critical competencies: digital literacy and financial literacy. It means knowing how to use a smartphone or a payment app, but also understanding savings, credit, frauds, and grievance redressal. Without this knowledge, individuals are at serious risk of being excluded, misled, or even financially exploited.”

India is in the middle of a digital finance revolution — but the lack of Digital Financial Literacy (DFL) could make it a double-edged sword.

The gaps are striking. While India’s literacy rate is over 80%, only 24% of people are financially literate — far below the global average of 42%. Among millennials, digital natives by label, only 19% are digitally financially literate.

This gap between access and understanding is creating a vulnerable population in an increasingly digital economy.

The digital divide in India isn’t just technological — it’s gendered, generational, and geographic.

“Women in many parts of the country still lack access to mobile devices or internet services.”

Deep-rooted cultural norms, psychological barriers, and a persistent reluctance to engage with financial matters often discourage women from managing their money independently and confidently.

Meanwhile, senior citizens and rural users may own phones but lack awareness of fraud risks or digital payment safety.

Even the educated aren’t safe. Many fall prey to phishing scams and digital frauds, unaware of how to freeze their UPI IDs or report financial crimes.

According to the RBI, bank frauds — particularly via digital channels — have tripled.

Over 63,000 cases involving frauds of ₹1 lakh or more were recorded under digital payments last year.

Digital illiteracy doesn’t just exclude; it leads to misuse. Millions of Jan Dhan accounts remain inoperative. Young consumers, enticed by Buy Now Pay Later (BNPL) schemes and easy credit, risk falling into debt traps. In the microcredit space, lack of awareness about repayment terms has led many into cycles of over-indebtedness.

Bridging the Gap

To address this, a coordinated national strategy is needed — bringing together government, regulators, educators, community leaders, and the private sector.

DFL must be made a part of school and college curricula across all disciplines. Students should learn how to use digital banking tools safely, recognize scams, and understand key financial concepts. It should be treated as essential as math or language — not just an optional module.

“Further, mass awareness campaigns need to be rolled out in local languages through TV, radio, and social media. In rural areas, storytelling, theatre, mobile vans, and public fairs can serve as effective platforms. Interactive kiosks at panchayat offices, markets, and railway stations can help bridge information gaps.”

Local influencers — teachers, Anganwadi workers, SHG leaders, and panchayat heads — should be trained as DFL ambassadors. Gram sabha meetings can be used to share practical advice on identifying fake apps, safe digital practices, and redressal mechanisms.

Senior citizens need dedicated support. Customised workshops using simple guides and visual aids can help them understand and trust digital finance. Banks and post offices should offer helplines and walk-in helpdesks to assist older users.

Similarly, outreach for women must be targeted and culturally sensitive. Women-led financial literacy circles, SHG-based digital training, and awareness sessions through Mahila Mandals and Anganwadis can help build both access and confidence.

DFL for youth and gig workers can leverage gamified mobile learning. Interactive videos, WhatsApp-based modules, and digital quizzes can make learning about finance easy, engaging, and widely accessible.

“Fraud-prevention modules should be a mandatory part of onboarding whenever a person opens a bank account or downloads a payment app. Just like KYC norms, digital hygiene must become routine.”

Also, certified DFL training can be linked to access to credit or government schemes. Incentives like digital cashback or micro-rewards could encourage participation, especially in low-income households.

Finally, a Digital Financial Literacy Index can be developed and published at regular intervals to measure progress, identify gaps, and guide data-driven policymaking. Fintech companies and banks must also contribute through CSR — co-developing content, conducting workshops, and running digital safety drives across geographies.

The Road Ahead

India has laid the groundwork — with UPI, Jan Dhan, Aadhaar, and mobile networks forming the backbone of a robust digital finance system. But infrastructure alone cannot ensure effective inclusion and digital safety. Without DFL, these tools can increase vulnerability to risk, not empowerment.

A digitally enabled society must therefore be a digitally literate one. As we transition toward a cashless, connected economy, digital financial literacy must be seen not as a privilege — but as a non-negotiable life skill towards achieving our goal of Viksit Bharat.

(The writer is the IEPF Chair Professor, NCAER. He was honoured with the “Investor Education and Awareness Award 2024” by SEBI and AMFI for his exceptional contribution in the field of Investor Awareness and Education, given at the IITF, Delhi on 23rd November 2024. He is a former Indian Economic Service officer of the 1986 batch.)

Swipe, tap, exclude: The uneven march towards financial inclusion

Over two-thirds of Indians who use digital devices struggle with basic digital banking transactions, highlighting the persistent challenge of bridging the digital literacy and access gap.

India, amidst rapid technological advancement, stands at a critical juncture in its digital journey. The nation has demonstrably invested in the foundational pillars of digital financial services through significant infrastructure development, progressive policymaking, and public awareness campaigns — epitomised by flagship initiatives like Digital India, Jan Dhan Yojana, and Aadhaar integration. It has undeniably reshaped the financial landscape, particularly during and after the Covid pandemic.

The Department of Financial Services (DFS), Ministry of Finance, hosted the Digital Payments Awards ceremony on June 18, 2025, to recognise the strength of the nation’s digital payments ecosystem. It highlighted that nearly half of all real-time digital transactions in the world are happening in India with 35 crore active users being part of UPI system, and also that the country has an 87 per cent fintech adoption rate compared to 67 per cent globally.

However, this impressive digital façade hides a sobering reality: Over two-thirds of Indians who use digital devices struggle with basic digital banking transactions, highlighting the persistent challenge of bridging the digital literacy and access gap.

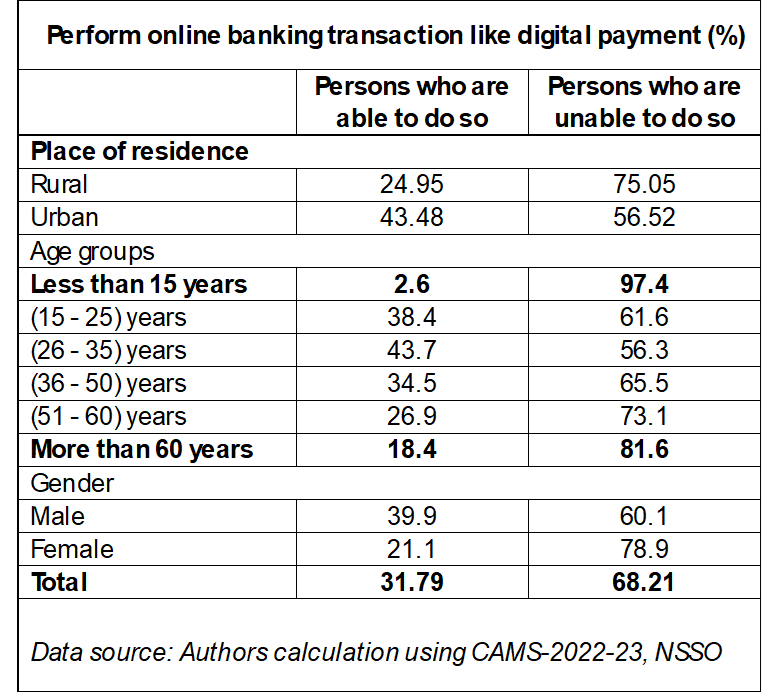
According to data from the Government’s Comprehensive Annual Modular Survey (CAMS- 2022-23), only 31.7 per cent of people who use a digital device (mobile phone, computer, laptop, or tablet) are capable of carrying out digital financial activities like online payments. This isn’t just a gap — it’s a gaping blind spot, one that threatens to transform a well-intentioned digital revolution into a tool of exclusion.

The digital skew

Urban India, with its superior access to internet connectivity, banking facilities, and digital literacy programmes, reports a comparatively higher share of digital banking users — 43.48 per cent. However, even this figure highlights that over half of urban residents are still unable to use basic financial tools. The rural statistic is more alarming — nearly three-quarters (75.05 per cent) of the rural population cannot perform digital transactions. For rural India, digital inclusion remains a promise deferred.

Predictably, digital proficiency peaks among the youth. In the 26–35 age group, nearly 44 percent can perform digital transactions. This is the working-age population, which is more likely to have smartphones, jobs with salary accounts, and exposure to digital ecosystems. Conversely, people above 60 show alarmingly low digital engagement.

Children under 15 are understandably out of the financial loop, hence the lower capability. However, the digital exclusion of the elderly — more than 81 per cent are unable to transact digitally — is concerning. Many senior citizens struggle with using digital apps, forget passwords, or fear fraud, leading to a reluctance to adopt online banking.

Perhaps the most troubling disparity revealed by CAMS data is the digital gender gap. While around 40 per cent of men can transact online, only 21 per cent of women can do so — a gap of nearly 20 percentage points. This isn’t merely about access to technology; it reflects entrenched gender inequality in education, employment, asset ownership, and digital autonomy.

In the lowest expenditure quintile (Q1), only 13.56 per cent of rural individuals are able to use online banking for digital payments, compared to 24.53 per cent in urban areas. This nearly twofold gap, though alarming in itself, is only a small piece of the broader disparity. The adoption rate increases steadily with expenditure in both rural and urban areas. However, the rate of growth is notably sharper in urban areas.

By the highest expenditure quintile (Q5), 61.91 per cent of urban individuals are able to use digital banking services — a figure that dwarfs the 37.71 per cent adoption in rural areas. But even in Q5 — where individuals theoretically have better access to smartphones, internet connectivity, and bank accounts — nearly two-thirds of rural residents are still not able to use digital banking.

This may indicate not just infrastructural issues but also a lack of trust, digital literacy, and support systems in rural settings.

Bridging the faultlines

The data paints a worrying picture: India is moving towards a two-speed digital economy —one inhabited by the digitally fluent who can transact, save, invest, and borrow; and the other by the digitally stranded, who remain dependent and are increasingly being left behind. This divide is not due to unwillingness but systemic barriers, which include linguistic exclusion, digital illiteracy, and cultural constraints.

India’s digital revolution must be reimagined to serve every Indian — not just the urban, young, male minority that currently benefits the most. To ensure inclusiveness, targeted interventions are needed. These can include rural digital literacy drives in local languages, special training for the elderly and simplified interfaces, empowering women with direct access to mobile technology and policies to include individuals in banking and tech ecosystems.

The true test of a digital economy lies in who it includes — and who it leaves behind.

Palash Baruah is fellow at National Council of Applied Economic Research (NCAER), New Delhi and D L Wankhar is a retired Government of India officer. Views are personal.

Why India must tap its wastewater prospects

A country that aims to supply piped drinking water to every rural household continues to lose billions of litres of water daily because of inadequate treatment.

India’s water and wastewater treatment market, valued at $13.1 billion in 2023, is projected to reach $23.85 billion by 2033. This number mirrors India’s accelerating urbanisation, climate fragility, and industrial thirst. In 2020, urban centres generated over 72.4 billion litres per day (BLD) of sewage; yet, the installed treatment capacity stood at just 31.84 BLD. The deficit of over 40 BLD represents a staggering gap in basic infrastructure. Progress here is unbalanced: Maharashtra treated over 8 BLD in end-2023, while Bihar treated under 0.4 BLD, despite comparable population pressures.

A country that aims to supply piped drinking water to every rural household continues to lose billions of litres of water daily because of inadequate treatment and reuse mechanisms. Can a water-secure India ever emerge if it continues to ignore wastewater?

India’s industrial sector is a major player in this landscape. The industrial wastewater treatment sub-market was worth $1.44 billion in 2023 and is set to touch $2.4 billion by 2033.

Sewage treatment, meanwhile, remains the second-largest segment, growing from $5.01 billion in 2023 to a projected $9.08 billion by 2033. Water treatment, including desalination and recycling plants, dominates, climbing from $6.65 billion to $12.37 billion in the same period. This layered growth hints at the simultaneous pressures of urban expansion, rising demand for potable water, and tighter environmental mandates.

However, these numbers obscure a deeper structural issue — policy fragmentation. Despite the consolidation of water-related departments into the Jal Shakti ministry in 2019, overlapping jurisdictions, state-level inertia, and a lack of techno-commercial capacity often derail projects mid-stream.

India’s wastewater sector is undergoing a significant technological pivot. Traditional chemical treatment is steadily giving way to more sustainable, membrane-based approaches like reverse osmosis (RO), sequencing batch reactors (SBR), and membrane bioreactors (MBR). The market for these advanced technologies is buoyed by rising industrial compliance costs and water reuse mandates.

However, with MBR systems being very expensive, the barriers to entry remain steep — particularly for small municipalities and low-income states. Public-private partnerships (PPPs) offer a partial solution, but uptake has been uneven. Tamil Nadu and Gujarat are leading examples, boasting some of the largest municipal and industrial desalination projects in Asia. But here’s the catch — decentralised systems that serve peri-urban clusters, villages, and small towns are virtually absent in policy frameworks. Real-time water quality monitoring, process automation, and AI-enabled compliance tools are still limited to large city projects or high-end industrial clusters.

India’s budgetary allocations for water and sanitation are substantial but not transformative. In 2023, only 67% of Amrut 2.0 funds were utilised, and over ₹6,000 crore of Jal Jeevan Mission grants remained unspent. Moreover, capital allocation is skewed towards urban megaprojects, while smaller cities — where over 60% of untreated wastewater originates — are left behind. Private investment faces its own hurdles. A 2023 industry survey revealed that 53% of wastewater firms cite high operating costs and lack of guaranteed returns on investment for not bidding on tenders. If the wastewater sector is to meet its $23.8 billion potential by 2033, India will need innovative financing mechanisms, including green bonds, water credits, and blended finance models.

India’s wastewater success is often measured by construction of sewage treatment plants (STPs) — by programmes such as Amrut 2.0 and Namami Gange — rather than performance. In 2023, as per the Central Pollution Control Board (CPCB), 40% of STPs failed to meet national discharge standards. Mandating zero liquid discharge (ZLD) for polluting sectors is a step in the right direction. But enforcement remains patchy. Only 13% of textile units in Punjab and Haryana were ZLD compliant as of mid-2023, despite repeated notices. Moreover, state-level implementation varies wildly. While Maharashtra, Gujarat, and Tamil Nadu have crossed 75% of their planned STP capacity, states such as Jharkhand and Tripura remain under 15%.

The “3R” mantra — reduce, reuse, recycle — is slowly entering industrial and municipal thinking. Yet nationally, less than 20% of treated wastewater is reused. The rest is discharged back into the environment. Circular thinking also opens the door to energy recovery, nutrient extraction, and sludge-to-brick conversion. In Pune, for instance, biogas from sewage sludge powers local buses. But such projects are outliers, not norms. India’s policy focus must shift from wastewater disposal to resource recovery.

The challenge is immense — but so is the promise. The drain, it turns out, may be the most powerful pipeline to India’s sustainable future.

Souryabrata Mohapatra is an assistant professor at the IIT Jodhpur School of Liberal Arts, and Amit Mitra is a research associate at NCAER, New Delhi. The views expressed are personal.

NCAER News: June 2025

NCAER News is a monthly digest where you can learn about NCAER’s research outputs, its latest events, and offerings.

    Get updates from NCAER