Tapping India’s hidden wastewater wealth

Chennai has demonstrated that wastewater reuse is not just a pipe dream, selling secondary-treated wastewater and using proceeds to rejuvenate water bodies. What India needs is an ecosystem to treat 70% of water going down drains.

India is set to become home to a quarter of the world’s urban population living in water-stressed regions. While the nation races towards economic prosperity, its urban centres are buckling under mounting water stress, rapid in-migration, and shrinking freshwater reserves. But what if the solution to India’s water woes — and an untapped economic opportunity — lies not in its rivers or reservoirs, but in its drains?

India generates over 72,000 million litres of domestic wastewater every day, yet only 28% of this is currently treated. The rest contaminates surface water, burdens ecosystems, and worsens public health. In a country where 70% of the water supply is contaminated, affecting 75% of the population, this is more than an infrastructural shortfall — it’s a national crisis.

But hidden in this crisis is a circular economy goldmine. If treated and reused, wastewater can not only replenish urban water supplies and mitigate environmental degradation but also fuel a multi-billion-dollar reuse market.

Scaling up wastewater treatment and reuse isn’t merely a climate or health imperative—it’s an economic one. According to projections, by 2050, India will have the capacity to treat 80 per cent of its sewage, equivalent to 96,000 million litres per day. At current market rates, this could fetch Rs 1.9 billion daily, nearly tripling from Rs 630 million in 2021.

The reuse of treated wastewater (TWW) also offers staggering potential in agriculture. In 2021, 8,603 million cubic metres of TWW could have irrigated 1.38 million hectares (Mha) — roughly nine times the area of Delhi — yielding produce worth Rs 966 billion. 

With inherent nutrients like nitrogen, phosphorus, and potassium, this water could reduce fertiliser use, saving an additional Rs 50 million. By 2050, irrigation potential will become more than triple, enabling over 3 Mha of cultivation. This is circularity in action — using what was once waste to grow food, save water, cut fertiliser use, and generate jobs.

Several Indian cities have already demonstrated that wastewater reuse is not just a pipe dream. Chennai sells secondary-treated wastewater to industries and uses the proceeds to rejuvenate local water bodies. Delhi reuses tertiary-treated water for groundwater recharge, reducing energy demands for extraction. Cities like Gwalior and Kanpur have channelled TWW for suburban irrigation.

But these are exceptions, not the norm. For India to unlock the true potential of this circular economy, we need systemic change backed by strong policy, innovative financing, and public acceptance.

The policy groundwork is slowly taking shape. India’s National Water Policy (2012) mandates TWW reuse. The National Framework on Safe Reuse of Treated Water guides state policies. Schemes like Namami Gange, AMRUT 2.0, and Swachh Bharat Mission–Urban have also injected momentum into urban wastewater management.

Yet, gaps persist. Many state policies drafted before the 2023 framework need urgent updating, especially around effluent quality standards and reuse-specific business models. Urban local bodies must be empowered to create city-level reuse plans, identifying opportunities across irrigation, construction, landscaping, industrial cooling, and more.

Equally critical is the technological shift. In a business-as-usual scenario (unabated growth in GHG emissions), India’s sewage treatment energy demand will more than triple by 2050, rising from 11.6 terawatt hours (TWh) in 2021 to 35.1 TWh. When it comes to technologies like the Moving Bed Biofilm Reactor and Activated Sludge Process, they are energy-intensive, requiring up to 224 kilowatt hours (kWh) per million litres per day (MLD). In contrast, Water Stabilisation Ponds and Upflow Anaerobic Sludge Blankets with Extended Aeration systems demand far less, just 6 and 126 kWh/MLD, respectively.

Switching to low-energy or nature-based solutions — and powering STPs through solar or bio-energy — can make wastewater treatment green and cheaper.

What India needs now is a viable financial ecosystem to fund this transition. Encouragingly, new models are emerging. The Green Credit Programme enables tradable credits for environmentally sound practices like TWW reuse. Similarly, Wastewater Reuse Certificates—pioneered by the 2030 Water Resources Group—operate like carbon credits. Bulk users exceeding their reuse targets earn certificates; others buy them to offset shortfalls. Maharashtra is already piloting this system.

The Hybrid Annuity Model, tested under the Clean Ganga Mission, allows private players to build and operate STPs over 15 years, with the government paying annuities tied to performance. Corporate Social Responsibility funds, too, can be leveraged — whether for building infrastructure or training farmers in safe reuse practices. In short, with the right incentives and institutional mechanisms, wastewater reuse can be both financially sustainable and socially inclusive.

Reusing wastewater has co-benefits beyond the balance sheet. If India had used the available TWW for irrigation in 2021, the reduced pumping and fertiliser usage could have enabled the nation to cut greenhouse gas emissions by 1.3 million tonnes.

Moreover, wastewater management can create green jobs in plumbing, treatment operations, water auditing, and urban planning. As cities expand, these roles will be vital in building climate-resilient infrastructure.

Still, the greatest challenge may not be technical or financial, but behavioural. Many communities remain hesitant about using treated wastewater, particularly in food production. Awareness campaigns, crafted with local insights, are essential to shift perceptions and showcase TWW as a safe, sustainable, and smart resource.

A circular economy is not just about reusing waste, but it’s about rethinking value. India’s wastewater, long seen as a problem, is now an opportunity. If harnessed wisely, it can quench our cities, irrigate our fields, green our economy, and clean our future.

The question is no longer “Can we afford to treat and reuse wastewater?” It is: “Can we afford not to?”

Mohapatra is with IIT Jodhpur, and Mitra is with NCAER. Views are personal.
India Human Development Survey: June 2025

The IHDS Forum is a monthly update of socio-economic developments in India by the IHDS research community, based on the India Human Development Survey, jointly conducted by NCAER and the University of Maryland. While two earlier rounds of the survey were completed in 2004-05 and 2011-12, respectively. Fieldwork for the third round was undertaken in 2022-24 and the data is currently being cleaned and processed.

Click here for previous issues

Private versus public: US and Europe diverge over stablecoins

Different approaches to regulation risk fragmenting the global digital finance landscape

Stablecoins have emerged as a practical alternative to the traditional banking system for payments and remittances. These digital coins seek to maintain stable value by pegging to currencies like the dollar, combining blockchain technology with reserve backing. They bring opportunities for more accessible and efficient financial intermediation, but also raise concerns about monetary control, illicit transactions, user protection and financial stability.

However, a fundamental divide has emerged between the US approach to the regulation of stablecoins, which encourages private sector innovation, and the European approach, which prioritises sovereign monetary and regulatory control. This divergence in approach could profoundly reshape the global financial structure.

Regulatory and policy concerns

The growing use of stablecoins in finance is raising a complex set of policy concerns. These include the risk of undermining official currencies as more transactions migrate to stablecoin platforms, their potential use in illicit financial flows, gaps in safeguards for retail users and unresolved questions surrounding the taxation of returns on cryptoassets.

Regulatory concerns are arising from the increasing role of stablecoins in financial intermediation. Central banks and regulators now consider large stablecoin issuers as systemically important institutions. The US Financial Stability Oversight Council 2024 Annual Report noted that stablecoins ‘continue to represent a potential risk to financial stability because they are acutely vulnerable to runs absent appropriate risk management standards’.

Concerns were highlighted by the May 2022 collapse of TerraUSD (which lost its dollar peg entirely) and the November 2022 failure of the FTX exchange, as well as brief de-pegging events affecting even major stablecoins like USDC under banking sector stress in March 2023. Such events can have systemic implications given that stablecoins’ integration with securities markets, custody chains and payment processors creates links to the core financial infrastructure.

A related concern is that weak reserve management by stablecoin issuers or trading platforms could trigger collateral fire sales during mass redemptions, driving down the cost of assets and potentially destabilising other parts of the financial markets.

To date, however, progress in addressing these risks has been uneven, slowed by the absence of clear regulatory mandates over stablecoin activities and by diverging views among policy-makers and agencies on the dangers and potential benefits of this rapidly evolving ecosystem.

Transatlantic divergence

The transatlantic divergence in the regulation of stablecoins widened in early 2025. The US, under the Donald Trump administration, views stablecoins primarily as vehicles for innovation – tools to expand consumer choice and provide more efficient forms of financial intermediation, with the additional benefit that the rapidly rising use of dollar stablecoins helps to bolster dollar dominance globally. An executive order issued in January 2025 promoted stablecoins while explicitly prohibiting central bank digital currencies in the US.

Meanwhile, the Generating Revenue and Enhancing National Investment by Using Stablecoins Act, which has just been passed by the Senate, proposes a light touch but structured framework for stablecoins. The Act mandates that stablecoins be backed 1:1 with safe, liquid assets and that issuers undergo regular audits and adhere to disclosure requirements.

However, it carves out a separate regime for smaller issuers – with less than $10bn in outstanding stablecoins – allowing them to operate under state-level oversight. This has raised concerns about regulatory arbitrage and the potential for inconsistent standards across jurisdictions, and the potential for systemic risk from a growing multitude of alternative forms of digital money.

Europe is taking the opposite approach, prioritising tighter control. This is not just a technical difference from the US – rather, it reflects competing visions about who should control the future of finance: private companies or government institutions. The European Central Bank’s concerns focus on monetary sovereignty and the ability to implement effective monetary policy in a digital world. The ECB is accelerating the development of a digital euro to counter the growth of US stablecoins, with pilot testing of a coordinated digital payments platform expected by the end of 2025.

At the same time, EU regulations treat stablecoin issuers much like banks, with equivalent capital and operational rules. The European Union’s Markets in Crypto-Assets regulation, adopted in 2024, imposes stricter rules than the US GENIUS Act. It requires large stablecoin issuers to maintain strong capital buffers, establish clear liability frameworks and implement tight operational controls. MiCA also seeks to limit the spread of non-euro stablecoins, particularly dollar-denominated ones, by increasing compliance costs and making authorisation more challenging for foreign issuers.

What this means

Diverging approaches to regulating stablecoins risk fragmenting the global digital finance landscape, with a dollar-based stablecoin system in the US, a state-backed European digital euro regime and a mix of regional approaches elsewhere. These competing models risk disrupting the transmission of monetary policy, cross-border capital flows and regulatory coherence.

Stablecoins must now be considered an integral part of the core financial architecture. A coordinated international response is needed before their scale outpaces the capacity of any single jurisdiction to manage the risks they pose to monetary and financial stability.

Udaibir Das is a Visiting Professor at the National Council of Applied Economic Research, Senior Non-Resident Adviser at the Bank of England, Senior Adviser of the International Forum for Sovereign Wealth Funds, and Distinguished Fellow at the Observer Research Foundation America.

Export thrust: India should move goods like a horse to trade like a Tiger

India has taken big strides in its logistical infrastructure but must press ahead with reforms to meet its aspiration of becoming a global trading powerful. Easing and speeding up exports is critical to that endeavour.

India’s merchandise exports grew by a significant 39% from $317.5 billion in 2014 to $441.7 billion in 2024. This rise in exports testifies to India’s ambition of positioning itself as a global manufacturing and export powerhouse. Flagship government schemes, such as production-linked incentives (PLI), Make in India and the Phased Manufacturing Programme have played a vital role in India’s export thrust.

The ‘trading across borders’ indicator from the World Bank’s 2020 Doing Business data-set showed that exporting from India took significant time and money. On average, border procedures alone took 52 hours and $212 per container. Export documentation consumed 12 hours and $58. Importing took even more—with around 65 hours and $266 needed for border clearance, and 20 hours and $100 for documentation.

In comparison, China was processing the same export shipments within 21 hours at a slightly higher cost of $256 per container. It processed documents faster too, in 9 hours on average, although the documentation cost is $74, slightly higher than in India.

India was better placed than the likes of Bangladesh and Vietnam, but behind countries like South Korea, which was the world leader on those counts. South Korea was doing border checks in just 13 hours at a cost of $185, and document processing in 1 hour for only $11. All these numbers showed the gap India needed to cover in competition with the world’s best export performers. While Doing Business data is old and the World Bank has discontinued this study, its broad 2020 rankings may not have changed very much (except in Vietnam’s case perhaps).

More recent data from the World Bank’s Logistics Performance Index (LPI) offers us another picture. This index tracks the transportation of goods within and between countries, taking into account six measures: customs efficiency, infrastructure, ease of coordinating international shipments, logistics quality, tracking and tracing ability, and punctuality (frequency of on-time shipments).

India: On the move

The country is catching up with China on the movement of goods within and across borders but still has some distance to cover.

Logistics performance index, India and China

As reported by the 2023 LPI report, India has taken significant strides on logistics, moving its world ranking from No. 54 in 2014 to No. 38 in 2023, with its score rising from 3.08 to 3.4. Its ranking on timeliness rose from No. 51 to No. 35, and its score for logistics competence and quality rose from 52 to 38, signifying higher professionalism and reliability in freight services.

Moreover, in terms of infrastructure (covering ports, roads and railways), India’s rank rose from No. 58 to No. 47, reflecting the impact of recent investments in physical logistical infrastructure.

Still, China is ahead of India on an absolute basis, at 19th place with a score of 3.7. It scores better on all the key factors: timeliness, quality of logistics and impressively on infrastructure, indicating the strength and dependability of its supply chain mechanisms. India’s progress is heartening. Yet, continued efforts are needed to reach the logistics performance of global leaders.

India has also achieved impressive reductions in ‘dwell time’—the number of days that cargo is held at a terminal or port before it can proceed. In the LPI 2023 report, while 4 to 8 days is the typical dwell time for economies at every level of income, India is on par with Singapore with a dwell time of only 3 days. This is an achievement ahead of the UAE, South Africa, US and Germany, indicative of improved coordination between customs officials, port authorities and logistics firms.

Underpinning these efficiency gains is India’s massive investment in transport and logistics infrastructure. The coverage of National Highways (NH) increased from 65,569km in 2004 to 146,145km in 2024, with four and more lane stretches rising 2.6 times since 2014.

The construction tempo has picked up sharply, from 12.1km per day in 2014-15 to 33.8km per day in 2023-24. Flagship programmes such as the Bharatmala Pariyojana launched in 2017, are developing 26,000km of economic corridors, ring roads, bypasses and elevated corridors to ease city congestion and enhance freight movement. As of November 2024, 18,926km of roads had been constructed under this scheme.

Apart from this, 35 multimodal logistics parks are also being built under the Bharatmala plan, with an aggregate outlay of ₹46,000 crore. On commissioning, these parks will be capable of transporting 700 million metric tonnes of cargo, increasing India’s capacity to integrate various modes of transport in a cost-effective manner.

India’s port cargo handling capacity has nearly doubled from 800.5 million tonnes annually in 2014 to 1,630 million tonnes in 2024, an increase of 87%. India has also climbed in terms of its world ranking in shipments, from No. 44 in 2014 to No. 22 in 2023. Concurrently, the turnaround time (TRT) at major ports—the time that ships spend at port—has declined significantly from 94 hours in 2013-14 to 48.06 hours in 2023–24. Average berth-day production has gone up by 52% and India is also seeing increased tourism through cruise terminals and lighthouse sites.

These reforms can be said to represent a paradigm shift. India is slowly putting in place the logistical framework necessary to support its dream of becoming an export-led economy. Continued and deepened, these reforms could bridge the gap between India’s expansive trade aspirations and the harsh realities of trading on the international stage, thus making India not just a significant exporter but a truly competitive one.

The author is a research associate, NCAER, New Delhi. Views are personal.

Assam is wary of digital payments. It’s stalling the growth of MSMEs

Data from a recent survey on MSMEs in Assam shows a paradox. While most MSMEs have adopted digital payment systems, a large share of their customers still prefer to pay in cash.

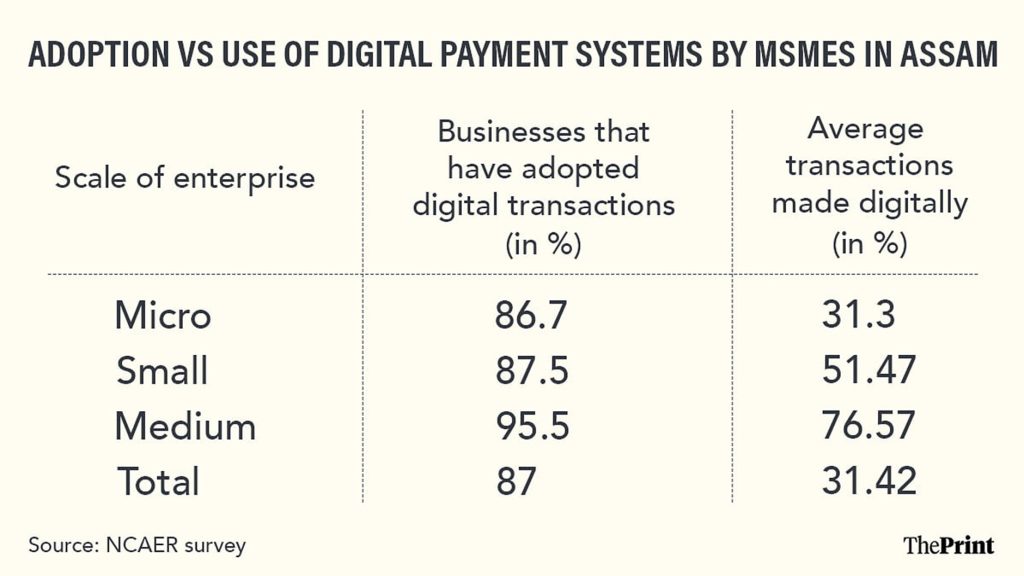
According to a recent survey conducted by the National Council of Applied Economic Research (NCAER) for the Directorate of Economics and Statistics (DES), Assam, nearly 87 per cent of MSMEs in the state have adopted at least one form of digital payment. This is promising.

Among medium enterprises, the adoption rate stands at an impressive 95.5 per cent. Small enterprises report an adoption rate of 87.5 per cent, while micro enterprises follow closely at 86.7 per cent. These figures signal a high level of digital readiness and a willingness among entrepreneurs to embrace change.

However, a closer examination of transaction data reveals a paradox. While the adoption is high, actual use of digital modes of payment remains relatively low. The NCAER survey shows that only about 31.3 per cent of total transactions for micro enterprises are conducted digitally. Small enterprises fare better, with 51.47 per cent of total transactions being digital, and medium enterprises lead with 76.57 per cent. This wide gap between the adoption and active use of digital payment systems tells a larger story—one where the missing link is not the business owner, but the customer.

Why customers don’t pay digitally

The reality on the ground is that even though MSMEs have installed digital infrastructure, a significant share of their customers still prefer to pay in cash. Whether it is a local grocery store, a tea stall, or a tailoring shop, the digital payment option is often available but rarely used. This reluctance among customers stems from a combination of behavioural, technological, and cultural factors.

For many people, particularly in tier-3 towns and rural areas, cash remains a deeply embedded mode of payment. It feels more tangible and trustworthy than a digital transaction that takes place on a screen.

Another important barrier is digital literacy. Many customers, especially the elderly or those with limited education, find mobile payment apps difficult to navigate. Others fear fraud or worry that if something goes wrong with the transaction, there is no clear route for recovery. In some cases, customers believe that using cash gives them more flexibility or helps them manage their spending better.

This gap between the availability of digital options and their actual use is not just a technological issue. It has far-reaching implications for the MSME ecosystem. Digital payments create financial records that are crucial for accessing credit, applying for government schemes, or building business credibility. Without a strong history of digital transactions, many small businesses remain outside the formal financial system. This makes it harder for them to grow, scale up, or survive during economic shocks. In a region like Assam, where MSMEs are central to employment and income generation, this disconnect could hold back broader development.

Bring MSMEs in digital mainstream

It is also worth noting that the Northeast has been identified as a key focus area for India’s future growth. Described by Prime Minister Modi as the “Ashta Lakshmi”—a potential source for the country’s eightfold prosperity—the region is expected to play an important role in national progress. For this vision to become a reality, the MSME sector in Assam and neighbouring states must be brought fully into the digital mainstream. This will not happen if digital readiness is limited to business owners alone. Customers must also become active participants in the digital economy.

So far, most policy interventions have focused on the supply side—on helping MSMEs adopt digital tools, install QR codes, and attend training sessions. These efforts have delivered encouraging results. But the next phase must address the demand side. There is a need to invest in customer awareness, trust-building, and habit formation.

People must be shown that digital payments can be easy, safe, and rewarding. Campaigns in local languages, community-based outreach, and visible grievance redressal systems can all help build public confidence. Above all, digital financial literacy must be treated as a public good—something that empowers citizens and strengthens the economy.

MSMEs in Assam have taken an important step toward a digital future. They have embraced technology and demonstrated their willingness to evolve. But unless customers also make this shift, the benefits of digital transformation will remain limited.

A truly digital economy cannot be built by businesses alone. It requires customers who are informed, confident, and willing to adopt new behaviours. Every stakeholder—from governments and banks to fintech companies and civil society—must focus on turning digital payments into a habit.

The groundwork has been laid, and the opportunity is clear. It is only a matter of bringing the customer on board.

Palash Baruah is a fellow at the National Council of Applied Economic Research (NCAER), Delhi. Poonam Munjal is a professor at NCAER. Views are personal.

    Get updates from NCAER