The climate promise that won’t survive geopolitics

Every climate conference promises finance. Every time, the money arrives in the wrong form, in the wrong channel and in the wrong magnitude. Now the world is trying again. Last month, the G7 finance ministers reaffirmed their unwavering commitment to climate finance. But the real question isn’t whether climate finance can be raised. It’s whether climate finance can survive a world falling apart.

The escalating tensions in West Asia involving Iran, Israel and the US is entering its third month, the surge in defence spending in Europe post-Russia-Ukraine was unprecedented since the Cold War and India’s quiet recalibration of its energy import strategy post reciprocal tariff regime by the US brought with it significant geopolitical implications. None of these events are classified under climate policy. Yet together, they expose a fatal flaw in the world’s newest climate finance goal by proposing a $ 300 billion annual floor situated within a broader mobilisation effort of $ 1.3 trillion per year by 2035 under the New Collective Quantified Goal (NCQG), centred around COP29 in Baku in November, 2024.

However, geopolitical dynamics are inherently uncertain and often transient. Consequently, commitments that may initially appear credible may lose their viability when conditions change. Climate money expands in periods of cooperation. But it contracts under geopolitical stress. And right now, stress is all we have.

The NCQG, which replaces the failed $100 billion commitment from Copenhagen 2009, aims to mobilise $1.3 trillion per year by 2035 from public, private, and multilateral sources. On paper, this is pragmatic. Fiscal constraints mean public money alone cannot bridge the gap. Private capital must be crowded in. Multilateral development banks must lend more. But pragmatism becomes delusion when it ignores how finance actually behaves under pressure.

Here is the uncomfortable truth that no COP communiqué admits: Green finance is neither recession-proof nor war-proof. When geopolitical tensions rise, capital flees to safety. Governments reallocate budgets toward defence, energy security and industrial policy. Long-term climate commitments which require stable, predictable finance over decades compete with immediate political priorities. And they lose. The $ 100 billion goal was undermined by inconsistent definitions, inflated accounting and uneven allocation. The $1.3 trillion goal faces something more dangerous: A world where the rules of cooperation are breaking down.

The NCQG’s reliance on private finance assumes that public interventions can reliably crowd in capital at scale. But developing economies face persistent regulatory uncertainty, currency volatility and weak institutional frameworks all of which translate into higher risk premiums. Capital flows where returns are predictable, not where climate needs are most urgent. This is the mobilization trap: Finance gets counted, but not delivered in forms that are accessible or affordable. The $ 100 billion experiment proved that. There is no reason to believe $ 1.3 trillion will be different.

Even if the money arrives, it arrives skewed. Historically, climate finance has concentrated on mitigation through renewable energy, where revenue streams are clearer, while adaptation remains chronically underfunded. The NCQG does not fix this imbalance, rather, it risks widening it. Worse, by expanding the pool of contributors to include private actors and multilateral banks, the new framework dilutes accountability. The $300 billion floor is tied to developed countries. The remaining $1 trillion depends on mobilisation, a word that has historically meant less scrutiny, not more.

For India, this is not an abstract debate. The country’s development trajectory demands a delicate balance between rapid growth and deep decarbonization. According to estimates from the NITI Aayog report, the financial requirements may reach approximately $ 6.5 trillion over the coming decades to realise the critical double pivots. But access to affordable, reliable finance is precisely what the NCQG cannot guarantee. If climate money retreats during the next global crisis and there will be a next crisis, India will be left holding a transition plan without the capital to execute it. Rather than identifying the issue as a funding gap, it is wise to address this as a design flaw.

The NCQG was supposed to be the moment climate finance grew up moving from billions to trillions, from aid to investment, from developed-country charity to global mobilisation. But scale without resilience is just a larger target to miss. The test is not whether $1.3 trillion can be pledged. It is whether those pledges can survive the next war, the next recession, the next realignment of alliances. Without institutional arrangements that lock in commitments beyond political cycles, the world will repeat the same mistake: Scaling ambition and scaling the gap between promise and delivery.

This article is authored by Suvajit Banerjee, fellow, National Council of Applied Economic Research (NCAER), New Delhi and Stutii Srivastava, financial analyst, University College London. Views are personal.

India’s majority of workers don’t have social security. New labour reforms can change that

The Code’s effects on employment and productivity depend less on its provisions than on how mandates interact with firm size, labour market structure, and worker perceptions of contributions.

Social security – the provision of a safety net against retirement, health expenses, and income shocks – is a foundational principle of formal employment. In India, this net remains out of reach for most workers. With 88% informally employed in 2024, down only marginally from 91% in 2010 (Figure 1), the vast majority of the workforce lacks pension, health insurance, or any income protection. India’s principal social security schemes (that is, Employees’ Provident Fund (EPF) and Employees’ State Insurance (ESI)) cover formal establishments only above a size threshold, structurally excluding informal, casual, and platform workers. 

The Code on Social Security, 2020 is an attempt to address the poor coverage of social security benefits by widening its reach beyond formal establishments, making accumulated benefits portable so workers do not lose protection when they change jobs and bringing gig and platform workers under statutory coverage for the first time.

Figure 1. Informal employment rate: India versus other developing economies

Source: Authors’ compilation based on state government gazette notifications on the Code on Social Security issued by state labour departments (2020-2025).Notes: The map shows the year in which states and union territories issued draft or final rules under the Code on Social Security, 2020. Where both draft and final rules were notified, the year of the first notification is reported.
Source: Authors’ compilation based on state government gazette notifications on the Code on Social Security issued by state labour departments (2020-2025).
Notes: The map shows the year in which states and union territories issued draft or final rules under the Code on Social Security, 2020. Where both draft and final rules were notified, the year of the first notification is reported.

Key changes in the Code on Social Security, 2020

The Code on Social Security, 2020 introduces several structural changes that collectively reshape India’s social security landscape. 

First, it consolidates nine separate labour statutes into a single legislation, replacing multiple overlapping inspectorates with a single Inspector-cum-Facilitator and unifying compliance filings – directly lowering the administrative cost of formal employment. 

Second, the 50% wage rule closes the most exploited salary-structuring loophole, whereby employers inflated allowances to suppress basic wages and shrink EPF, gratuity, and maternity liabilities; any excluded allowances exceeding half of total remuneration are now reclassified as wages.

Third, a new category of fixed-term employees receive full parity with permanent workers from day one, with gratuity accruing on a pro-rata basis after one year rather than the earlier five-year threshold that effectively excluded the entire contract workforce. 

Fourth, gig and platform workers are formally recognised for the first time, with digital aggregators required to contribute between 1% and 2% of annual turnover to a dedicated Social Security Fund. 

Fifth, central and state governments are empowered to frame welfare schemes for unorganised workers, while Aadhaar-seeded, Universal Account number (UAN) based portability ensures accumulated benefits are no longer lost when workers change employers or cross state lines.

Sixth, the Code reverses the earlier perverse arrangement whereby employer default could deny workers their benefits – ESIC (Employees’ State Insurance Corporation) may now pay benefits directly and recover the capitalised value from defaulting employers. 

Seventh, penalties for non-compliance are substantially stiffer. Finally, wage ceilings and contribution rates can be revised by government notification without fresh legislation, making the framework more responsive to economic change.

State-level implementation

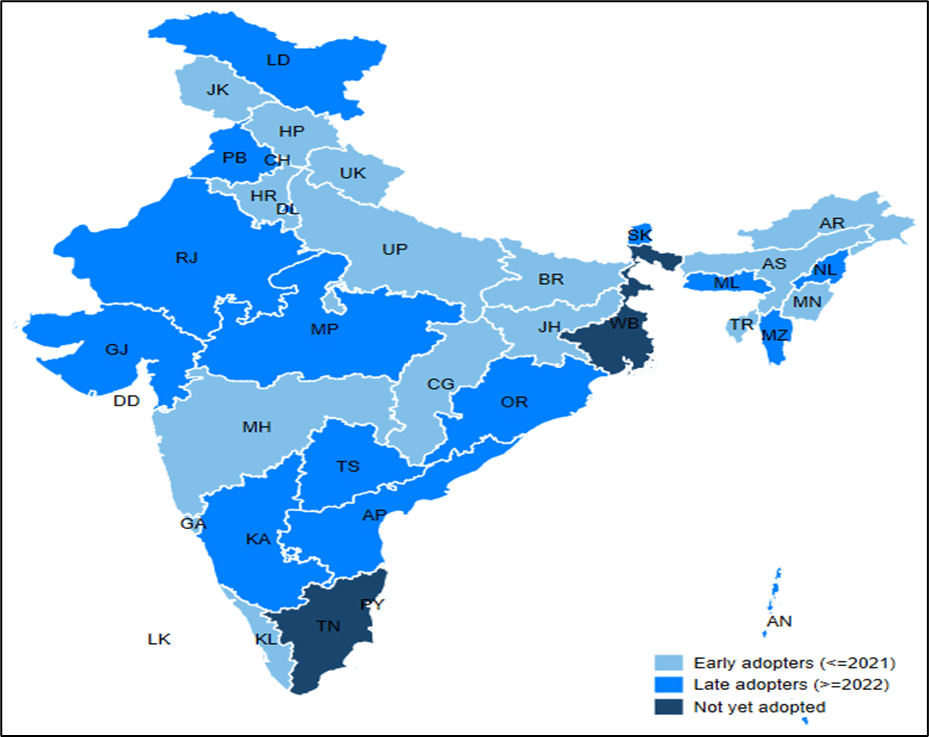
The distribution of states by preparedness for implementation of the new code (Figure2) reveals considerable variation. Early adopters had published draft rules by 2021; a second wave followed in 2022 and after; West Bengal and Tamil Nadu are yet to publish draft rules within the reference period. This uneven adoption reflects India’s federal dynamic – where state capacity, political priorities, and administrative bandwidth determine how quickly central labour legislation translates into operative rules.

Figure 2. State-wise timing of adoption of rules under the Social Security Code

Source: Authors’ compilation based on state government gazette notifications on the Code on Social Security issued by state labour departments (2020-2025).Notes: The map shows the year in which states and union territories issued draft or final rules under the Code on Social Security, 2020. Where both draft and final rules were notified, the year of the first notification is reported.
Source: Authors’ compilation based on state government gazette notifications on the Code on Social Security issued by state labour departments (2020-2025).
Notes: The map shows the year in which states and union territories issued draft or final rules under the Code on Social Security, 2020. Where both draft and final rules were notified, the year of the first notification is reported.

Literature review

A review of the existing literature yields divergent predictions on how social security may affect employment and productivity, as the tables below illustrate – the outcome depends critically on firm behaviour, market structure, and institutional design.

‍Potential impact on employment 

Table 1. Theoretical impact of social security on employment

‍Source: Authors’ compilation.

Evidence from India’s labour market suggests that raising the cost of formal employment consistently drives informalisation. Besley and Burgess (2004) showed that pro-worker amendments to the Industrial Disputes Act reduced formal manufacturing employment while expanding the informal sector. Ahsan and Pages (2009) found that firms typically respond to higher formal labour costs by shifting towards contract and casual arrangements rather than cutting headcount outright.

The most direct evidence on a specific social security component comes from the Maternity Benefit Amendment Act of 2017, which extended paid maternity leave from 12 to 26 weeks for firms with ten or more employees. Banerjee, Biswas and Mazumder (2025) find a decline in employment probability and earnings for targeted women. Bose and Chatterjee (2024) show that women in covered firms were 4.3 percentage points less likely to hold regular salaried jobs and 5.3 percentage points more likely to be in casual or unpaid work. Since the cost falls entirely on employers rather than a shared insurance fund, firms have a strong incentive to reclassify women into ineligible arrangements – meaning the reform measurably harmed those it intended to protect.

Table 2. Theoretical impact of social security on productivity

‍Source: Authors’ compilation.

India’s experience shows how social security mandates interact with policy distortions to shape productivity through capital deepening. Hasan, Mitra and Sundaram (2013) find that Indian firms employ more capital-intensive production techniques than countries at comparable development stages, attributing this to stringent labour regulation that raises the effective cost of formal employment and induces capital substitution even where factor endowments would counsel otherwise. While this raises measured labour productivity, the gains reflect allocative inefficiency rather than genuine technological progress.

Trade liberalisation can reinforce these dynamics through a complementary channel. Hasan, Mitra and Ramaswamy (2007) show that in states with more restrictive labour laws, firms adjusted to competitive pressure through capital substitution rather than employment flexibility, while Sen and Das (2015) add that trade reforms simultaneously reduced the relative price of capital goods. Regulation raising labour costs and trade reform lowering capital costs thus operated in the same direction, with their combined effect exceeding what either would produce independently.

The structural consequence is a diminished employment margin. Adhvaryu, Chari and Sharma (2013) demonstrate that industrial employment in stricter regulation states is less sensitive to demand shocks, as firms having reorganised production around capital-intensive models no longer expand or contract workforces in response to demand fluctuations – a rigidity with significant implications for inclusive growth.

Summary of expected impacts in India

The Code’s effects on employment and productivity depend less on its provisions than on how mandates interact with firm size, labour market structure, and worker perceptions of contributions. On employment, the tiered threshold architecture – EPF at 20 and ESI at 10 workers – may create sharp compliance cliffs that incentivise firms to remain sub-threshold by limiting hiring, fragmenting operations, or substituting contract labour. Where a large informal sector sits outside the regulatory perimeter, tightening formal compliance may lead to informalisation rather than net employment reduction.

On productivity, larger formal firms benefit from reduced worker turnover and skill accumulation, but compliance costs may induce capital substitution that inflates productivity metrics without genuine gains. For small enterprises, threshold incentives may suppress firm growth and foreclose the scale economies that drive long-run productivity.

The overarching prediction on potential impact is divergence: modest gains in large formal firms, growth-suppressing distortions in small enterprises – along with a large share of the workforce engaged in informal work with limited social security benefits. 

Views are personal. 

Based on their new NCAER working paper, Farzana Afridi and other authors will review the new labour law reforms.

This article was originally published on the Ideas for India website. 

The next phase of India’s agricultural transformation must be export-oriented, standards-driven, and value-chain centric

Improving standards compliance, institutional coordination, and farmer-market linkages is critical for enhancing India’s competitiveness in global agri-food trade

India stands at a pivotal moment in global agri-food trade. It is among the world’s largest producers of rice, milk, spices, fruits, fisheries, and several horticulture products, yet its share in global agricultural exports remains modest at around 2.2 per cent. The contradiction is striking: a country with vast production capacity still struggles to fully translate its agricultural strength into sustained global competitiveness.

The challenge is no longer merely about producing more. It is about building resilient, traceable, standards-compliant, and globally integrated agricultural value chains. As international trade increasingly revolves around quality assurance, sustainability, food safety, and logistics efficiency, India must move beyond the traditional “farm-to-market” approach toward a modern “farm-to-global-market” framework.

At the core of this transformation lies value chain strengthening. Indian agriculture continues to be fragmented, dominated by smallholders, and characterised by weak aggregation systems. A substantial share of produce passes through multiple intermediaries before reaching processors or exporters, eroding farmer margins and compromising quality consistency. In several commodities, post-harvest losses remain significant due to inadequate cold chains, storage infrastructure, and grading systems.

This fragmentation becomes particularly costly in export markets, where buyers demand uniformity, traceability, and reliable delivery schedules. Countries competing with India in agri-food exports—such as Vietnam, Thailand, Brazil, and the Netherlands—have invested heavily in integrated supply chains linking farmers, processors, logistics providers, certification agencies, and exporters. India’s agricultural competitiveness will increasingly depend on whether it can replicate similar ecosystem efficiencies.

Evidence from an NCAER study on agro-processing cooperatives and institutional financing further highlights the structural weaknesses in India’s agricultural value chains. The study, covering 304 cooperative units across states including Assam, Gujarat, Kerala, Maharashtra, and West Bengal, found that marginal and small farmers continue to sell a major share of their produce to private traders due to weak aggregation systems and inadequate storage infrastructure. As a result, farmers often fail to benefit from favourable price movements even during bumper harvests. The study also observed that nearly 34 per cent of surveyed agro-processing units were operating below optimal capacity because of irregular raw material supply, shortage of skilled manpower, weak market demand, and limited access to modern machinery. These findings underline the urgent need for stronger producer organisations, cooperative processing systems, warehousing networks, and integrated supply chains to improve India’s export competitiveness.

Farmer Producer Organisations (FPOs), cooperatives, and agri-tech platforms can play a transformative role here. Aggregation at the producer level not only improves bargaining power but also facilitates standardisation, contract farming, digital traceability, and certification compliance. Strengthening linkages between farmers and food processing industries is equally important, especially for high-value exports such as fruits, vegetables, marine products, spices, dairy, and organic produce.

However, stronger value chains alone are insufficient if market access barriers continue to constrain exports. Increasingly, global trade barriers are shifting away from tariffs toward non-tariff measures, particularly Sanitary and Phytosanitary (SPS) regulations and Technical Barriers to Trade (TBT). These standards govern pesticide residues, food safety, animal and plant health, packaging norms, traceability, and sustainability practices.

For Indian exporters, SPS compliance has emerged as one of the most critical bottlenecks. Studies indicate that SPS notifications and trade-related standards can significantly reduce agricultural exports from developing economies by increasing compliance costs and uncertainty. Export consignments from India have periodically faced rejections in advanced markets due to issues relating to residue levels, contamination, or documentation gaps. Such incidents not only cause immediate economic losses but also affect long-term credibility in international markets.

The problem is not that standards are unnecessary. On the contrary, food safety and biosecurity are legitimate global concerns. The issue is that India’s compliance ecosystem remains uneven across regions and commodities. Many small and medium exporters lack access to internationally accredited laboratories, real-time testing facilities, traceability systems, and technical advisory support. Compliance is often treated as an end-stage formality rather than being embedded throughout the value chain.

India therefore requires a strategic shift from reactive compliance to proactive standards competitiveness. This calls for substantial investments in testing infrastructure, digital traceability systems, residue monitoring, cold-chain logistics, and certification ecosystems aligned with global benchmarks such as Codex Alimentarius and WTO SPS frameworks. Export-oriented clusters for specific commodities—such as grapes, shrimp, spices, mangoes, and basmati rice—can serve as models for integrated standards-driven production systems.

Equally important is institutional coordination. India’s agri-trade governance is spread across multiple ministries and agencies including the Ministry of Agriculture, Ministry of Commerce, APEDA, FSSAI, MPEDA, DGFT, state departments, and commodity boards. While each institution performs an important function, coordination gaps often create delays, duplication, and regulatory uncertainty for exporters.

A fragmented institutional architecture is particularly problematic in global trade negotiations and standards diplomacy. Developed economies increasingly shape market access through regulatory frameworks, sustainability norms, and private standards. India needs stronger inter-agency coordination to anticipate emerging global requirements, negotiate equivalence agreements, and support exporters in adapting to evolving standards.

Trade agreements must also move beyond tariff discussions to include regulatory cooperation, mutual recognition arrangements, and SPS harmonisation. Research on SPS barriers suggests that many advanced trade agreements now incorporate deeper regulatory coordination mechanisms, whereas India’s approach has historically remained limited to reiterating WTO provisions. Future trade strategies must therefore integrate market intelligence, standards negotiations, and export facilitation into a unified framework.

There is also a domestic dimension to this debate. Agricultural exports should not be viewed merely as foreign exchange earners, but as catalysts for rural transformation. Stronger agri-food value chains can generate non-farm employment, stimulate food processing, improve farmer incomes, encourage crop diversification, and reduce post-harvest wastage. Export-linked agriculture often creates incentives for higher quality production, better infrastructure, and improved logistics that benefit domestic markets as well.

India’s demographic and dietary transitions globally also present an opportunity. Rising demand for processed foods, nutritionally diverse products, sustainable sourcing, marine products, organic food, and ready-to-eat segments opens new export avenues. India possesses natural advantages in many of these sectors due to climatic diversity, large production bases, and labour availability. But comparative advantage alone no longer guarantees market success. Competitiveness now depends on reliability, quality assurance, logistics efficiency, and institutional responsiveness.

The next phase of India’s agricultural transformation must therefore be export-oriented, standards-driven, and value-chain centric. Production surpluses without market integration will yield diminishing returns. What India needs is an integrated agri-trade strategy that links farmers to global consumers through efficient logistics, strong institutions, compliance ecosystems, and modern supply chains.

India’s competitiveness in global agri-food trade will ultimately depend not only on production volumes, but on its ability to build coordinated institutions, farmer-centric aggregation systems, modern processing infrastructure, and standards-compliant value chains. In the coming decade, global agri-food trade will increasingly reward countries that can combine scale with standards. India has the scale. The challenge now is to build the systems that make that scale globally competitive.

Saurabh Bandyopadhyay and Laxmi Joshi work with NCAER. Views expressed are the authors’ own and don’t necessarily reflect those of Down To Earth.

NCAER News: May 2026

NCAER News is a monthly digest where you can learn about NCAER’s research outputs, its latest events, and offerings.

India Human Development Survey: May 2026

The IHDS Forum is a monthly update of socio-economic developments in India by the IHDS research community, based on the India Human Development Survey, jointly conducted by NCAER and the University of Maryland. While two earlier rounds of the survey were completed in 2004-05 and 2011-12, respectively. Fieldwork for the third round was undertaken in 2022-24 and the data is currently being cleaned and processed.

Click here for previous issues

    Get updates from NCAER