Employability of women outside the labour force

Industry-aligned skilling programmes, convenient modes of commute to the workplace and remote work opportunities will present them with a pathway into the labour force.

In a population, there are individuals who belong to the labour force — either employed or seeking work — and those outside the labour force — neither employed nor seeking work. According to the latest Periodic Labour Force Survey (PLFS 2023-24) data, 40 per cent of India’s population aged 15+, comprising about 415 million people, is outside the labour force. This of course includes people who are still studying (about 118 million).

Employment generation through skill development is among the priori-ties of Budget 2025-26. It is expected that through skilling — either formal training or education/vocational qualifications — people can gain employment and contribute to India’s ambitious economic growth targets. While this supports employability from the supply side, adequate and accessible employment opportunities are also required to enable employability from the demand side.

Since the last four survey rounds, PLFS has been reporting the ‘main reason’ for individuals to be outside the labour force (OLF). The options reflecting employability aspects (from supply and demand sides) include: did not have the required training/qualification/age for work; want to continue study; and non-availability of work at a convenient location. How many people are OLF due to these factors? Are there differences by gender and age?

Females comprise a larger share of those OLF. There are nearly twice as many females over males in the 15-29 age group, jumping to nearly 19 times in the 30-59 age group.

Lack of skills, training

Not having the required training/qualification/age for work indicates an inability to meet the available job-role criteria due to potential skill or age-related gaps. Among the youth, females stating this as the reason for being OLF is nearly twice as that of males. The issue aggravates among women in the older cohort of 30-59 years, where females stating this is nearly 32 times that of males. In all, around 1.4 million women of working age are OLF because of this reason, in comparison to about 4,16,000 men.
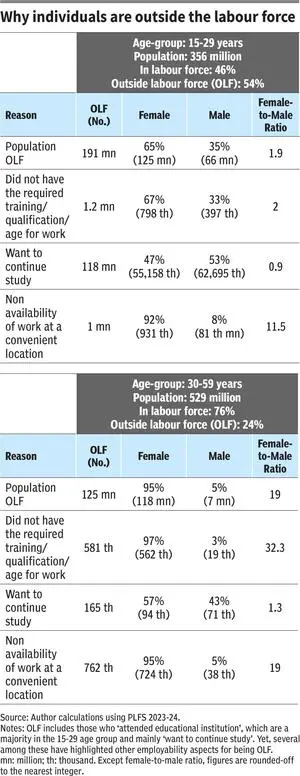
While ‘not having the required training/qualification/age for work’ may not be the topmost reason for either males or females to be OLF, but the sheer magnitude of the problem indicates that it cannot be ignored either.

Regarding acquisition of skills through their ‘want to continue study’ — this factor is relatively prominent among young males for being OLF, and relatively prominent among females in the older cohort. In all, around 55 million women and 63 million men, of working age, are OLF because of this reason.

Non-availability of work at a convenient location indicates a spatial mismatch — jobs may not be available where there are people available to work. This issue is highly pronounced for females — stated by nearly 12 times more females over males in the 15-29-year age group, and 19 times more females in the 30-59-year age group. In all, around 1.7 million women of working age are OLF because of this reason, in comparison to about 1,19,000 men.

Overcoming the barriers

Available data indicate that many individuals, particularly females, can be brought to participate in the labour force by overcoming their barriers to current and future employability. This will help inch closer to the Budget 2025-26 target of 70 per cent women in India’s workforce.

When a large share of the population ‘wants to continue study’, the aim should be to help this investment be remunerative through gainful future employment. We want to avoid a situation where individuals are not in the labour force because they ‘did not have the required training/qualification for work’. It is therefore important that industry-aligned skilling programmes, with dedicated counselling and mentorship, are promoted — including reskilling and upskilling programmes for older females in the 30-59 age group.

Once individuals have the requisite skills, convenience of commute to the place of work is an equally important criterion to facilitate employment. Females are particularly worse-off in this regard, given that many choose not to work because of ‘non-availability of work at a convenient location’ — indicating the relative difficulty females face, over males, in migrating or travelling long distances for work. This finding holds for females in both urban and rural areas. Working women hostels, accessible and reliable transportation facilities, institutional support for safety and security, as well as job opportunities in rural pockets are all necessary. However, harnessing the power of digital technologies to offer flexible/remote work opportunities can help overcome issues around difficulty of commute altogether.

A positive externality of the above measures is for the large section of women who are outside the labour force due to care commitments in home-making (about 58 million women in the 15-29-year age group and 99 million women in the 30-59-year age group). Re/up-skilling opportunities along with remote work options could present them with a pathway into the labour force, and balance between home and work commitments. Other infrastructure, like care facilities, can go a long way in improving labour force participation.

Dayal is Fellow and Bhandari is Professor at National Council of Applied Economic Research (NCAER). Views are personal.

Green hydrogen is the missing link in India’s net-zero transition

The National Green Hydrogen Mission is a strong first step, but India must adopt a whole-of-economy approach to scale its efforts.

As the world races to address the climate crisis, green hydrogen emerges as both a promising solution and a potential disruptor in the clean energy landscape. Unlike conventional hydrogen derived from fossil fuels, green hydrogen is produced using renewable energy sources and emits zero carbon in the process. For India—committed to achieving net-zero emissions by 2070—green hydrogen is not merely an opportunity; it is a necessity.

Why green hydrogen matters

Green hydrogen, produced using renewable electricity through electrolysis, is gaining global attention as a versatile and zero-emission fuel. Unlike grey hydrogen derived from fossil fuels, green hydrogen offers a clean energy alternative that can be applied across diverse sectors—transportation, industry, and power. It acts as both a fuel and an energy carrier, capable of stabilising grids by storing excess renewable power and meeting peak demand. More importantly, it plays a pivotal role in decarbonising “hard-to-abate” industries such as steel, cement, ammonia, and long-haul transport, where direct electrification is impractical or costly. For a developing country like India, green hydrogen is not just a technological opportunity—it is an essential enabler for sustainable growth. It bridges the gap between the present carbon-intensive infrastructure and a future powered by renewables. By integrating green hydrogen, India can balance economic development with environmental goals, making strides toward its 2070 net-zero target. The adoption of green hydrogen also offers energy security, reducing dependency on imported fossil fuels. As climate change intensifies, India must embrace green hydrogen as a strategic solution—both to meet its international climate commitments and to transition into a resilient, clean-energy economy.

For India, green hydrogen offers a pathway to reconcile economic development with environmental stewardship.

A bold beginning

India’s National Green Hydrogen Mission, launched in January 2023 with Rs 19,744 crore, aims to produce 5 million metric tonnes (MMT) of green hydrogen annually by 2030. The initiative supports over 125 GW of renewable energy and could reduce 50 MMT of CO2 per year while creating 600,000 jobs. Financial support under the SIGHT program and pilot projects in steel and shipping show India’s intent to lead in green hydrogen. These steps aim to align clean energy goals with national development..

To drive this mission, the Strategic Interventions for Green Hydrogen Transition (SIGHT) program offers financial incentives—Rs 17,490 crore to support production and electrolyser manufacturing. Pilot projects in sectors like shipping and steel are already underway, including plans to retrofit vessels and develop green ammonia refuelling hubs at key ports. These are not just technical experiments; they are strategic moves to anchor India’s place in the global hydrogen economy.

India’s renewable advantage

India’s vast solar and wind resources provide a strong base for green hydrogen production. With 180 GW of renewable energy already installed and a 2030 target of 500 GW, India can produce green hydrogen affordably. Large corporations like Reliance and Adani plan major investments, potentially increasing production beyond the government’s targets. These efforts support India’s climate goals under the Paris Agreement, helping reduce carbon intensity and dependence on coal.

Green hydrogen could become the cornerstone of India’s clean energy strategy, combining low costs with global competitiveness.

Staying competitive in a global race

Green hydrogen costs currently range between $2.7-8.8/kg but are expected to fall to $2-6/kg by 2030. Countries like China are scaling fast, lowering global costs through technology and manufacturing dominance. India must stay competitive by expanding domestic electrolyser production, building full hydrogen value chains, and forming strategic partnerships. Government incentives—such as capital subsidies and tariff waivers—could help green hydrogen reach parity with fossil-based alternatives. With coordinated efforts, India can be a leader in the global hydrogen economy.

To stay competitive, India must act swiftly and strategically. Building robust domestic manufacturing capabilities is crucial—not just for electrolysers but for the entire green hydrogen value chain. India must also actively engage in global partnerships, secure access to critical minerals, and create a business environment that attracts both domestic and foreign investment.

Overcoming key challenges

India faces several hurdles—high capital costs, raw material dependence, safety issues, and limited infrastructure for hydrogen transport and storage. Financing is another major concern, especially in emerging markets. Innovative funding models and policy support are needed to attract investments. Environmental oversight is also essential, as hydrogen could indirectly affect greenhouse gases like methane and ozone. India must ensure robust monitoring to maintain its green credentials. Overcoming these issues is key to unlocking the full potential of green hydrogen.

Environmental safeguards also need to evolve. Though hydrogen is a clean fuel, it can indirectly impact greenhouse gas levels by affecting methane and ozone concentrations. India must therefore adopt strong monitoring and regulatory mechanisms to ensure that green hydrogen truly remains green.

A call to action

The National Green Hydrogen Mission is a strong first step, but India must adopt a whole-of-economy approach to scale its efforts. Integrating green hydrogen into national policies, trade strategies, and urban planning is crucial. International partnerships, such as with the EU, can support technology transfer and market access. India has a unique chance to lead the global green hydrogen movement. But quick action, bold investments, and strategic planning are needed to ensure long-term success and global leadership in clean energy.

India has a window of opportunity to lead the world in green hydrogen—but this window will not stay open forever. With bold leadership, targeted investments, and strategic global engagement, India can position itself as a clean energy powerhouse, proving that climate responsibility and economic ambition can go hand in hand.

Anushka Bandyopadhyay and Raktimava Bose is associated with National Council of Applied Economic Research (NCAER) and Debanka Samanta is associated with The Energy and Resources Institute (TERI)

Views expressed are author’s own and don’t necessarily reflect those of Down To Earth.

Fixing fault lines in wastewater market

India faces a significant wastewater challenge, with over 70% of urban wastewater untreated. The market is projected to grow from $13.1 billion in 2023 to $23.8 billion by 2033, driven by urbanization and industrial demand.

In a country where over 70% of urban wastewater is untreated and flows into rivers, lakes, and coastal zones, India’s wastewater challenge is not merely ecological but existential. India’s water and wastewater treatment market, valued at $13.1 billion in 2023, is projected to reach $23.8 billion by 2033, with 6.2% compound annual growth rate. This reflects accelerating urbanisation, climate fragility, and growing industrial water demand.

In 2020, urban centres generated 72,368 million litres per day (MLD) of sewage, but the installed treatment capacity was just 31,841 MLD. As of December 2023, progress remains uneven across states: Maharashtra treats over 8,000 MLD, while Bihar lags at under 400 MLD despite similar population pressures. This imbalance highlights a critical paradox — while India pursues piped drinking water to 146 million rural households through the Jal Jeevan Mission (JJM), it loses billions of litres daily due to inadequate wastewater treatment and reuse.

The industrial sector is a key player, with thermal power plants consuming 87.8% of all industrial water. Sectors like food and beverage, pharmaceuticals, textiles, and chemicals contribute substantially to the demand for high-purity water and treatment technologies. The industrial wastewater treatment sub-market was worth $1.44 billion in 2023 and is expected to grow to $2.4 billion by 2033.

Sewage treatment remains the second-largest segment, projected to grow from $5 billion in 2023 to $9.08 billion by 2033. Water treatment, including desalination and recycling, leads the market, as it expanded from $6.65 billion to $12.37 billion over the same period. This growth reflects mounting pressures from urban expansion, potable water demand, and environmental regulations.

Yet, despite the market potential, policy fragmentation persists. Even after consolidating water-related departments into the ministry of jal shakti in 2019, overlapping jurisdictions, slow state-level execution, and limited technical capacity derail many projects. By 2023 nearly 25% of sanctioned sewage treatment plants (STPs) were either under construction or stalled.

Our wastewater sector is shifting from traditional chemical treatments to membrane-based solutions like reverse osmosis, sequencing batch reactors, and membrane bioreactors (MBR). These technologies are driven by stricter compliance costs and mandates for water reuse. But with MBR systems costing up to Rs 1.2 crore per MLD and operational costs of `1-1.5 lakh per month per MLD, small municipalities and lower-income states face big barriers.

Public-private partnerships offer partial relief, with states like Tamil Nadu and Gujarat leading desalination efforts. Gujarat’s plants contribute over 100 MLD to urban supply. But decentralised systems for peri-urban clusters and small towns remain largely absent from policy focus. Advanced technologies like real-time monitoring and AI-enabled compliance tools are concentrated in large urban projects.

Government funding for water and sanitation is sizeable but insufficient to bridge the infra gap. In FY24, allocations included Rs 70,000crore for JJM, Rs 15,000 crore for Atal Mission for Rejuvenation and Urban Transformation (AMRUT) 2.0, and `20,000 crore for Namami Gange. Yet, only 67% of AMRUT 2.0 funds were utilised, and over Rs 6,000 crore of JJM grants were unspent.

Funding skews toward megacities. Smaller cities, responsible for over 60% of untreated wastewater, are under-resourced. Private investors cite high operational costs and uncertain returns.

Meeting the sector’s $23.8-billion potential by 2033 will require innovative financing like green bonds, water credits, and blended finance. Designing pricing strategies that encourage efficiency without burdening low-income users is a key challenge.

Flagship schemes like AMRUT 2.0 and Namami Gange have set up over 1,000 sewage and common effluent treatment plants. But success is often measured by infrastructure completion rather than performance. Central Pollution Control Board data (2023) revealed that 40% of STPs failed to meet discharge standards.

Mandates like zero liquid discharge (ZLD) for high-polluting sectors (tanneries, dyeing units, sugar mills) are steps forward, but enforcement remains inconsistent. For example, only 13% of textile units in Punjab and Haryana were ZLD-compliant by mid-2023. State-level variations are stark: Maharashtra, Gujarat, and Tamil Nadu exceed 75% of their planned STP capacity, while Jharkhand and Tripura are below 15%. A performance-linked federal grant system that rewards outcomes could improve accountability.

The greatest opportunity in India’s wastewater sector lies in embracing the circular economy — reduce, reuse, recycle. Recycled wastewater is used for horticulture, construction, industrial cooling, and flushing in cities like Pune and Surat. But nationally, less than 20% of treated wastewater is reused. Circular models enable energy recovery, nutrient extraction, and sludge-to-brick conversion. Pune’s use of sewage sludge biogas to fuel buses is a notable example, though still rare. Policy focus must shift from wastewater disposal to resource recovery, transforming every litre of into a potential source of energy, fertiliser, and reusable water.

India faces critical questions for the next decade: Can we transition from building infrastructure to delivering performance? Will pricing reforms drive innovation? Can India lead the Global South in circular wastewater economies? With 70% untreated discharge, a $23.8-billion market, and mounting climate risks, India’s wastewater sector is central to its ecological resilience and water security. Success will depend on policy realism, fiscal innovation, and a cultural shift — from viewing wastewater as waste to recognising it as wealth.

By Souryabrata Mohapatra, Amit Mitra & Sanjib Pohit, Respectively assistant professor, School of Liberal Arts, IIT Jodhpur, and research associate & professor, National Council of Applied Economic Research. Views are personal.

India Human Development Survey: May 2025

The IHDS Forum is a monthly update of socio-economic developments in India by the IHDS research community, based on the India Human Development Survey, jointly conducted by NCAER and the University of Maryland. While two earlier rounds of the survey were completed in 2004-05 and 2011-12, respectively. Fieldwork for the third round was undertaken in 2022-24 and the data is currently being cleaned and processed.

Click here for previous issues

Impact of a Drought in South India on the Indian Economy: An Application with the TERM-India Model

Unlike other countries, economy-wide modelling in India generally has treated the Indian nation as one entity even though one recognises that the states/regions differ significantly in respect of their resource base and factor endowments. Of course, a few models at the state level exist.  However, these models do not capture the transmission channels from the rest of India since these types of models treat the rest of India as merely a balancing mechanism. A few of the existing research studies for India using a Computable General Equilibrium model use a top-down approach to analyse state-level issues. A major drawback of this approach is the lack of consideration for region-specific price effects, for which the effect of state-sponsored programmes or imperfect factor mobility or disparities across regions cannot be captured in these models. Our study is the first attempt to develop a bottom-up model–TERM (The Enormous Regional Model)-for India. The model is utilised to understand the implications of a hypothetical drought in a region (South India) and how the effect transmits to the rest of India, through a 52 commodity sector TERM model for 7 regions in India encompassing 31 states and Union Territories. Each region within the model has its own input–output database and agricultural product mix, and the simulation in this static TERM model depicts short-run effects. The study shows that despite being limited to some states in South India, the drought is likely to have a moderate impact on the Indian economy. Both GDP and employment are going to be affected at the national level, and the parameters are affected in several states in India, that are not necessarily situated in the southern region. The interconnectedness of the regions causes reduction in employment and the wage rate, leading to migration of labour and redistribution of investment.

    Get updates from NCAER